Beotimmok Refinancing Loan: Core Target and Basic Principles
This is the draft body text for “1. Beotimmok Refinancing Loan: Core Target and Basic Principles,” applying Naver Blog’s highly readable mobile line breaks and empathetic storytelling.
- Beotimmok Refinancing Loan: Core Target and Basic Principles
Every month from the bank account## Beotimmok Refinancing Loan: Core Target and Basic Principles
If the monthly interest burden has grown due to high jeonse loan interest rates from commercial banks, the Housing and Urban Guarantee Corporation/Korea Housing Urban Fund’s Beotimmok Jeonse Refinancing Loan can be a representative alternative. This structure reduces housing cost burdens by converting existing high-interest jeonse loans taken from commercial banks into low-interest government policy products.
- Basic Operating Principle: How to Switch?
The Beotimmok refinancing loan is not a method where money is deposited into an individual’s personal bank account for them to pay back directly.
- Fund loan screening and approval: Eligibility screening is conducted through Housing and Urban Fund trustee banks.
- Direct repayment of the existing loan: Once refinancing is approved, the new Beotimmok loan amount is wired directly to the existing commercial bank jeonse loan account to pay off the existing loan.
- Conversion of interest rates and terms: Switching from the existing bank’s variable and high interest rate system to a policy low-interest rate of around 2% per year (varying by income and deposit tier) immediately reduces the interest paid each month.
- Core Support Targets (Application Eligibility Criteria)
Not all jeonse loan users can switch, as applicants must simultaneously meet non-homeowner requirements as well as income and asset criteria.
Household head requirement: As of the loan application date, the applicant must be a household head aged 19 or older, and all household members must be non-homeowners.
Income criteria: Combined total annual income of the couple must be 50 million KRW or less (however, 60 million KRW or less for newlywed households, multi-child households, and households with 2 or more children; separate criteria apply to youth-dedicated loans).
Asset criteria: The net asset value of the applicant and spouse must be equal to or less than the average value of all households in the 3rd income quintile (usually in the mid-300 million KRW range).
Target housing:
Exclusive residential lease area must be 85㎡ or less (100㎡ or less for eup/myeon areas that are not urban areas, excluding the capital area).
Lease deposit must be 300 million KRW or less in the capital area and 200 million KRW or less in non-capital areas for general households (relaxed upper limits apply to newlyweds and multi-child households).
Existing loan conditions: The existing loan must be a ‘regular housing jeonse loan’ handled by a primary tier-1 commercial bank, with no history of delinquency or grounds for credit disqualification. Credit loans and non-banking sector loans are not eligible for refinancing.
- Essential Checkpoints When Switching
Prepayment penalty: You must compare the actual savings against the sum of the prepayment penalty incurred by terminating the existing commercial bank loan early and the guarantee fee incurred when taking out the new Beotimmok loan.
Timing: It is generally necessary to confirm in advance through a trustee bank counter whether the requirements are met to proceed with an increased-amount refinancing at the time of jeonse contract renewal, or to refinance according to the remaining contract period during the lease term.
Digging Into the Most Confusing ‘Non-Homeowner Household Head’ Eligibility Requirements
This is the body text of Section “2. Digging Into the Most Confusing ‘Non-Homeowner Household Head’ Eligibility Requirements,” which clearly organizes the administrative standards that Naver Blog readers search for and find most confusing.
Digging Into the Most Confusing ‘Non-Homeowner Household Head’ Eligibility Requirements
When looking into refinancing a Beotimmok jeonse loan, the first and highest hurdle is precisely the ‘non-homeowner household head’ requirement.
We clearly explain the core criteria where eligibility and disqualification can easily hinge on a single detail, answering questions like “Can I apply if I live alone?”, “Can I split the household if I am living with my parents?”, and “Is it okay if I have a pre-sale right won through subscription housing?”
- Actual Scope of ‘All Household Members Being Non-Homeowners’
The basic rule of the Beotimmok loan is that not only the loan applicant but also all household members registered on the resident registration certificate must be non-homeowners.
- Scope of household members: Applicant, spouse (combined even if resident registrations are separated), lineal ascendants (parents, grandparents), lineal descendants (children, grandchildren), and their spouses
- Ownership of pre-sale rights and occupancy rights:
- Even if one does not own physical residential property, housing pre-sale rights or cooperative member occupancy rights held by the applicant and household members are also considered homeownership.
- In other words, if you hold a pre-sale right prior to move-in, you may be excluded from non-homeowner status, so you must verify the acquisition timing and right type beforehand.
- Exceptions for recognizing homeownership:
- When lineal ascendants (such as parents) aged 60 or older own a home, some public housing or policy products may consider the applicant non-homeowners; however, the Beotimmok jeonse loan strictly adheres to the principle that an applicant is not recognized as a non-homeowner household head if parents own a home. Therefore, if registered together with parents on the resident registration, splitting the household prior to applying for the loan is essential.
- Single Household Head vs. Combined Household Criteria (Age-Specific Conditions)
For single-person households living alone (single household heads), the approach varies completely depending on age.
- Single household heads aged 30 or older:
- If forming an independent household (single household head), you can apply for the general Beotimmok jeonse refinancing loan without any special additional requirements.
- Unmarried single household heads under the age of 30:
- In principle, the general Beotimmok loan restricts applications from single household heads under 30 years of age.
- However, if you have a history of supporting at least one lineal ascendant in the same household for 6 months or longer, or if you meet the conditions for the ‘Youth-Dedicated Beotimmok Jeonse Loan’ (aged 19 to 34), you can apply through the youth-dedicated track.
- Scope of Recognition for Prospective Household Heads (Engaged Couples, etc.)
Even if an applicant is not currently a household head because they are listed as a household member under their parents on the application date, exceptions are recognized in certain cases.
- Prospective newlyweds (Newlywed-Dedicated / General Beotimmok):
- Although not currently a household head on the application date, you can apply in advance as a prospective household head by proving (wedding hall contract, wedding invitations, etc.) that you plan to complete marriage registration and become independent as a household head within 3 months from the scheduled wedding date.
- However, after the loan is disbursed, you must submit a resident registration certificate showing the completed marriage registration within the deadline to prove after the fact that you have actually become a non-homeowner household head.
- Household separation scheduled for relocation:
- Even when planning to move into a new jeonse home on the balance payment date (refinancing execution date) and establish a single household head, you can check whether processing is possible through bank pre-screening consultations.
Summary Checklist
| Category | Recognition Criteria and Precautions |
|---|---|
| Applicant and Spouse | Considered a single unit even if resident registrations are separated (ineligible if spouse owns a home) |
| Cohabiting Family on the Certificate | All individuals listed together on the certificate, such as parents and children, must not own a home |
| Pre-sale/Occupancy Rights | Classified as homeowners in principle if held |
| Single Household Head Age | Age 30 or older can be single; age under 30 should consider youth-dedicated products |
Practical Tip:
When you issue a resident registration certificate, check in advance whether anyone among the family registered with you holds even a 1% share of a home or possesses a pre-sale right. If there is a homeowner among family members, it is safe to complete moving-in notification and household separation for valid reasons at least 1 to 2 months prior to the loan application.
Eligibility Criteria for Income, Assets, and Target Housing
This is the body text of Section “3. Eligibility Criteria for Income, Assets, and Target Housing,” organizing income, asset, and housing requirements into tables and detailed explanations so that Naver Blog readers can assess their eligibility at a glance.
Eligibility Criteria for Income, Assets, and Target Housing
Once you meet the non-homeowner household head requirement, the next hurdles to pass are the government fund regulations regarding ‘money (income/assets)’ and ‘housing (area/deposit)’.
As the Beotimmok Jeonse Loan is a policy product designed for working-class housing stability, the upper limits on income and assets are clear, and the target housing for refinancing must also fall within designated specifications.
- Couple Combined Annual Income Requirements (Differentiated by Type)
Income is screened by combining the income of the applicant and the spouse for the previous year (or the most recent 1 year).
| Household Type | Income Upper Limit | Note |
|---|---|---|
| General Single / General Household | Couple combined 50 million KRW or less | Standard criteria |
| Newlywed Household (Within 7 years of marriage) | Couple combined 75 million KRW or less | Significantly relaxed compared to general Beotimmok |
| Multi-child / Households with 2 or more children | Couple combined 60 million KRW or less | Upper limit relaxed according to number of children |
| Employees of Public Institutions Relocating to Innovation Cities, etc. | Couple combined 60 million KRW or less | Policy support target group |
- Income calculation method: For earned income earners, it is based on the total salary on the withholding tax receipt; for business income earners, it is based on the income amount on the certificate of income amount.
- Notes for job changers and retirees: If you have recently changed jobs, are a freelancer, or are currently unemployed, the recognized income may differ depending on the proof method, so Housing and Urban Guarantee Corporation (HUG) or Korea Housing Finance Corporation (HF) standards must be checked in advance.
- Net Asset Value Criteria (As of 2026)
Even if income is low, fund loan usage is restricted if held assets (real estate, financial assets, automobiles, etc.) are substantial.
- Threshold amount: Combined net asset value of the applicant and spouse must be 345 million KRW or less (based on the average value of all households in the 3rd income quintile from Statistics Korea’s Household Financial Welfare Survey, subject to minor periodic announcement changes)
- Net asset calculation method:
- Precautions:
- The existing commercial bank jeonse deposit is also captured as a financial asset during asset evaluation, but the existing bank loan tied to it is deducted and reflected as a liability.
- Possessing high-priced foreign vehicles (when exceeding the vehicle value limit) or large amounts of stocks and deposits may result in disqualification during the asset screening phase.
- Target Housing Eligibility Requirements (Area and Deposit)
Not all jeonse homes are eligible for refinancing. The home’s ‘official ledger purpose’, ‘exclusive residential area’, and ‘lease deposit’ must all meet the standards.
- Exclusive residential area:
- Exclusive area of 85㎡ or less (typically around the size of a standard 25-pyeong national housing apartment)
- Eup or myeon areas that are not urban areas, excluding the capital area: up to 100㎡ or less permitted
- Residential officetels can also apply if the exclusive area is 85㎡ or less (unauthorized/violating buildings such as neighborhood living facilities are ineligible)
- Lease deposit upper limit:
- Capital area (Seoul, Gyeonggi, Incheon): Jeonse deposit 300 million KRW or less
- Non-capital area (outside capital area): Jeonse deposit 200 million KRW or less
- However, for newlywed and multi-child households, relaxed deposit limits apply up to 400 million KRW in the capital area and 300 million KRW in non-capital areas.
Practical Checklist Tip
Mandatory Verification of Certified Real Estate Register and Building Ledger
Even if the area on the lease contract matches, refinancing approval will be rejected if the building ledger indicates ‘neighborhood living facility’ or ‘violating structure’. Furthermore, if the deposit size exceeds the regional upper limit (capital 300 million KRW, non-capital 200 million KRW) by even 1 KRW, applying itself becomes impossible, so the contract must be written so that it does not exceed the deposit cap when renewing with an increased deposit.
Beotimmok Jeonse Loan Refinancing Detailed Terms & Loan Limits
If you are currently using a jeonse loan with high interest rates from a primary commercial bank, you can significantly reduce your interest burden by refinancing (switching) to the Housing and Urban Fund’s Beotimmok Jeonse Loan (General, Youth, Newlywed). Unlike new applications, refinancing loans come with separate conditions and evidentiary procedures that must be satisfied, so key criteria must be reviewed in advance.
- Basic Eligibility Conditions for Beotimmok Refinancing
Refinancing is possible only when all of the following detailed requirements are met while satisfying the basic income and asset requirements of the Beotimmok jeonse loan.
- Existing loan requirements: It must be a guaranteed jeonse loan handled by a primary tier-1 bank (collateralized by a guarantee certificate from HF Korea Housing Finance Corporation or HUG Housing and Urban Guarantee Corporation).
- Secondary financial sector loans, tenant lease funds in the form of credit loans, or products with complicated pledge arrangements may be excluded from refinancing.
- Loan usage period: The existing jeonse loan must have been used normally for at least 3 months after execution. (Must have no history of delinquency)
- Household head requirement: A non-homeowner household head aged 19 or older as of the loan application date (including single household heads; age 34 or younger for youth-dedicated).
- Income and asset criteria:
- General Beotimmok: Couple combined annual income of 50 million KRW or less (60 million KRW or less for households with 2 or more children, etc.)
- Newlywed Beotimmok: Couple combined annual income of 75 million KRW or less
- Youth-Dedicated: Annual income of 50 million KRW or less (single household heads allowed)
- Assets: Net asset value of 345 million KRW or less as of 2026 (announced annually based on the 3rd quintile income average)
- Target Housing Conditions
- Exclusive residential area: Exclusive area of 85㎡ or less (100㎡ or less for eup/myeon areas that are not urban areas, excluding the capital area).
- However, an exclusive area of 60㎡ or less applies to youth single household heads.
- Lease deposit upper limits:
- General Beotimmok: 300 million KRW or less in the capital area, 200 million KRW or less in non-capital areas (400 million KRW or less in the capital area, 300 million KRW or less in non-capital areas for households with 2 or more children).
- Newlywed Beotimmok: 400 million KRW or less in the capital area, 300 million KRW or less in non-capital areas.
- Youth Beotimmok: Deposit of 300 million KRW or less.
- Refinancing Loan Limit Calculation Method
The loan limit approved upon refinancing is determined by the lowest amount among the following three items.
| Category | General Beotimmok | Youth-Dedicated Beotimmok | Newlywed-Dedicated Beotimmok |
|---|---|---|---|
| Maximum Limit per Product | Capital 120 million KRW / Non-capital 80 million KRW
(2 or more children: Capital 300 million / Non-capital 200 million) |
Up to 200 million KRW | Capital up to 300 million KRW /
Non-capital up to 200 million KRW |
| Ratio Against Deposit | Within 70% of new/renewal deposit
(Within 80% for multi-child households) |
Within 80% of deposit | Within 80% of deposit |
| Existing Loan Balance | Within the principal balance of the existing bank jeonse loan | Within the principal balance of the existing bank jeonse loan | Within the principal balance of the existing bank jeonse loan |
Core Precautions for Refinancing Limits
- A refinancing loan cannot be applied for in an amount exceeding the principal balance of the existing loan. In other words, even if the 80% deposit limit calculation yields 160 million KRW, refinancing will only be approved up to 120 million KRW if the current bank loan balance is 120 million KRW.
- The final calculated amount may be reduced based on the guarantee limit of the guarantee institution (HF/HUG), individual income-based DTI, and credit scores.
- Refinancing Application Timing and Mandatory Procedures
- Application timing:
- Refinancing is possible even before the maturity of the existing loan as long as 3 months have passed, but in practice, proceeding at the time of lease contract renewal (1 to 2 months prior to maturity) is smoothest in terms of prepayment penalties and pledge release procedures.
- Repayment method:
- Upon approval of refinancing, the loan proceeds are not disbursed into the applicant’s account, but rather transferred directly from the new fund trustee bank to the existing lending bank to be fully repaid on the same day.
- Key required documents:
- Original lease contract (fixed date certified), resident registration certificate/abstract, certificate of income amount, certificate of employment
- Financial transaction confirmation for the existing jeonse loan (must state loan type, original loan date, and current balance), debt certificate
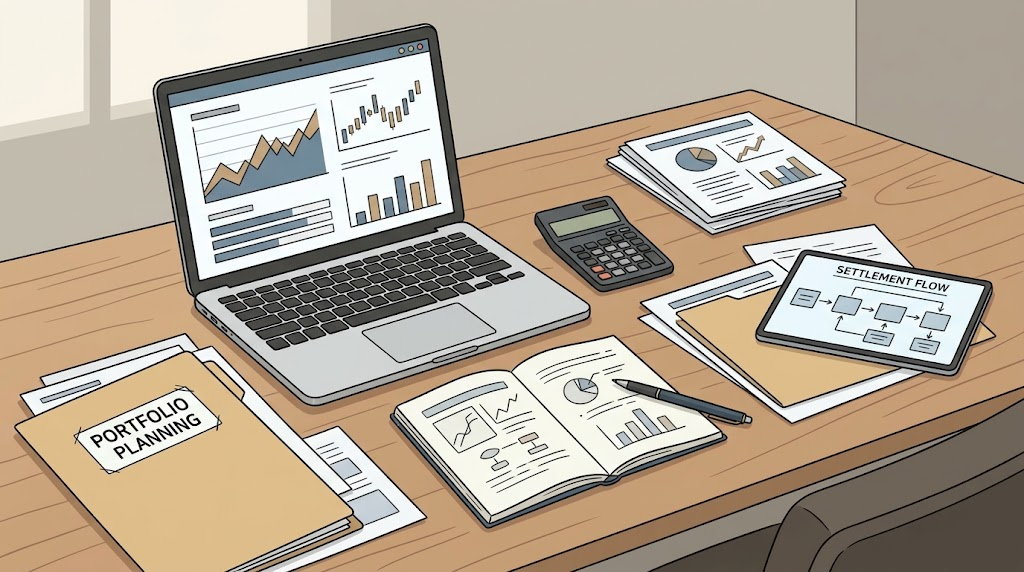
Essential Check Before Visiting the Bank! Application Procedures and Required Documents
Refinancing a Beotimmok jeonse loan involves more demanding paperwork and administrative steps than an ordinary new loan. Because existing loan repayment coordination and fund guarantee screening occur simultaneously, messing up the sequence or missing even a single document can disrupt the balance payment schedule.
To prevent unnecessary trips to the bank counter, we summarize the official 4-step application procedure and the essential document preparation checklist.
- 4-Step Beotimmok Refinancing Application Procedure
Plaintext
[Step 1] Pre-qualification verification and application via Gigeum-e-Deundeun
▼
[Step 2] Housing and Urban Guarantee Corporation (HUG) preliminary asset screening approval (qualified determination)
▼
[Step 3] Visit trustee bank branch and submit documents for final review
▼
[Step 4] Refinancing approval and loan execution (Direct loan repayment from new bank → existing bank)
- Gigeum-e-Deundeun Online Pre-Application (Mandatory Precedent)
Before visiting a bank without preparation, complete a refinancing loan application on the Housing and Urban Fund ‘Gigeum-e-Deundeun’ website or mobile app.
Proceed with scraping using an accredited certificate (joint/financial certificate) to enter basic personal information and income eligibility.
- Check Preliminary Asset Review Results (HUG Review)
Within 1 to 3 business days after applying, a KakaoTalk/SMS notification such as ‘Qualified’ or ‘Proceeding with Individual Review’ will arrive.
Immediately after receiving the ‘Pre-qualification Qualified’ decision, you must visit the designated trustee bank branch.
- Visit Handling Trustee Bank and Submit Main Documents
Visit the branch chosen on Gigeum-e-Deundeun among the five major trustee banks of the Housing and Urban Fund (Woori, Shinhan, Kookmin, Hana, NH Nonghyup).
For refinancing, the process can be conducted at any of the five major trustee banks, even if it is not the bank that handled the existing jeonse loan.
- Post-Asset Review and Direct Repayment Execution
Once the loan screening is passed and the execution date (contract date) arrives, the new Beotimmok loan funds are deposited directly into a virtual account at the existing lending bank without passing through the applicant’s account, extinguishing the existing debt.
- Essential Document Preparation List at a Glance
All documents must be issued showing all 13 digits of the resident registration number, and only those issued within 1 month as of the loan application date are valid.
① Identification and Non-Homeowner Household Head Verification Documents
ID Card: Resident Registration Card or Driver’s License
Resident Registration Certificate: Displaying address changes for the past 5 years and including household members
Resident Registration Abstract: Including entire personal address change history (for single household head verification)
Family Relationship Certificate (Detailed): Mandatory regardless of marital status (to confirm spouse-separated households)
(For prospective household heads): Proof of scheduled marriage such as wedding invitations or wedding hall contracts
② Income and Employment Verification Documents
Earned income earners:
Certificate of Employment (stamped with company seal)
Earned Income Withholding Tax Receipt or Certificate of Income Amount for the past 2 years
Health Insurance Eligibility Confirmation
Business income earners / Freelancers:
Certificate of Business Registration
Comprehensive Income Tax Certificate of Income Amount for the past 2 years
(If needed) Certificate of Commission or Withholding Tax Receipt for Resident Business Income
③ Target Housing and Contract-Related Documents
Original Lease Agreement: Must be stamped with a fixed date (bring both existing contract and renewal contract)
Lease Deposit Down Payment Receipt: (Receipt showing payment of at least 5% of the increased deposit when renewing with an increased deposit)
Certified Real Estate Register (Certificate of All Registered Matters) of Leased Housing: 1 copy each for land and building (must be issued for submission, not for viewing)
Building Ledger: To check for violating structures
④ Existing Loan Verification Documents (Core Refinancing Documents)
Financial Transaction Confirmation: Issued at the branch of the existing lending bank (must clearly state loan type, initial loan date, loan balance, and maturity date)
Debt Certificate (Loan Balance Certificate): To confirm principal balance to be repaid as of the current date
Copy of Existing Jeonse Loan Agreement: (May be requested additionally depending on the bank)
Practical Visit Tip
Visit Timing and Bank Counter Selection
Application timing: Document submission at the bank counter should be completed at least 3 to 4 weeks prior to the lease contract expiration or target refinancing date. HUG pre-asset review and guarantee approval alone take 10 to 15 business days.
Branch selection: It is advisable to select a large branch with abundant fund loan handling experience and helpful staff among general retail branches. Because refinancing involves cumbersome administrative procedures, some branch counters may be passive; inquiring by phone in advance about whether the branch handles fund refinancing before visiting will make things much smoother.
Frequent Disqualification Reasons & Practical Tips During Refinancing
Even if applicants meet the basic eligibility for a Beotimmok refinancing loan, quite a few receive disqualification determinations due to minor differences in guarantee institution regulations and bank administrative procedures. We have compiled the 4 most frequent reasons for rejection encountered on-site by applicants, along with practical tips to avoid them.
- Frequently Occurring Rejection and Disqualification Reasons
Issues with Guarantee Institution (HUG vs HF) Succession and Conversion Impossibility
Many cases are rejected because applicants apply without checking which institution’s guarantee certificate (Housing and Urban Guarantee Corporation HUG vs Korea Housing Finance Corporation HF) their existing commercial bank jeonse loan was issued under.
If a pledge or bond assignment notice is attached to the existing loan, depending on the handling bank or branch, they may refuse conversion to a different guarantee institution’s certificate or require refinancing only through the identical guarantee institution.
Attempting to Apply for More Than the Existing Loan Balance
Even if the Beotimmok deposit limit (70–80% of the deposit) allows a higher headroom, applying for a refinancing amount greater than the existing loan principal will result in disqualification.
Loans for refinancing purposes are strictly limited to the balance indicated on the financial transaction confirmation from the existing lending bank.
Omitting the ‘5% Down Payment’ Receipt on Deposit-Increased Renewals
When refinancing to include an increased deposit during lease renewal, applications are frequently rejected because applicants fail to prove down payment payment (usually 5% or more of the deposit) with a wire receipt or receipt showing funds transferred to the landlord’s account.
Midway Asset Changes (Post-Asset Review Disqualification)
Even if you passed the Gigeum-e-Deundeun preliminary review, if vehicle purchases, deposits from stock liquidations, or debt fluctuations are reflected within 1 to 2 months before or after loan execution and push your final net asset value over the threshold (around 345 million KRW), penalty interest rates will be imposed or notice of loan recall will be issued.
Property Rights Changes and Building Ledger Disqualifications
Even if the home was free of issues at the time of the initial contract, if the landlord registers additional collateral mortgages (collateralized loans), provisional seizures, or if illegal extensions cause a ‘violating structure’ notation on the building ledger during residency, fund guarantee certificate issuance will be rejected outright.
- Practical Preparation Tips to Boost Approval Rates
Identify the Guarantee Institution Type of the Existing Loan First
Check in advance through the existing bank’s app or customer service whether your loan is backed by HUG (Safe Jeonse), HF (Housing Finance Corporation), or SGI (Seoul Guarantee Insurance). Applying for Beotimmok through the identical guarantee institution line greatly minimizes variables in document processing and pledge cancellation procedures.
Check the Wording on the ‘Financial Transaction Confirmation’ Before Visiting the Bank
You must check whether the loan type on the issued financial transaction confirmation explicitly states ‘Housing Jeonse Loan’ and whether at least 3 months have elapsed since loan disbursement. If personal credit loan characteristics are mixed in, refinancing is impossible.
Mandatory Prepayment Penalty Profit/Loss Calculation
Since this involves terminating the existing bank loan before its 3-year maturity, you must calculate the prepayment penalty payable to the existing bank (around 0.5 to 1.5% depending on remaining loan days). It is safe to proceed only after comparing and ensuring that the annual interest saved by switching to Beotimmok is significantly greater than the prepayment penalty.
Request Advance Cooperation from the Landlord
During the refinancing process, the bank requires an on-site property inspection, phone call verification of lease facts, or receipt of notice of pledge establishment. If the landlord avoids contact or refuses receipt, loan disbursement may be canceled on the day of execution; thus, it is best to seek understanding regarding the fund refinancing procedure in advance when negotiating contract renewal.
Want me to write the final Epilogue section comparing monthly interest savings and summarizing the guide?
Yes
Korean version: 한국어로 읽기