Why Should You Sign Up for Youth Asset Formation Support Savings Accounts? (Introduction Purpose)
One of the biggest concerns for early-career workers or young adults preparing for independence is, “How can I efficiently build seed money?” Nowadays, with rising prices and unstable interest rates, growing assets solely through earned income is a daunting task.
This is why you must pay attention to the ‘Youth Savings Account and Asset Formation Support System,’ launched jointly by the government, local authorities, and commercial banks to help young people achieve self-reliance. We break down the purpose of the system’s introduction and the core benefits provided by youth savings accounts into 3 key points.
- The State’s ‘Matching Support Fund’ Added to Earned Income (Accelerating Asset Growth)
While standard commercial installment savings consist only of the principal you deposit and a small amount of interest provided by the bank, government-supported youth savings accounts feature a completely different structure.
Support fund matching structure: When the youth saves a certain amount each month (e.g., 100,000 KRW to 500,000 KRW), the government or local authorities additionally accumulate a support fund (government support matching fund) based on income criteria and product types.
Thanks to this, the amount received upon maturity combines your contributed principal with beyond-imagination support funds and interest, allowing you to achieve the goal of building seed money—which would be difficult to reach alone—much faster.
- A Reliable Economic Safety Net for Early-Career, Low-Income, and Middle-Class Youth
Asset formation means more than simply saving money; it is the foundational stamina to relieve future anxiety and prepare for a social leap.
It presents a foundation for economic self-reliance to young people taking their first steps into society after college graduation or those facing major turning points in life such as housing, marriage, and starting a business.
Providing fair opportunities to the youth demographic—whose foundation for asset formation could otherwise be shaken by income disparities—and establishing a social safety net by mitigating the wealth gap are the core national purposes behind the introduction of this system.
- Formation of Savings Habits and Enhancement of Financial Literacy
Beyond simply receiving financial support, developing proper financial habits during youth has a major impact on lifelong asset management.
A savings structure requiring consistent monthly contributions builds systematic spending habits and savings routines into your body.
Through the process of comparing various youth savings account products and weighing interest rates, preferential benefits, and tax benefits, it serves as an opportunity to build financial knowledge and grow as a smart economic agent.
Tip. Core of Utilizing the System
Unlike regular products, youth savings accounts have very strict qualification requirements such as enrollment age, personal income, and household income, and duplicate enrollment between products is often restricted. Choosing the most advantageous product for your employment type and income level and plotting a strategy in advance is the first step toward successful seed money accumulation.
[AI Image Generation Prompt Guide for Insertion (16:9)]
Style: Warm, bright, and modern financial lifestyle photography, clean indoor daylight, text-free.
Scene Description: A young professional or student smiling brightly while managing finances on a clean modern laptop and a smartphone next to a neat piggy bank on a bright wooden desk, symbolizing financial growth and savings. Wide 16:9 aspect ratio, high resolution, realistic textures, absolutely no text, no watermark, no logos.
Negative Prompt: Hangul text, cluttered desk, dark shadows, low resolution, messy dust, cartoon style.
Comparison of Major Youth Savings Account Types and Eligibility Criteria
There are several representative youth savings account systems operated by the government, local authorities, and the financial sector to help young people build assets. However, because support purposes and characteristics differ by product, you must accurately compare and choose which product perfectly fits your income and employment type.
We clearly compare the characteristics and eligibility requirements of the 3 most widely used and solid youth savings accounts.
- Youth Tomorrow Savings Account (Matching Support Fund for Low-Income and Working Youth)
This is a representative asset formation savings account where the state adds a reliable monthly support fund for young people who save while engaging in economic activities.
Eligibility and Income Criteria:
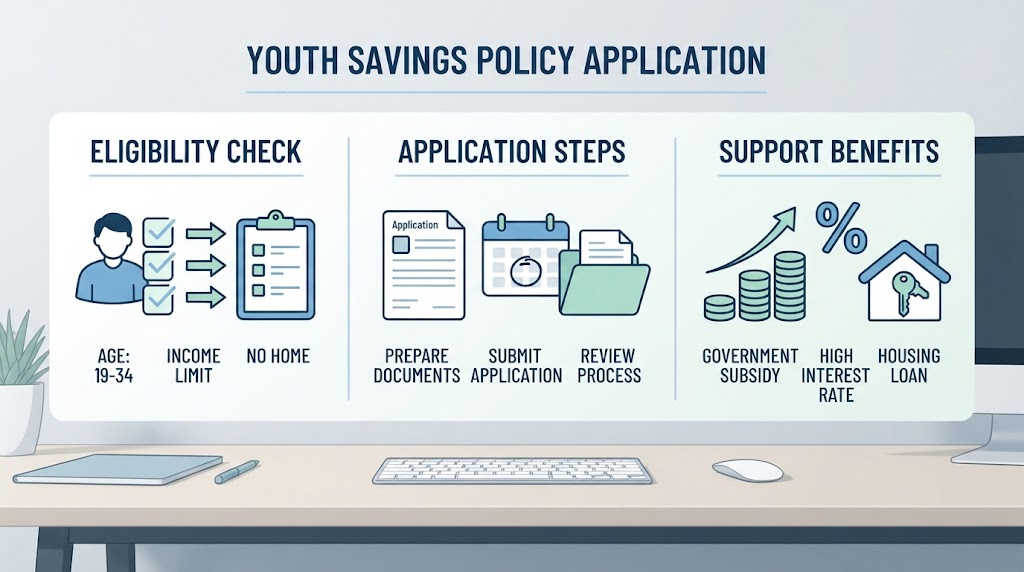
Age: Between 19 and 34 years of age as of the application enrollment date (However, recipients of basic livelihood security and near-poverty brackets are allowed up to 39 years of age)
Earned/Business Income: Youths currently engaged in employment or business whose household median income falls between 50% and 100% based on general household standards (※ Recipients and near-poverty brackets with 50% or less of median income are also eligible)
Support Benefits: When you save 100,000 KRW or more (up to 500,000 KRW) per month, the government additionally accumulates a support fund (government support matching fund) of 100,000 KRW to 300,000 KRW monthly based on income criteria, allowing you to handsomely receive principal and interest upon the 3-year maturity.
- Youth Tomorrow Chaeum Deduction / Employment Promotion Youth Support Product (For Small and Medium-Sized Enterprise Employees)
This is a system that simultaneously supports long-term retention and seed money accumulation for young people newly employed by small and medium-sized enterprises (SMEs).
Eligibility and Income Criteria:
Age: Youths aged 15 to 34 (Upper age limit can be extended based on military service period)
Employment Condition: Employment insurance subscription history and regular employment status at a small and medium-sized enterprise (※ Detailed operating guidelines and seasonal enrollment conditions may vary slightly depending on company size, industry, or corporate contribution burdens.)
Support Benefits: Structured so that corporate contributions and government support funds are accumulated together with the youth’s personal contributions. When working continuously for a certain period (usually 2 or 3 years) or longer, you can get your hands on a large lump sum of funds that would be difficult to accumulate alone, making it exceptional for preventing early-career turnover and laying a foundation.
- Youth Housing Dream Subscription Savings Account (Combined Housing Independence, Subscription, and Preferential Interest Rates)
Going beyond simple savings, this is an all-around subscription savings account that simultaneously captures the dream of homeownership and groundbreaking interest rate benefits.
Eligibility and Income Criteria:
Age: Homeless individuals aged 19 to 34
Income Criteria: Earned, business, or other income earners with an annual income of 50 million KRW or less (Income criteria have been drastically relaxed compared to the existing youth-preferred housing subscription comprehensive savings account.)
Support Benefits: Not only do you receive preferential interest rates up to around 4.5% per annum on your contribution amount, but if you win a housing subscription using this account, you can advantageously secure housing purchase funds through linked low-interest loans (Youth Housing Dream Loan), making it essential for youths dreaming of housing stability.
Tip. Precautions for Duplicate Enrollment
Among youth savings accounts, cash-matching products funded directly by the government (such as the Youth Tomorrow Savings Account) often restrict duplicate enrollment with similar local government asset formation projects. On the other hand, housing subscription-related products have different characteristics, so if you meet the enrollment conditions, you can often run them parallel to other savings accounts, so be sure to check carefully before enrolling.
[AI Image Generation Prompt Guide for Insertion (16:9)]
Style: Clean, professional, and modern financial lifestyle photography, bright indoor daylight, text-free.
Scene Description: A clean modern comparison concept featuring three different colored savings passbooks neatly arranged on a bright wooden desk next to a sleek laptop and a calculator, symbolizing financial product selection. Wide 16:9 aspect ratio, high resolution, realistic textures, absolutely no text, no watermark, no logos.
Negative Prompt: Hangul text, cluttered desk, dark shadows, low quality, cartoon style.
Comparison of Preferential Benefits, Interest Rates, and Support Fund Conditions by Bank
Once you have met the government-supported funds or subscription eligibility, the next important question is through which commercial bank you should open an account and secure additional preferential benefits. Beyond the base interest rates or matching support funds supported by the government, there are subtle differences in preferential interest rate conditions and ancillary services offered by each financial institution (commercial bank).
We outline the comparison points for preferential benefits and interest rate/support fund conditions by major commercial bank that you should know when signing up for youth savings accounts (especially the Youth Housing Dream Subscription Savings Account and bank-linked installment savings products, etc.).
- Common Base Conditions and Differentiating Points by Major Commercial Bank
Major domestic commercial banks such as Kookmin, Shinhan, Woori, NH Nonghyup, and Hana equally provide the base product interest rate benefits (e.g., maximum 4.5% per annum for the Youth Housing Dream Subscription Savings Account) as government-designated official handling institutions. However, it is advantageous to consider the following factors when choosing a bank.
Primary bank connectivity: Linking with your salary account, frequently used check card, or mobile app (App) primary transaction performance makes it easier to secure additional preferential interest rates.
Non-face-to-face subscription events: There are differences in mobile coupons, financial fee waivers, or additional cash-back events provided when opening a youth savings account non-face-to-face through each bank’s smartphone app (e.g., KB Star Banking, Shinhan SOL, Woori WON Banking, etc.).
- Comparison of ‘Preferential Interest Rate Conditions’ to Check When Choosing a Bank
For some bank-linked installment savings or subscription products among youth savings accounts, the final interest rate is maximized when preferential interest rate conditions are met.
Salary transfer and automatic transfer performance: Preferential interest rates of 0.2%p to 0.5%p are provided if salary above a certain amount is deposited into the bank account every month or if the number of automatic transfer contributions to the account meets a certain number of times or more.
Marketing consent and first-time subscriber benefits: Promotions providing extra interest rates are regularly operated for customers who are making their first lifetime housing subscription or whose account is a first-time account with that bank (new customers), so even a bank you don’t normally trade with might be advantageous to open an account with if the conditions are better.
Linked card usage performance: For products requiring credit or check card performance, you must check whether it matches your usual consumption pattern. (※ Caution is required as trying too hard to meet performance requirements may instead increase consumption.)
- Tips for Maximizing Government Support Funds and Interest Income Tax Exemption Benefits
While interest rate differences among banks are important, the core of youth savings account asset management lies in ‘full receipt of tax benefits and government support funds.’
Application of interest income tax exemption: Qualified youth savings accounts (such as accounts converted from youth-preferred housing subscription comprehensive savings or the Youth Housing Dream Subscription Savings Account) are exempted (tax-exempt) from income tax excluding the rural development special tax within a certain limit (usually 5 million KRW in interest income, 6 million KRW annual contribution principal limit, etc.) upon maturity cancellation. You must submit all evidentiary documents for tax exemption targets when signing up at the bank to enjoy the benefits.
Synergy with government matching funds: Since the monthly definitive government support matching amount coming from products like the Youth Tomorrow Savings Account is much larger than a bank interest rate being 0.1%p higher, it is wiser to select your main product focusing on ‘government support eligibility that you can secure with certainty’ rather than the bank brand itself.
Tip. Pre-Checklist Before Visiting the Bank
Rather than visiting a bank branch blindly, check the ‘Non-face-to-face subscription conditions for youth-preferred products’ in advance through smartphone financial platforms or each bank’s customer center app. You are much more likely to receive preferential interest rate coupons or additional events when signing up on mobile, and you can process it conveniently without waiting time.
[AI Image Generation Prompt Guide for Insertion (16:9)]
Style: Clean, bright, and modern financial lifestyle photography, soft indoor daylight, text-free.
Scene Description: A clean modern smartphone showing a digital banking app screen with interest rate comparisons, resting on a bright wooden desk next to a modern credit card and a notepad. Wide 16:9 aspect ratio, high resolution, realistic textures, absolutely no text, no watermark, no logos.
Negative Prompt: Hangul text, cluttered desk, dark shadows, low quality, cartoon style.
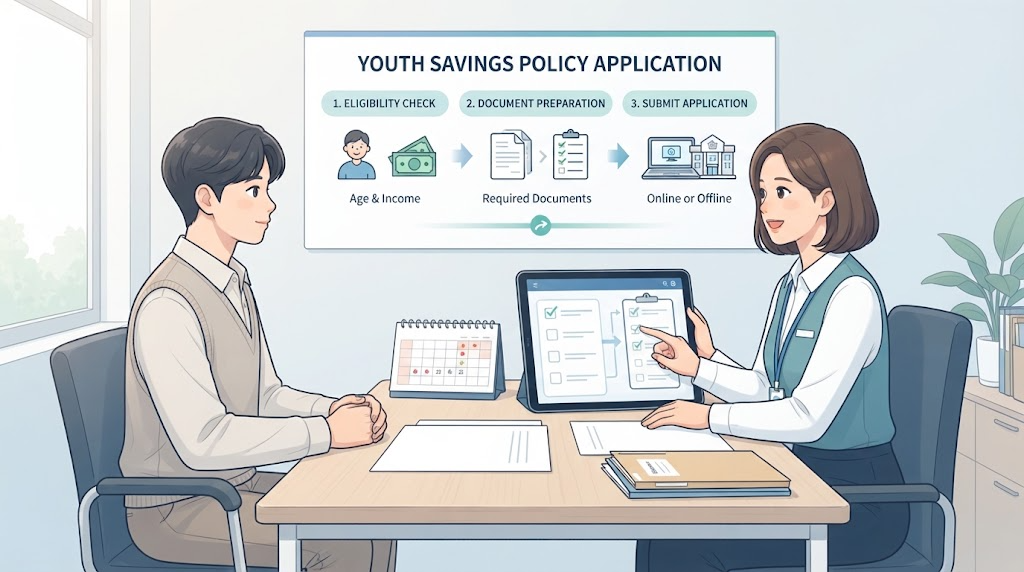
Application Methods and Essential Required Documents
Once you have understood the attractive benefits and bank-specific conditions of youth savings accounts (such as the Youth Tomorrow Savings Account, Youth Housing Dream Subscription Savings Account, etc.), it is time to take concrete execution steps on how to apply and what documents to prepare to actually secure the benefits.
Although offline and online application methods vary slightly depending on the product type, we meticulously organize the essential required documents and application procedures that are commonly easy to miss.
- Application Methods (Online vs. Offline)
Youth savings accounts can be conveniently applied for through government welfare portals or commercial bank apps.
Online application (Most recommended method):
Welfare support type products (e.g., Youth Tomorrow Savings Account, etc.): After logging in with a joint certificate or similar on South Korea’s representative welfare portal ‘Bokjiro (bokjiro.go.kr)’ official website or mobile app, you can easily apply through the welfare service application menu.
Financial product type (e.g., Youth Housing Dream Subscription Savings Account, etc.): Non-face-to-face subscription and application are possible without visiting a branch through the smartphone official financial app (App) of each commercial bank (Kookmin, Shinhan, Woori, NH Nonghyup, Hana, etc.).
Offline application (Visiting a bank branch or community center):
If internet authentication or document submission is cumbersome, you can directly visit and apply at the eup, myeon, or dong administrative welfare center (community center) with jurisdiction over your residence for government-supported types, and you can directly visit a nearby handling commercial bank branch counter to receive guidance and proceed for financial products like subscriptions.
- Essential Required Documents Checklist
The most important thing when applying for a youth savings account is objective data proving ‘personal and household income requirements’ and ’employment/business verification.’ To pass all at once without rejection, you must prepare the following documents in advance.
① ID card: Resident registration card or driver’s license for identity verification.
② Income amount certificate or income confirmation certificate: Earned (or business) income verification documents for the most recent year issued by the National Tax Service Hometax or Government24 (※ Core material for checking whether income criteria are met.)
③ Certificate of employment or 4 major public insurances subscription details confirmation: A document to prove that you are currently engaged in economic activity.
④ Resident registration copy and family relationship certificate: Required to check the number of household members and verify age requirements. (Consent forms for household income and property investigations may be required depending on circumstances.)
⑤ Tax exemption application documents (When signing up for bank products): Additional forms required by the bank, such as the ‘Income Confirmation Certificate (for Youth Preferential Savings)’ to receive interest income tax exemption benefits.
Tip. Final Check Tip Before Application
For government-supported products (e.g., Youth Tomorrow Savings Account), specific application periods during the year (usually concentrated recruitment periods 1 to 2 times a year) are often set by local government, so it is essential to check Bokjiro announcements frequently so as not to miss the period. On the other hand, financial products like the Youth Housing Dream Subscription Savings Account are available for year-round enrollment.
[AI Image Generation Prompt Guide for Insertion (16:9)]
Style: Clean, professional editorial and administrative concept photography, bright natural daylight, text-free.
Scene Description: A neatly organized wooden desk displaying an official welfare application form, a smartphone open to a banking app, and a sleek blue pen, symbolizing a successful financial application process. Wide 16:9 aspect ratio, high resolution, realistic textures, absolutely no text, no watermark, no logos.
Negative Prompt: Hangul text, messy desk, dark shadows, low quality, blurred documents, cartoon style.
Tips for Maintaining and Utilizing Your Savings for Successful Seed Money Accumulation
Even if you pass the demanding enrollment conditions and manage to open a youth savings account, fully maintaining your eligibility until maturity and maximizing benefits is another challenge. A minor carelessness leading to premature cancellation or missing out on support funds can turn your efforts up to that point into bubbles.
We outline 3 core maintenance and utilization tips that you must remember to successfully get your hands on seed money through a youth savings account and cleverly utilize it as a future asset.
- Setting Up an ‘Automatic Transfer Routine’ to Prevent Premature Cancellation and Separating Emergency Savings Accounts
Most youth savings accounts set ‘consistent contributions over a certain period (2 to 3 years or more)’ as the core condition for maturity payout.
Mandatory automatic transfer: Setting up an automatic transfer for your monthly savings amount for the very next day after your salary comes in is the safest way to build a system where savings happen before money even has a chance to linger in your account.
Separate operation of emergency fund account: As life goes on, situations inevitably arise where cash is suddenly needed. To prevent breaking your youth savings account (premature cancellation), it is wise to gather a separate emergency fund equivalent to at least 3 months’ worth of living expenses through a separate ‘CMA or parking account.’
- Beware of Employment Status Changes and Omissions in Income Reporting (Guarding Recipient Eligibility)
Changes in employment status such as job changes, resignations, or leaves of absence may occur while utilizing government-supported youth savings accounts (e.g., Youth Tomorrow Savings Account, etc.).
Immediate reporting and coping: Even if you change jobs, eligibility is often maintained if you continuously maintain employment or get re-employed within a certain grace period. However, failing to report changes to the competent authorities on time or omitting them can result in disqualification or support fund recovery measures, so you must carefully check the regulations.
Monitoring income criteria changes: It is advisable to steadily monitor your annual salary and income flow so that you do not stray out of the median income range during the annual income and property investigation process.
- Strategic Utilization of Seed Money After Maturity Receipt (Seed Money Snowball)
The moment when a reliable lump sum combining principal, government support funds, and interest is released upon maturity cancellation after years of patience is where the real start begins.
Linking to housing stability and asset growth: If the funds were prepared through the Youth Housing Dream Subscription Savings Account or similar, you should utilize them to drastically lower housing costs by linking directly to low-interest loans (Youth Housing Dream Loan) after winning a housing subscription for homeownership.
Reinvestment portfolio construction: Rather than leaving it as plain cash, you need a strategy to roll the snowball (compound effect) of your assets by distributing the matured seed money into stable deposits and installment savings, blue-chip asset investments, or additional self-development funds.
Tip. Final Check Right Before Maturity
Although guide text messages arrive from banks or local governments as the maturity date approaches, there are times when missed document submission deadlines delay interest income tax exemption benefits or maturity support fund claims. Checking in advance what documents are required (such as final income verification) starting 1 to 2 months before maturity is the secret to placing a perfect period at the end.
[AI Image Generation Prompt Guide for Insertion (16:9)]
Style: Warm, inspiring, and clean financial lifestyle photography, bright morning sunlight, text-free.
Scene Description: A clean and modern wooden desk featuring a blooming small green plant sprouting from a neat glass jar filled with coins, symbolizing steady financial growth, wealth accumulation, and successful future planning. Wide 16:9 aspect ratio, high resolution, absolutely no text, no watermark, no logos.
Negative Prompt: Hangul text, cluttered desk, dark shadows, low resolution, messy dust, cartoon style.
[Overall HTML Code Structure and English SEO Metadata Organization for This Posting]
Do you need the entire English translation work or additionally required article outlines for this youth savings account comparison posting?
Yes
Korean version: 한국어로 읽기