Introduction: Why Should You Check the Loan Limit Suited to Your Jeonse Deposit in Advance?
When you decide to be independent and go around looking for a jeonse home that catches your eye, you face a huge reality before stamping your seal on the contract. That is the question, “Can I really afford the deposit for the home I want with the lump sum I have and a loan?”
Many young adults hurry their contracts or look for a home with the vague thought that “things will somehow work out if I go to the bank.” However, there are countless cases where they proceeded with a contract without properly grasping loan limits and conditions, only to lose their down payment due to a lower-than-expected loan limit or break into a sweat trying to urgently secure insufficient funds.
“The jeonse deposit is 100 million won, so up to how much can I get for a loan?”
“What are the differences in loan limit criteria between the capital area and regional areas?”
The ‘Youth Beotimuk Jeonse Fund Loan,’ a representative youth housing financial product supported by the state, boasts unconventional ultra-low interest rates, but the limit you can borrow is thoroughly determined depending on the deposit size and personal conditions. Therefore, calculating the exact loan limit in advance according to your jeonse deposit size is an essential first stepping stone for successful independent living.
Then just how much funding will the Youth Beotimuk Loan reliably support by deposit amount? From now on, let’s easily break down everything about loan limits according to the jeonse deposit size!
What is the Youth Beotimuk Jeonse Fund Loan? Core Summary and Support Targets
“It’s so scary and daunting to find a studio apartment because of soaring jeonse prices, but are there reliable loan products that early-career workers or college students can use without burden?”
For young adults taking their first steps into society or preparing for independence, jeonse deposits impose a heavy burden under the name of lump-sum money. General jeonse loans from commercial banks are often out of reach for youth due to high interest rates and strict income verification requirements. To ease these young adults’ housing difficulties, the representative public fund product supported by the government is the ‘Youth Beotimuk Jeonse Fund Loan.’ We clearly and simply organize the core content of what kind of product it is and who can receive support.
- What is the Youth Beotimuk Jeonse Fund Loan?
The Youth Beotimuk Jeonse Fund Loan is a state-supported exclusive financial product that lends jeonse deposits at low interest rates with resources borne by the Housing and Urban Fund for youth in desperate need of housing stability, such as early-career workers, college students, and job seekers.
It provides incomparable unconventional interest rate benefits and generous limits compared to general loans, serving as a reliable pillar that helps youth starting independent living escape economic pressure and concentrate on their studies or livelihoods.
- Who Can Apply? Key Support Target Requirements
To enjoy this benefit, you must fully satisfy several basic qualification requirements established by the state.
Age Criteria: According to the youth criteria set by the Housing and Urban Fund, it generally targets youth aged 19 to 34. (For those who have completed military service obligations, the age limit may be applied upward in proportion to the service period.)
Homeless Household Head Criteria: Not only the youth applicant applying for the loan, but all household members must be ‘homeless people’ who do not own a home. (This includes cases where someone is scheduled to become a single-person household head immediately after the loan is executed as a prospective household head.)
Income and Asset Criteria:
For single-person households consisting solely of the youth, the annual income of the previous year must be below a certain standard (e.g., generally 50 million won or less).
Priority support is given to working-class youth classes who do not possess excessively excessive assets (below fund-standard asset values such as real estate, automobiles, etc.).
💡 Core Summary
Although the qualification requirements may seem somewhat strict, homeless youth can enjoy tremendous interest rate benefits incomparable to commercial bank products. It is important to check in advance whether your annual income and assets meet the criteria.
Then, how much will the loan limit that you can actually borrow be calculated specifically according to your jeonse deposit amount? We will examine it in detail in the next section!
Comprehensive Guide to Loan Limits by Deposit Size: How Much Can I Borrow to Secure a Home?
“My jeonse deposit is 100 million won, so how much can I get for a loan at most? What if I can’t fully cover the deposit of the home I want?”
When looking into the Youth Beotimuk Loan, the most curious yet important part is the ‘loan limit.’ Since it is a government-supported product, it does not unconditionally lend as much as you want; the limit is thoroughly calculated based on the size of the jeonse deposit and the location of the housing (capital area vs. regional areas). We will thoroughly examine in detail how reliably you can receive fund support according to your jeonse deposit size.
- Examining Loan Limit Criteria by Jeonse Deposit Size
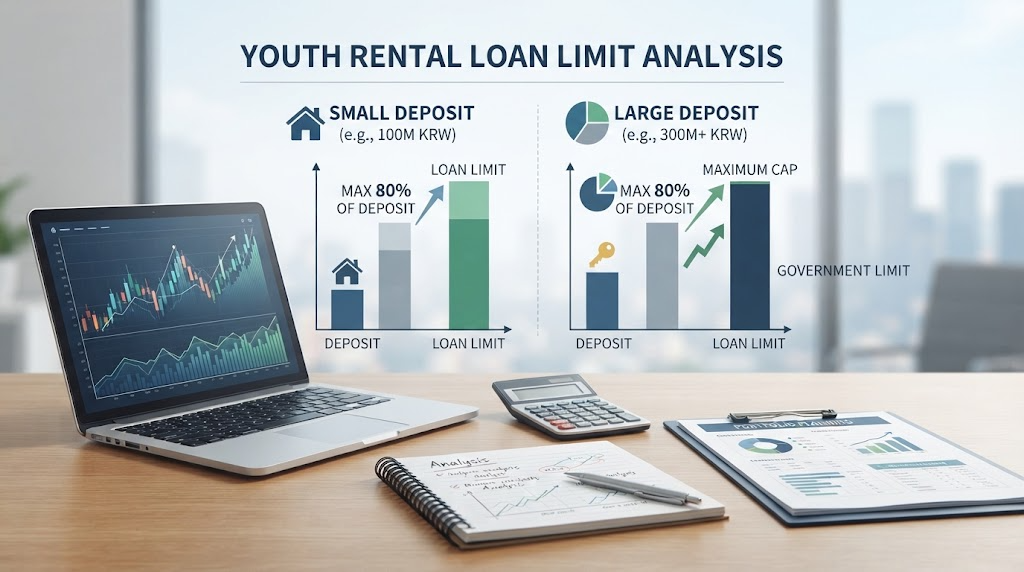
The Youth Beotimuk Jeonse Fund Loan basically sets a certain ratio of the lease deposit (generally within 80%) as the limit, but maximum upper limits are determined for each product.
Small-Scale Jeonse Homes (Studio apartments, officetels, etc., with a deposit of 100 million won or less): For small-scale housing that requires relatively less funds, you can stably procure the necessary funds within a maximum of 80% of the deposit.
Medium-Scale Jeonse Homes (Deposits exceeding 100 million won up to 200 million won): As the deposit size increases, you can generously receive up to the maximum upper limit of the youth-exclusive Beotimuk loan, which can sufficiently cover most officetels or villa jeonse properties in Seoul and the metropolitan area.
Maximum Loan Limit Upper Bound: The general maximum limit of the Youth Beotimuk Jeonse Fund Loan is differentially applied up to a maximum of 200 million won or less based on the capital area (Seoul, Gyeonggi, Incheon) and up to 160 million won or less based on regional areas (non-capital area).
- Perfect Comparison of Regional Limit Differences Between Capital Area and Regional Areas
Reflecting the housing price market conditions and price levels of the residing region, differences are placed on loan limits and target housing deposit requirements by region.
Capital Area: Targets housing with a total housing deposit of 300 million won or less, supporting loans up to 200 million won to relatively alleviate high deposit burdens.
Regional Areas (Non-Capital Area): Targets housing with a total housing deposit of 200 million won or less, allowing loans up to 160 million won to utilize funds with leeway in accordance with regional market conditions.
💡 Deposit & Limit Core Point
No matter how high the maximum limit is, you cannot borrow exceeding 80% of the jeonse deposit you intend to contract. For example, if the deposit is 100 million won, the maximum borrowable amount is 80 million won (80%), so the remaining 20% (20 million won) must be securely prepared with your own funds (including the down payment) to be safe.
Then, let’s check specifically in the next section how much the ultra-low interest rate benefits and additional interest rate reduction conditions actually applied when using this reliable loan are!
Interest Rate Benefits and Additional Preferential Interest Rate Application Conditions
The most decisive reason why the Youth Beotimuk Jeonse Fund Loan is counted among South Korean youth as the ‘best housing welfare product’ lies in its unimaginable, unconventional ‘ultra-low interest rate’ benefits.
Nowadays, when general jeonse loan interest rates at commercial banks exceed 4% to 6%, government-supported fund loans drastically lower the interest burden for young adults. We explain in detail, ranging from basic interest rate benefits to additional preferential interest rate application conditions you will regret missing.
- Unconventional Basic Interest Rates That Sharply Lower Wallet Burdens
The basic interest rate of the Youth Beotimuk Loan is applied differentially according to the youth’s income level and jeonse deposit bracket, but it is provided at an astonishingly low interest rate ranging generally from 1.5% to 2.1% per year.
Differential Application by Income Bracket: Lower interest rates are applied as annual income is lower (e.g., 20 million won or less), and it is slightly adjusted upward step-by-step as income increases, yet it is incomparably cheap compared to commercial interest rates.
Resolution of Interest Bomb Worries: Because the interest burden going out as fixed monthly expenses is minimized, it serves as a reliable foundation allowing early-career workers and college students to escape economic pressure and concentrate fully on their studies, livelihoods, and preparation for independence.
- This is Not the End! Additional Preferential Interest Rate Application Conditions and Tips
Although the basic interest rate is sufficiently cheap, additional preferential benefits exist where you can lower the interest rate further through overlapping applications if specific conditions are met.
Housing Stability Monthly Rent and Youth Preference: Additional preferential interest rates can be applied depending on the characteristics of the youth household or policy targets.
Utilization of Electronic Contract Type 3: When concluding an electronic contract (lease contract) through the Ministry of Land, Infrastructure and Transport’s Real Estate Transaction Management System, you can additionally receive a 0.1%p per year interest rate reduction benefit.
Other Preferential Conditions: If you meet additional requirements designated by the Housing and Urban Fund (e.g., subscription period for youth preferential housing subscription savings accounts, etc.), you can maximize benefits down to the lowest interest rate floor through duplicate applications.
💡 Interest Rate Benefit Core Point
An interest rate in the 1% range is so powerful that you barely feel the interest burden, but because the final applied interest rate varies depending on your income level and whether you meet preferential conditions, it is best to carefully check applicable preferential benefits when applying at the bank.
Then, to actually utilize this attractive loan product, what procedures should you use to apply and what should you prepare before visiting the bank? Let’s examine specifically in the next section!
Practical Application Method and Essential Preparation Checklist Before Visiting the Bank
“I’ve checked all the conditions, limits, and interest rate benefits of the Youth Beotimuk Loan, but where on earth and how should I start applying? And what kind of documents do I need to prepare in advance before going to the bank branch?”
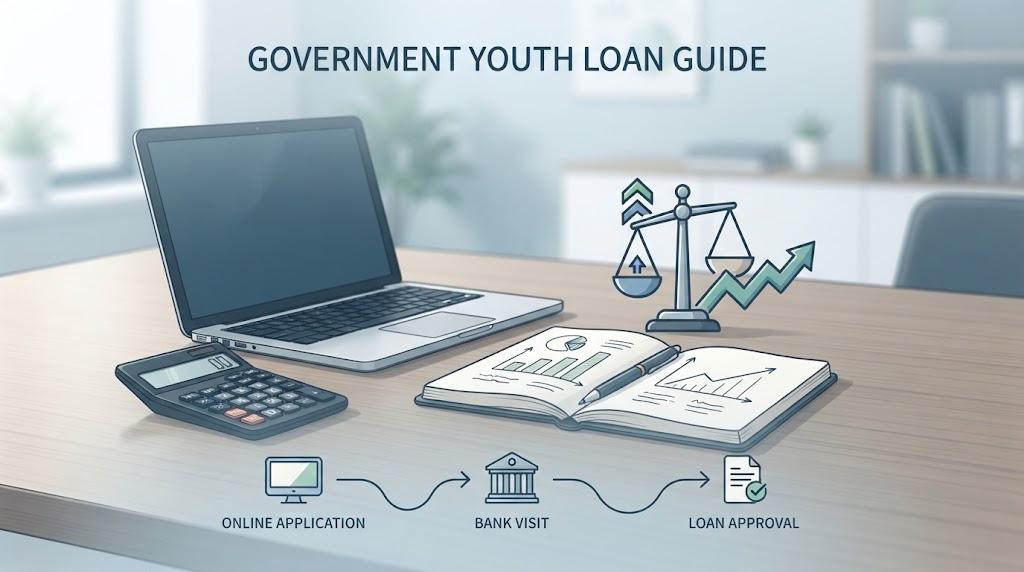
Government-supported jeonse loans are not executed immediately just by blindly visiting a bank branch. Since you must go through online preliminary application and offline bank visit stages, we thoroughly organize the step-by-step application method and essential required document checklist to help you get approval in one go without wandering around.
- 2-Step Process from Online Preregistration to Bank Visit
Step 1 (Online Preregistration and Qualification Check):
Log in to the Housing and Urban Fund portal or the Fund e-DeunDeun (enhuf.molit.go.kr) website using a joint certificate. Select the Youth Beotimuk Jeonse Fund Loan product and enter basic information to proceed with a preliminary qualification screening (eligibility status). You must go through this process to make future bank screenings much faster and smoother.
Step 2 (Visit to Entrusted Bank and Final Document Submission):
If you received an eligible judgment or completed a preliminary reservation in the Fund e-DeunDeun screening, visit a branch of the entrusted fund-handling bank, such as Woori Bank, KB Kookmin Bank, Shinhan Bank, NH Nonghyup, or IBK Industrial Bank, to submit final documents and execute the loan agreement.
- Essential Required Document Checklist to Definitely Pack Before Visiting the Bank
These are the core documents that determine the success or failure of the loan screening. Make sure to prepare them completely based on the latest standards issued after the announcement date or contract date.
① ID Card and Resident Registration Copy and Extract:
Submit an ID card for identity verification, along with a resident registration copy and extract that include all address change histories. (For verifying single-household head requirements and homelessness)
② Family Relations Certificate (Detailed):
Must be issued as a detailed certificate to accurately check marital status, relationship with parents, household member composition, etc.
③ Employment and Income Verification Documents:
Office workers: Certificate of employment, copy of business registration certificate (if applicable), income amount certificate or withholding receipt for earned income, etc.
College students / Job seekers: Alternative income verification documents such as a certificate of enrollment or certificate of leave of absence
④ Housing-Related Documents (Lease Agreement and Receipt):
Original lease agreement stamped with a fixed date (must be accompanied by a deposit receipt proving that 5% or more of the jeonse deposit has already been paid as a down payment!)
Certified copy of the building registry (certified copy of the register) and building ledger of the target property.
💡 Practical Tips Before Visiting the Bank
It is safest to request a preliminary screening in advance from a certified real estate agent or a bank teller before signing the contract to see if the jeonse home you intend to contract is a safe property meeting loan conditions (without risk factors such as illegal buildings, excessive collateralized mortgages, or provisional seizures).
Can you rest easy once you have prepared all documents perfectly and completed the bank application? Wait a moment! There are critical precautions remaining that you must never miss during the loan screening process. Let’s check them in the next section!
Practical Tips & Precautions for Passing the Loan Screening
“If you met all the qualification requirements and prepared your essential documents perfectly to submit to the bank, but were rejected in the final screening due to a minor rule or a contracting mistake, there would be nothing more heart-wrenching than this.”
Because the government-supported Youth Beotimuk Jeonse Fund Loan is operated with limited financial resources and has very strict screening criteria, small carelessness can lead to loan rejection or refusal to return the deposit. We deliver practical precautions and tips to pass the screening in one go without missing the precious opportunity you worked hard to seize!
- Must Secure Down Payment Receipt (5% or More) and Fixed Date
Down Payment 5% Payment Receipt is Mandatory: When applying for a loan at the bank, you must submit a down payment receipt proving that you have already paid at least 5% of the jeonse deposit to the landlord with your own funds. If exchanged in cash, you must write a receipt and get a stamp from a certified real estate agent, or thoroughly secure a remittance statement transferred to the landlord’s account.
Get a Fixed Date Immediately Upon Contracting: On the day you write the lease contract, you must immediately obtain a fixed date through a community center or internet registry office to safely protect your precious jeonse deposit from unexpected deposit accidents later on.
- Triple-Checking the Housing ‘Register’ and Illegal Building Status
Avoid houses with excessive mortgages (collateral): If the jeonse home you are trying to move into already has too many loans (collateralized mortgages) set up or is subject to seizure, provisional seizure, etc., government-supported loan approval may be rejected or it may be difficult to safely get your deposit back in the future.
Beware of illegal buildings and neighborhood living facilities: Neighborhood living facilities that are not for residential use according to the building ledger or illegally expanded unauthorized buildings are fundamentally excluded from the target of youth-exclusive fund loans. Before signing a contract, you must go through confirmation with a certified real estate agent as to “whether it is a safe property where Beotimuk Loan is available.”
- Adjusting the Timing of Moving and Resident Registration Transfer
Matching the loan execution date and resident registration transfer date: The loan amount is deposited directly into the landlord’s account and is usually executed on the day of the move. Since the resident registration transfer to the target housing must actually be completed on the day the loan is executed, you must closely coordinate the moving schedule and bank schedule.
💡 Summary of Final Screening Pass Tips
Be sure to secure a receipt for paying 5% or more of the jeonse deposit at the time of contract.
Carefully check whether it is a safe property through the registry copy and building ledger before contracting.
Get verified in advance through the handling bank (preliminary screening) prior to contracting as to whether loan execution is possible.
If you remember all these precautions and prepare thoroughly, you will be able to successfully grasp the reliable Beotimuk Loan that will blow away your worries about jeonse deposits all at once! Now, shall we check the warm concluding remarks that will gracefully wrap up the posting?
Conclusion: Successful Independence Together with Reliable Youth Beotimuk Loan
So far, we have explored together ranging from how to cleverly calculate loan limits by jeonse deposit size, to the core requirements and benefits of the Youth Beotimuk Jeonse Fund Loan, practical application procedures, and precautions.
Whenever dreaming of independence and looking into studio apartments, there must have been many of you who felt helpless in front of the walls of soaring jeonse prices and raising lump-sum money. However, the government-supported Youth Beotimuk Loan product introduced today will serve as your reliable wings, drastically lowering your financial burden and opening up a precious opportunity to secure a comfortable nest.
Shall we lightly retrace the core contents shared today once again?
First, accurately understand your jeonse deposit size and regional (capital area·regional area) loan limit criteria.
Second, carefully check the basic qualification requirements of the Youth Beotimuk Loan, such as annual income and homelessness status.
Third, after applying online for Fund e-DeunDeun in advance, visit the entrusted bank and perfectly equip essential documents such as the 5% down payment receipt.
Fourth, verify through a triple check whether it is a safe property by checking the registry copy and building ledger before contracting.
Financial housing support systems allow you to enjoy benefits as much as you know, and raise the quality of your life as much as you run around looking for them. Even if it feels a bit difficult and complicated, if you prepare step by step, you will be able to find a reliable answer that will refreshingly solve your light wallet and heavy housing worries.
We sincerely hope that this post served as a warm compass for your successful independent living and self-reliance. If you have any questions during the preparation process, please feel free to leave a comment anytime, and we sincerely cheer for everyone to smartly secure financial benefits and complete a comfortable and happy nest free of housing cost worries!
Korean version: 한국어로 읽기