Refinancing with a Beotimmok Jeonse Loan: 2 Distinct ‘Refinancing Purposes’
This is a draft of the body section written in a friendly yet informative tone so that Naver blog readers can understand it at a glance and stay engaged.
- Refinancing with a Beotimmok Jeonse Loan: 2 Distinct ‘Refinancing Purposes’
“I want to switch to a Beotimmok loan, can’t I just apply regardless?”
When looking at bank teller consultations or online reviews, surprisingly many people struggle right from the start of their consultation because they cannot clearly distinguish the nature of their refinancing.
The Beotimmok Jeonse Loan, a government-supported Housing and Urban Guarantee Fund loan, has completely different evaluation criteria and timing depending on the target property and the type of product you are currently using. To avoid disqualification, you must first accurately identify which of the following two categories applies to you.
① Commercial bank high-interest jeonse loan → Beotimmok refinancing (Interest diet type)
Target: Non-homeowners currently using general jeonse loans from commercial banks such as KB Kookmin, Shinhan, Woori, Hana, NH NongHyup, etc.
Core purpose: A type that drastically reduces monthly financial costs by converting commercial jeonse loan interest rates of 4–5% or higher into low-interest Fund loans around 1–2% per year.
💡 Key points you must check:
- Refinancing right after moving in (within 3 months): A method of converting a general bank jeonse loan into Beotimmok within 3 months of the balance payment date or move-in report date. (Mainly used by those who initially took out a general loan because they did not meet eligibility requirements at the start.)
- Refinancing upon lease agreement renewal: A method of switching at the time the existing lease contract expires and the deposit is increased or a renewed contract is signed. Drafting a renewed lease agreement and obtaining a fixed date (Hwakjeong-ilja) are mandatory.
- Limit calculation: In principle, refinancing is permitted only within the remaining balance of the existing commercial bank loan, so the goal of pulling out extra spare funds may be restricted.
② Existing Fund/General Beotimmok → Youth · Newlywed Beotimmok (Preferential condition type)
Target: Borrowers already using a Housing and Urban Guarantee Fund Beotimmok loan who newly meet marriage or age requirements.
Core purpose: A type that maximizes loan limits and preferential interest rates by switching to the ‘Youth-only’ or ‘Newlywed-only Beotimmok’, which offer stronger benefits than the general Beotimmok interest rate.
💡 Key points you must check:
- Life-cycle transition: Cases where someone was using a general Beotimmok and then got married to meet the ‘Newlywed-only’ requirements (relaxed income limits and lowest interest rate benefits), or switched to meet the requirements of a single householder aged 34 or younger.
- Accompanied by a property change (moving): Refinancing that simply changes conditions within the same house can be impossible or very difficult on the bank’s system. Typically, this proceeds in the form of moving to another house (changing the target property) after the contract expires and switching at the same time as signing a new contract.
- Restrictions on overlapping Fund loans: In principle, Housing and Urban Guarantee Fund loans are based on one account per person, so the repayment timing of the existing Fund loan and the disbursement timing of the new preferential loan must be precisely coordinated to avoid any gap.
📌 Core Summary
You can reduce wasted trips during bank counter consultations only if you clarify whether your current goal is “to cut high commercial bank interest” or “to level up to a more favorable Fund product by meeting Youth/Newlywed special requirements.”
If you want the next steps written, please click the buttons below:
Write Section 2: ‘Basic Loan Eligibility Requirements Checklist’
Write Section 3: ‘Top 4 Most Common Causes of Bank Evaluation Disqualification’
1st Hurdle: Basic Loan Eligibility Requirements Checklist
“My credit score is high and I have no delinquencies, so why did I fail the eligibility criteria?”
Unlike general commercial bank credit reviews, refinancing with a Beotimmok Jeonse Loan requires passing the strict public fund guidelines of the Housing and Urban Guarantee Fund first. Before submitting documents to a bank counter, a self-check is essential to ensure you haven’t missed any of the three core requirements (householder, income, and assets) listed below.
① Householder and Non-Homeownership Requirements
- Non-homeowner standard: As of the loan application date, all household members, including the householder, must be non-homeowners. Even if you do not own a home in your name, you will be disqualified if parents or a spouse listed on the same resident registration certificate own a home.
- Age of single householder:
- Single householder aged 25 or older: Eligible to apply for general Beotimmok
- Youth aged 19 to 34: Eligible to apply for Youth-only Beotimmok (including single householders or prospective householders)
- Notes for prospective householders: If you plan to get married or separate into an independent household after the loan is disbursed, you must submit a resident registration certificate showing the completion of move-in as a single householder to the bank within 1 month of the loan disbursement date to prevent disqualification.
② Income Requirements (Combined Annual Income for Married Couples)
The applicant’s and their spouse’s income from the preceding year are combined and evaluated, with upper limits varying by type.
| Category | Income Standard (Combined for Married Couples) | Notes |
|---|---|---|
| General Beotimmok | 50 million KRW or less | Basic requirement |
| Newlywed Household | 75 million KRW or less | Married within 7 years or planning to marry within 3 months |
| Public institutions relocated to Innovation Cities / 2 or more children | 60 million KRW or less | Preferential treatment for households with multiple children or regional relocation |
| Youth-only Beotimmok | 50 million KRW or less | Based on single or combined couple income |
💡 Notes when calculating income
For employees, it is based on the gross salary shown on the previous year’s withholding tax receipt. If you changed jobs or have worked for less than 1 year, the salary for the most recent months is annualized, which may result in an income higher than expected.
③ Net Asset Value Standard (HUG Fund-e-Deundeun Asset Screening)
One of the trickiest thresholds for Housing and Urban Guarantee Fund loans is the asset screening.
- Asset standard: The combined net asset value of the applicant and spouse must be 345 million KRW or less
- Calculation method: Based on net assets calculated by deducting liabilities (existing loan balances) from the sum of real estate, general assets (vehicles, etc.), and financial assets (savings, deposits, stocks).
- Frequent causes of disqualification:
- Need to check whether an existing commercial bank jeonse loan is properly reflected as a liability if it is subject to refinancing
- Cases where housing subscription deposit balances, stock valuations, or high-end vehicle values are unexpectedly counted as financial assets and exceed the limit (need to prepare for advance explanation procedures)
📌 Checkpoint
If you meet the basic three requirements (non-homeownership, income, and assets), you must now check whether there are any disqualification factors regarding the “house you plan to move into (target housing)” and the “timing of refinancing application.”
Please select if you would like the next table of contents written:
Top 4 Core Causes of Bank Review ‘Disqualification’
“I passed the Fund-e-Deundeun eligibility screening, but I was rejected at the bank teller counter.”
This is the most baffling moment in the actual Beotimmok refinancing process. Even if you meet the preliminary qualifications (income and assets), disqualifications frequently occur due to rule discrepancies during the bank counter’s final evaluation stage. You must check the 4 typical causes of disqualification in advance to prevent failure.
① Application Timing Mismatch: “Rejected by Just a Single Day”
Refinancing loans have much stricter golden times for application than general new loans.
- Refinancing right after moving in: You must apply within 3 months based on the balance payment date (or resident registration move-in report date). Even if you are just one day past the 3-month mark, refinancing is entirely blocked until the lease renewal period.
- Refinancing upon contract renewal: You must write a renewal contract prior to the expiration of the existing lease agreement and apply within a specified period before or after the renewal date (deposit increase date).
- Common mistakes: Typical cases include remaining in an implicit renewal status after the contract expiration date has passed, or missing the application window due to receiving the fixed date (Hwakjeong-ilja) late.
② Ineligible Target Housing: “The Space Is Perfect, but the Building Register Is the Problem”
Even if the borrower’s conditions are flawless, the loan cannot be executed if the housing itself falls short of the Fund’s standards.
- Exceeding exclusive use area: Only an exclusive use area of 85㎡ or less (100㎡ or less in eup/myeon areas outside the Seoul Metropolitan Area) is eligible. This is based purely on the exclusive use area, not the common area on the certified copy of the real estate register.
- Lease deposit ceiling: If the deposit exceeds the limit—such as 300 million KRW for general Beotimmok in the Seoul Metropolitan Area (200 million KRW for non-metropolitan areas), 400 million KRW for newlyweds in the Seoul Metropolitan Area (300 million KRW for non-metropolitan areas), or 300 million KRW for Youth-only—not even 10 KRW of support will be provided.
- Checking for illegal structures and designated use: Even if registered as a residence on the certified copy of the real estate register, if it is listed on the building register as a neighborhood living facility (illegal conversion of commercial property into residential) or marked as an ‘illegal structure’ due to unauthorized expansion, it will be rejected immediately.
③ Guarantee Certificate Issuance Denial: Confusion Over HUG vs. HF Standards
The Beotimmok loan structure does not involve borrowing bank money directly, but rather executing a loan secured by a guarantee certificate from a public institution. If you misjudge the review criteria for each institution, issuance of the guarantee certificate will be rejected.
| Category | HUG (Korea Housing & Urban Guarantee Corporation) | HF (Korea Housing Finance Corporation) |
|---|---|---|
| Review Focus | Rights relationship and market price of the target property (housing) | Income and credit score of the applicant (borrower) |
| Major Causes of Rejection | Ineligible if the sum of senior claims (collateral mortgages) + jeonse deposit exceeds a certain ratio of the officially assessed price (housing price valuation standard) (blocks ‘tin-can jeonse’ risk) | Cases where the guarantee limit is insufficient due to lack of proof of income or excessive existing credit loans |
| Issues During Refinancing | Cannot proceed if the landlord refuses to receive the notification of bond assignment | Loan limit shortfall due to insufficient recognized income for freelancers and individuals with no income |
④ Credit Rating and Existing Short-Term Loans: “The Butterfly Effect of a Minor Card Loan”
Even for a Fund loan, it goes through the bank’s credit evaluation, which introduces the borrower’s individual credit risk.
- Secondary financial sector short-term loans: Using card loans, cash advances, or savings bank loans right before the refinancing evaluation leads to a drop in credit score along with failing internal credit evaluation tiers.
- Delinquency history: If even a minor short-term delinquency history of 100,000 KRW or more—such as telecommunications bills or card balances—is registered in the electronic records, it becomes grounds for disqualification in the guarantee certificate evaluation.
- DSR/DTI limit interference: While general jeonse loans are often excluded from DSR calculations, having a large volume of existing credit loans can lead to reductions or disqualification notices depending on the handling bank’s internal debt repayment capacity assessment standards.
📌 Core Checkpoint
To prevent disqualification, before submitting documents, you must complete the rights relationship check on the certified copy of the register and building register, finalize application timing, and thoroughly manage your credit over the past 3 months in an integrated manner.
Please select an item below if you would like the next step written:
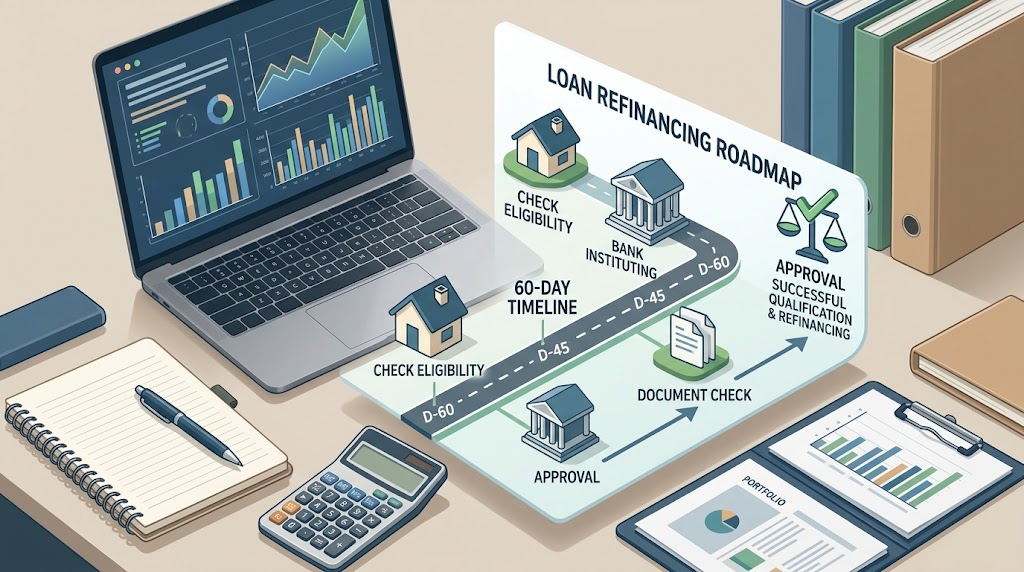
Step-by-Step Refinancing Process and Timeline (From D-60 to D-Day)
“Applying a week before should be fine, right?”
Absolutely not. Unlike general commercial bank jeonse loan extensions, Beotimmok refinancing must go through a triple process: ‘Fund eligibility screening + guarantee agency guarantee certificate evaluation + coordination of existing loan repayment.’
If the schedule gets mixed up and the refinancing funds are not disbursed by the existing loan’s maturity date, unfortunate situations arise where it is treated as delinquent or you are forced to extend the existing loan at high interest rates against your will. Here is a standard 60-day roadmap for successful refinancing.
⏳ D-60 (2 months before loan maturity): Landlord consultation and final review of the register
Prior consent from the lessor (landlord) and confirmation of renewal terms:
Check whether it is a renewed contract and whether there is an increase in deposit.
In the case of HUG Safe Jeonse Loan refinancing, the landlord’s cooperation (receiving mail and phone verification) is essential for ‘receipt of the notification of bond assignment’ or ‘pledge creation’, so you must ask for their understanding in advance.
Check changes in the certified copy of the register:
Be sure to inspect on the Internet Registry Office whether the landlord has set up additional collateral mortgages (taken out loans) against the house after initial move-in. If senior rights have been established, guarantee certificate issuance may be denied.
⏳ D-45 (45 days before loan maturity): Drafting renewal contract and applying on ‘Fund-e-Deundeun’
Securing a contract with a fixed date:
If there is a change in the deposit, draw up a renewed contract and receive a new fixed date (Hwakjeong-ilja) via the community center or the Internet Registry Office. (For a simple renewal without deposit changes, advance confirmation with the handling bank is required to check if proceeding with the initial contract is acceptable)
Application for Housing and Urban Guarantee Fund ‘Fund-e-Deundeun’ eligibility screening:
Apply for a refinancing loan online via the mobile app or website (enhuf.molit.go.kr).
At this stage, advance screening of the income and assets of the borrower and spouse begins through public data scraping. Typically within 3 to 5 business days, a KakaoTalk notification stating ‘Preliminary Asset Screening Qualified’ arrives.
⏳ D-30 (1 month before loan maturity): Visiting trustee bank branch and submitting documents
Visit the bank counter immediately after confirming the qualification notice:
Find a branch to proceed with refinancing among Housing and Urban Guarantee Fund trustee banks such as Woori, Shinhan, KB Kookmin, Hana, and NH NongHyup.
💡 Document packaging tip to reduce bank teller fatigue:
From the bank teller’s perspective, Beotimmok refinancing involves more complicated work than a general new loan. If you neatly arrange and submit the necessary documents (resident registration certificate and abstract, withholding tax receipt, contract with a fixed date, etc.) in a clear file folder according to the checklist order, the review speed will be much faster without rejections.
Initiate guarantee certificate (HUG/HF) evaluation:
The bank representative reviews the documents and requests guarantee approval from the guarantee agency. It takes about 1 to 2 weeks.
⏳ D-7 (1 week before loan maturity): Loan approval and agreement execution
Execution of electronic agreement (or written agreement):
Once guarantee approval and final approval are complete, sign the loan agreement documents through the bank app.
Confirm existing loan bank repayment schedule:
Confirm with the new bank’s loan officer the method for requesting a virtual account for repaying the existing bank loan, and coordinate in advance the handling method for the same-day repayment receipt.
🏁 D-Day (Disbursement day): Same-day repayment of existing loan and receipt confirmation
Execution of refinancing funds:
Generally, the new Beotimmok loan funds do not pass through your personal account; instead, they are remitted directly from the new bank to the existing loan bank for automatic repayment (interbank refinancing repayment method).
Repayment receipt and deregistration check:
Confirm whether the existing bank’s full loan payment (settlement) certificate or repayment receipt has been properly registered in the new bank’s computer system.
Deregistration of pledge/bond:
The pledge or bond assignment established by the existing bank is released and replaced by the new Beotimmok guarantee agency’s setup, bringing the refinancing procedure to a complete finish.
📌 Practical Core Point
Even if judged qualified in the Fund-e-Deundeun eligibility screening, it takes at least 2 to 3 weeks for the guarantee agency evaluation after submission at the bank counter. You must complete the Fund-e-Deundeun application at least 45 days before maturity (D-45) to prevent nerve-racking situations caused by review delays.
If you want the next steps written, please click the buttons below:
Write Section 5: ‘Essential Preparation Documents Guide for Bank Counters’
Write the final ‘Epilogue and Summary Checklist’
Essential Preparation Documents Guide Before Visiting the Bank Counter
“I missed one document and had to go back and forth to the bank three times…”
This is the most common tragedy experienced during consultations for Beotimmok refinancing loans. Because Fund loans involve intertwined screening entities—bank + Housing and Urban Guarantee Fund + guarantee agency (HUG/HF)—the required documents are much more demanding than those for general credit loans.
In particular, all issued documents must be issued within 1 month of the loan application date (with all 13 digits of the Resident Registration Number displayed). Here is a tailored list of packaged documents that can get an approval sign in one go when placed on the bank teller’s desk.
① Identity and Household Verification Documents (Issued via Gov24)
- Resident Registration Certificate (Deungbon): Address change history for the past 5 years and all 13 digits of household members’ Resident Registration Numbers displayed
- Resident Registration Abstract (Chobon): Based on oneself, including full address change history (from birth)
- Family Relationship Certificate (Detailed):
- Must be issued as ‘Detailed’ for all single householders, unmarried persons, prospective newlyweds, and married couples
- If separated from spouse on the Resident Registration, spouse’s Resident Registration Certificate and Family Relationship Certificate are additionally required
② Income and Employment Proof Documents (NTS Hometax / National Health Insurance Service)
Required documents vary depending on the income calculation method. (Based on the preceding year)
| Job Category | Essential Document List | Notes |
|---|---|---|
| Employee (Earned Income Earner) | ① Certificate of Employment (Company official seal mandatory)
② Wage and Salary Income Withholding Tax Receipt (Official seal stamped) ③ Certificate of Health Insurance Qualification Loss and Acquisition |
Workers with less than 1 year of employment need recent monthly pay slips (Class A Earned Income Withholding Tax Verification) |
| Business Owner (Sole Proprietor) | ① Certificate of Business Registration
② Certificate of Income Amount (Comprehensive Income Tax filing) |
Can be printed from Hometax |
| Freelancer / Other | ① Certificate of Commission (Affiliation)
② Certificate of Income Amount ③ Business Income Withholding Tax Receipt |
Consider applying HF special criteria if income cannot be proven |
| No Income / Homemaker | ① Certificate of Facts (No Filing Record)
② Certificate of Health Insurance Qualification Loss and Acquisition |
For confirming dependent status |
③ Target Housing and Contract-Related Documents (Real Estate Agency / Community Center)
- Original Lease Agreement with Fixed Date:
- Bring both the original initial contract and the renewal contract (if deposit changed)
- The contract must bear a fixed date (Hwakjeong-ilja) stamp/certification label from the community center or Internet Registry Office
- Lease Deposit Down Payment (5% or more) Receipt:
- Mandatory for refinancing upon new move-in; for renewal refinancing, this can be substituted with an existing deposit full payment breakdown or receipt
- Certificate of All Registered Matters (Certified Copy of Register): 1 copy each for land/building (issued including deregistered items)
- Building Register (General Header / Header): For checking whether it is marked as an illegal structure and verifying designated use such as neighborhood living facility
④ Existing Loan Verification Documents (Issued by Existing Bank)
Due to the nature of refinancing loans, you must prove that ‘you are properly using the existing jeonse loan.’
- Financial Transaction Confirmation Certificate:
- Issued at the branch or via internet banking of the existing bank where you currently hold the jeonse loan
- Purpose: For loan refinancing / Must clearly state the loan type, loan execution date, maturity date, balance, and type of collateral (pledge/bond assignment, etc.)
- Loan Interest Payment History Statement (recent 6 months to 1 year): Depending on the bank, this may be requested to prove regular payments and no history of delinquency
💡 30-Second Practical Tip Before Visiting the Bank
When organizing your documents, prepare an A4 file folder and attach index tabs labeled [Personal Documents / Income Documents / Housing Documents / Refinancing Documents] before submitting. This dramatically reduces the review fatigue of the loan officer in charge and speeds up same-day application processing noticeably.
Would you like to move on to the final closing step?
Korean version: 한국어로 읽기