Prologue: Once You’ve Calculated the Refund, It’s Time to Look at the ‘Value Beyond Maturity’
If you have calculated the amount you will hold in your hands after 5 years by plugging in the government contribution and tax-exempt benefits for your income bracket, a concrete figure of “around 50 million KRW” has likely formed in your mind. However, many young adults only look at the simulated numbers of their account balance, without deeply considering how this money will reshape their life’s financial trajectory 5 years down the road.
The sum of 700,000 KRW per month is by no means a small amount for young adults in their 20s and 30s, especially those new to the workforce. Setting aside a substantial portion of your salary to lock away for 60 months goes beyond simple saving; it is akin to an arduous marathon that requires moderating regular spending desires every single month. If your goal remains merely “earning a few million KRW in interest stamped in your bankbook upon maturity,” it becomes easy to succumb to spending temptations or slumps in the 2nd or 3rd year and waver before the allure of early termination.
What truly deserves attention at this stage is the ‘leverage beyond maturity’ that lies past the simply calculated refund amount.
The lump sum of around 50 million KRW held in hand after 5 years is not just a bank balance.
Interlocked with the Youth Housing Dream Subscription Account or low-interest policy loans, it serves as a practical down payment for homeownership;
The mere fact of completing a national policy finance program over 5 years without a single delinquency stands as powerful proof of creditworthiness and sound financial history in the banking sector;
And the experience of self-regulating fixed limits each month to build this sum builds the fundamental financial stamina to grow lifelong assets.
If you felt anticipation while running the refund calculator, it is now time to broaden your perspective and flesh out the structural benefits this 5-year completion will bring to your life and the asset blueprint beyond maturity. In the following sections, we will examine one by one the decisive advantages that completing the 5-year Youth Leap Account brings.
At-a-Glance Summary of the Core Real Yield on Maturity Refunds
The stated headline interest rate written on the Youth Leap Account product sheet is around ‘up to 6.0% per annum’. However, when comparing the actual net amount received in hand at maturity 1-on-1 with standard commercial bank installment savings, the real yield felt by subscribers leaps well past the 8–9% per annum range.
This is because it is not structured to pay simple bank interest alone, but combines the dual boosters of government matching contributions and full exemption from interest income tax.
- Mechanism Behind the 6.0% Headline Rate Leaping to an Effective 8–9% per Annum
To produce the same maturity refund as the Youth Leap Account with standard commercial installment savings, one would have to search for high-interest promotional products rarely seen at bank counters.
- Additional Interest Rate Conversion Effect of Government Contributions:
The contribution accumulated at 21,000 KRW to 24,000 KRW per month depending on the income bracket totals around 1.26 million to 1.44 million KRW over 5 years. Considering only pure government subsidies relative to principal (up to 42 million KRW), a fixed return of about 3.0% to 3.4% is additionally added, which equates to receiving an extra interest rate of around 1.0 to 1.5%p or more per annum when back-calculated into bank interest rates.
- 100% Exemption from 15.4% Interest Income Tax (Tax-Free):
When about 6 million KRW in interest is generated in a regular installment savings account, more than 920,000 KRW is deducted as tax. Because the Youth Leap Account does not deduct a single won of this tax, it creates an additional interest rate boosting effect of about 1.0 to 1.3%p per annum when converted to a pre-tax interest rate.
- Contracted Compound Interest Accruing on the Contribution Itself:
The contribution deposited by the government also does not sit idle in the account; instead, interest compounds monthly at the same rate as the bank’s maximum contracted interest rate.
- Summary of Net Payout Gap: General Taxable Savings vs. Youth Leap Account
When contributing 700,000 KRW per month for 60 months (total principal of 42 million KRW), comparing the difference in maturity net payouts between standard commercial installment savings and the Youth Leap Account with concrete figures reveals a stark contrast.
| Category | Standard Commercial Savings (Assuming 4.0% p.a.) | General High-Interest Savings (Assuming 5.0% p.a.) | Youth Leap Account (Max 6.0% p.a. + Contribution) |
|---|---|---|---|
| 5-Year Deposited Principal | 42 million KRW | 42 million KRW | 42 million KRW |
| Total Accrued Interest | Approx. 4.27 million KRW | Approx. 5.34 million KRW | Approx. 5.3 million ~ 6.4 million KRW |
| Government Contribution | 0 KRW | 0 KRW | Approx. 1.26 million ~ 1.44 million KRW |
| Interest Income Tax (15.4%) | – Approx. 660,000 KRW deducted | – Approx. 820,000 KRW deducted | 0 KRW (Fully Tax-Exempt) |
| Final Maturity Net Payout | Approx. 45.61 million KRW | Approx. 46.52 million KRW | Approx. 48.6 million ~ 50 million KRW |
| Net Take-Home Earnings | Approx. 3.61 million KRW | Approx. 4.52 million KRW | Approx. 6.6 million ~ 8 million KRW |
Even if you maintain a 4–5% annual rate in regular bank installment savings for 5 years, the actual earnings you take home remain in the 3 to 4 million KRW range after deducting interest income tax. In contrast, thanks to government contributions and tax-exempt benefits, the Youth Leap Account allows you to fully take home net earnings reaching up to 7 to 8 million KRW.
💡 Key Takeaway at a Glance
The maturity payout of the Youth Leap Account is not just a simple 6.0% annual savings account, but an unrivaled policy finance product delivering a real perceived yield of around 8.5% per annum driven by the interlocking gears of “Government Contribution + Zero Tax + Compound Interest.”
The mere fact that no principal-protected deposit or savings product on the market can deliver a guaranteed after-tax return in the 8% range per annum over 5 years makes completing the 5-year term of the Youth Leap Account the most reliable and safest first step in wealth building.
4 Decisive Maturity Advantages Enjoyed Upon Completing 5 Years in the Youth Leap Account
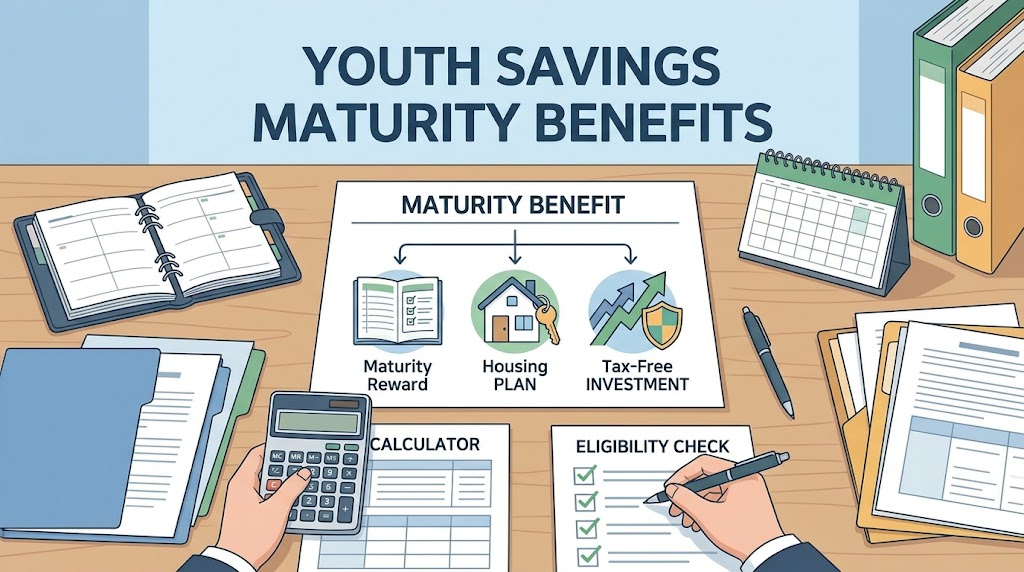
Reaching the 5-year maturity of the Youth Leap Account is not simply the conclusion of savings, but serves as the most powerful launching pad for full-scale asset growth and economic independence. Here are the four decisive practical benefits you will hold in your hands when you resist the temptation of early termination and stamp your completion of 60 months.
- Seed Money Power of a 50 Million KRW Lump Sum (The Tipping Point of Wealth Building)
In personal finance, the speed of moving toward 100 million KRW based on a seed money foundation of 50 million KRW is on an entirely different level compared to saving from 0 to 10 million KRW.
The Beginning of Full-Scale Asset Acceleration: A cash asset in the 50 million KRW range generates an effective cash flow of 2 to 2.5 million KRW annually even when placed solely in stable dividend stocks or bond instruments yielding 4 to 5% per annum.
Expansion of Life Choices: It serves as a reliable emergency fund to withstand gap periods of several months during job changes or career transitions, while providing bargaining power to reduce the risk of jeonse fraud and choose safer living environments.
- Linkage Benefits with the Youth Housing Dream Subscription Account and Policy Mortgages
The government has established powerful policy incentives so that Youth Leap Account maturity recipients can immediately connect these funds to a housing ladder.
Lump-Sum Transfer Linkage to the Housing Dream Subscription Account: You can inject part or all of your maturity refund into the ‘Youth Housing Dream Subscription Account’ as a lump-sum payment. Through this, you not only inherit high-interest benefits (up to 4.5% per annum), but also instantly meet the deposit requirements of the housing subscription account.
Synergy with the Youth Housing Dream Loan: If selected in a housing lottery subscription, it links to qualifications for a dedicated mortgage offering ultra-low interest rates starting as low as 2.2% per annum for up to 80% of the sale price, seamlessly completing down payment and balance financing plans for purchasing a home.
- Credit Score and Financial History Premium
A track record of faithfully making contributions to a long-term policy financial product for 5 years (60 months) without delinquency possesses extremely high credit value in itself within the banking sector.
Recognition of Non-Financial and Faithful Payment Records: Policy finance savings completion data is reflected as a positive financial transaction history by credit rating agencies (KCB, NICE, etc.), resolving the chronic ‘Thin Filer’ problem faced by young entrants to the workforce.
Preferential Loan Interest Rates Going Forward: The established prime credit rating directly translates into reduced spread margins and preferential loan limits by individual banks when applying for jeonse loans or mortgage loans in the future, returning benefits in the form of saving millions of KRW or more in loan interest.
- Acquiring Spending Control and Financial Stamina Through Forced Savings
An intangible asset even more precious than the refund converted into numbers is the ‘cash flow management capability’ acquired over 5 years.
Automatic Diet on Expenses: The 5-year habit of setting aside 700,000 KRW first every month and living on the remaining funds builds a robust spending firewall preventing excessive consumption.
Sense of Self-Efficacy in Goal Achievement: The success experience of personally completing a long-term financial project to the very end instills a solid financial mindset to sustain long-term compound investing without being swayed by short-term market volatility.
How Should You Grow the 50 Million KRW Maturity Payout? (Practical Asset Allocation Guide)
The maturity refund of around 50 million KRW accumulated through 5 years of discipline is the most critical seed money one can hold during their early career. However, when a large sum of money comes in all at once after long perseverance, it is easy to make the mistake of increasing spending out of a compensation mindset or damaging principal through reckless high-risk investments driven by impatience.
Here is a practical 3-tier portfolio allocation strategy to connect this valuable seed money to the next stages of ‘building 100 million KRW in assets’ and ‘housing stability.’
- Short-Term Goal: Lump-Sum Deposit into Youth Housing Dream Subscription & Housing Deposit Separation (Approx. 20M–30M KRW)
The top-priority objective for maturity funds is establishing a ‘housing stability ladder,’ which is the biggest challenge for young adults.
- Linking Lump-Sum Deposit to the Youth Housing Dream Subscription Account:
Under government policy benefits, you can deposit the Youth Leap Account maturity refund into the Youth Housing Dream Subscription Account as a lump sum all at once. It is wise to secure preferential interest rates of up to 4.5% per annum while instantly satisfying subscription deposit threshold criteria, thereby locking in eligibility for dedicated mortgage benefits starting as low as 2.2% per annum in the future.
- Didimdol & Beotimdol Jeonse Deposit Firewall:
If you are planning to become independent or move, setting aside funds for the self-funded deposit (typically 20–30% of the jeonse price) for low-interest government policy loans (such as the Youth Beotimdol Jeonse Loan) serves as housing leverage that blocks high-interest monthly rent expenses.
- Mid- to Long-Term Investment: Growing Secondary Tax-Free Compound Interest via ISA (Approx. 15M–20M KRW)
Pouring the principal built over 5 years via installment savings entirely into individual stocks or cryptocurrencies at once is strictly inadvisable. Indirect investment tracking market average returns through an Individual Savings Account (ISA)—a tax-sheltered vehicle—is the most stable approach.
- Utilizing ISA Contribution Limits:
An ISA allows contributions up to 20 million KRW per year (up to 100 million KRW over 5 years), offering complete tax exemption on net profits up to 2 million KRW for standard accounts (4 million KRW for general/low-income accounts), with excess profits benefiting from separate taxation at 9.9%. You can secure tax continuity by carrying over the tax-exempt benefits of the Youth Leap Account into an ISA.
- Dollar-Cost Averaging into Index-Tracking ETFs and Dividend Assets:
By regularly splitting investments monthly into domestic-listed US S&P 500, Nasdaq 100 ETFs, or stable US Dividend Dow Jones (SCHD-series) ETFs, you can target capital returns (targeting 7–10% per annum) above bank deposit/savings rates (3–4% per annum).
- Liquidity Management: Separating Emergency Parking Accounts & Excluding Reckless Theme Stocks/Coins (Approx. 5M–10M KRW)
No matter how sound an investment plan is, if you have to liquidate investments due to living costs or sudden unexpected expenses, your portfolio collapses.
- Separating into High-Yield Parking Accounts:
Set aside 5 to 10 million KRW, equivalent to 3 to 6 months of monthly living expenses, into parking accounts or CMAs at internet-only banks (Toss, KakaoBank, K Bank, etc.) that pay interest at around 2.5 to 3.5% per annum even for a single day’s deposit.
- Blocking the “All-in” Mindset (FOMO):
The impatience of thinking, “Now that I’ve gathered 50 million KRW over 5 years, I will instantly turn it into 100 million KRW with theme stocks or leveraged coins,” can reduce 5 years of effort to nothing in an instant. High-risk investments carrying substantial risks of principal loss should be strictly capped within 10% of total seed money.
📌 Recommended Portfolio at a Glance
| Asset Category | Allocation Share | Recommended Vehicle | Expected Effect |
|---|---|---|---|
| Housing and Subscription (Safe Asset) | 50% (25 million KRW) | Lump-sum deposit into Housing Dream Subscription Account / Jeonse deposit | Securing preferential subscription interest rates + Linkage to ultra-low-interest presale mortgage loans |
| Mid- to Long-Term Investment (Growth Asset) | 35% (17.5 million KRW) | Global index-tracking ETFs (such as S&P 500) within an ISA account | Maintaining tax savings (tax-free) + 7–10% compound annual growth |
| Emergency Liquidity (Safe Asset) | 15% (7.5 million KRW) | Tier 1 bank parking account / Brokerage CMA | Preparing for unexpected expenses + Preventing forced liquidation of investments |
A lump sum of 50 million KRW is not the ‘end,’ but the most reliable ‘stepping stone’ for leaping toward the next milestone of 100 million KRW in assets. Try taking your asset growth rate to the next level through a diversified strategy that balances safety and profitability.
Epilogue: Mindset for Completing the 5-Year Maturity Without Wavering
Once you have reviewed all the refund calculation methods for the Youth Leap Account and the diverse financial benefits to be gained at maturity, the final piece of the most critical puzzle is the ‘execution power to see through the full 60 months.’
A period of 5 years is by no means short. A savings slump arriving in the 2nd year, job changes or moving out on your own around the 3rd year, and a compensation mindset triggered by observing the spending of peers—numerous temptations to cancel early are bound to arise. Here are 3 mindsets you must take to heart to turn this marathon entirely into your victory.
- Viewing It Not as ‘Giving Up Short-Term Consumption,’ but as an ‘Advance Payment on My Future’
When saving 700,000 KRW every month, skepticism may arise: “Am I living too restrictively right now?” or “Am I missing out on enjoying my youth just to lock money away in a bankbook?”
Shift in Perspective: The money deposited right now is not an expenditure that disappears, but an advance payment deposited early into your future account at the highest fixed interest rate (effectively 8–9% per annum) to grant yourself freedom of choice 5 years later.
Establishing a Spending Benchmark: The experience of exercising discipline to save 50 million KRW over 5 years corrects lifelong consumption habits and builds a solid financial immunity that filters out impulse buying and unnecessary fixed expenses.
- Not Comparing Yourself to Surrounding Mirages of Quick Jackpots
Whenever news of surging stocks, crypto crazes, or real estate booms breaks, a feeling of urgency (FOMO) may strike: “Is it right to lock away money for 5 years just to get a few tens of thousands of won in monthly government contributions?”
The Weight of Principal Protection: Investment vehicles boasting high returns carry the corresponding risk of slashing your principal by more than half. Regardless of market volatility, the Youth Leap Account is the only product where the government and banks collaborate to guarantee 100% principal protection + interest tax exemption + fixed subsidies.
Respecting the Sequence of Wealth Building: Investing without seed money is like building a castle on sand. It is never too late to step into full-scale market investing after completing the solid fundamental stamina of 50 million KRW.
- Overcoming Slumps by Setting ‘Waypoints (Milestones)’
Looking at the massive number of 60 months from the very start can feel overwhelming. Breaking down the long race and recognizing it as staged goals significantly reduces psychological burden.
1st Milestone (1 Year / 12th Installment): The phase where the savings routine settles fully into daily life as 8.4 million KRW in principal and contributions accumulate in the account
2nd Milestone (3 Years / 36th Installment): The phase entering the safety line where policy improvements allow you to secure tax-free status and 60% of contributions
Final Completion (5 Years / 60th Installment): The phase of completion where you hold a 50 million KRW lump sum and leap forward into the Youth Housing Dream Subscription and ISA
💡 Closing Thoughts: Cheering on Your First Leap to be Completed in 5 Years
The figure of 50 million KRW is not merely a balance; it is a ‘certificate of financial integrity’ proving that you overcame temptations every month and kept a promise to yourself for 5 years during your youth in your 20s and 30s.
This solid seed money will serve as a springboard for future housing stability and a dependable anchor allowing you to take on challenges without hesitation at critical crossroads in life. Do not forget the initial determination you held while working the calculator, and picture yourself confidently walking out of the bank counter upon maturity in 5 years.
Korean version: 한국어로 읽기