Introduction: Youth Leap Account, Adding Government Subsidies to Savings—Why Is It Essential?
“I’m working hard to save and putting money into installment savings every month, but when I think about skyrocketing prices and housing costs, buying my own home or raising a lump sum feels so far away… Bank interest alone is completely insufficient to grow my assets, so aren’t there any reliable asset-building support funds for young people?”
The very first realistic wall that early-career workers or young professionals face when they receive their monthly paycheck and start saving is the slower-than-expected speed of asset growth. Amidst general savings interest rates that barely keep pace with the inflation rate, saving silently with just regular savings brings great anxiety about the future.
“When you want to gather a lump sum with your own strength but feel the limits of savings alone…”
“If you’re curious about the reality of that savings account where the government adds money on top of your savings?”
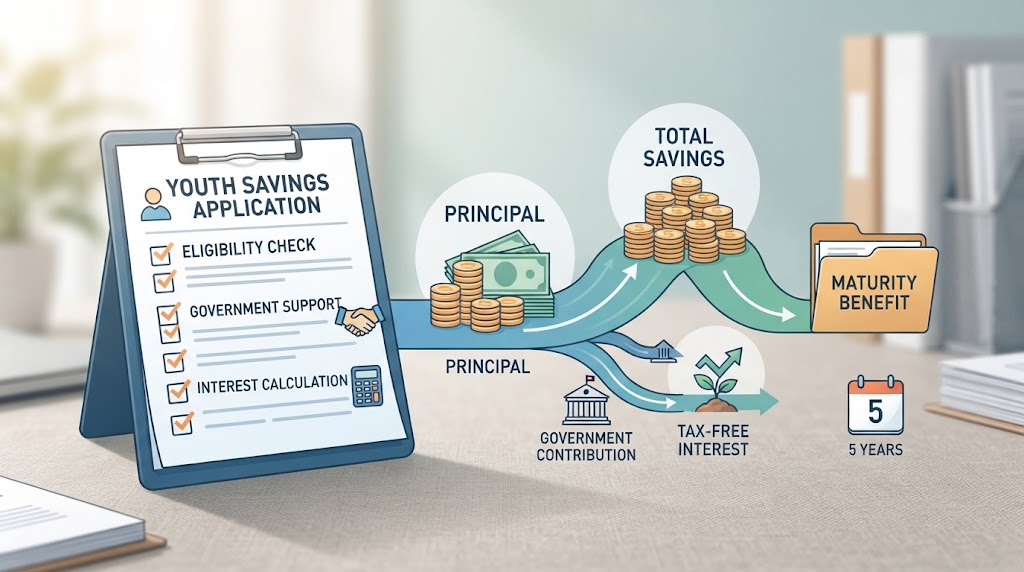
The representative policy financial product where the government directly rolled up its sleeves to support the solid asset building of young people is none other than the ‘Youth Leap Account’. If you save a certain amount every month, the state matches and adds a ‘government contribution’ according to your income bracket, and tax-exemption benefits on interest income are added, creating an enormous maturity refund effect incomparable to general savings products.
“Savings that just blindly cut back are now over!”
“We will thoroughly dissect the refund calculation method that smartly adds government subsidies and interest earnings to maximize your assets.”
Then, what on earth are the subscription conditions for the Youth Leap Account, and how much government subsidy will be added to my payments to return as a final refund? From now on, let’s examine one by one all of those amazing benefits and calculations!
Complete Summary of the Basic Structure and Subscription Qualifications of the Youth Leap Account
“I’ve heard a lot of stories that the Youth Leap Account is a cheat key for building a lump sum, but what kind of structure is this product operated under, and can I really satisfy the eligibility requirements?”
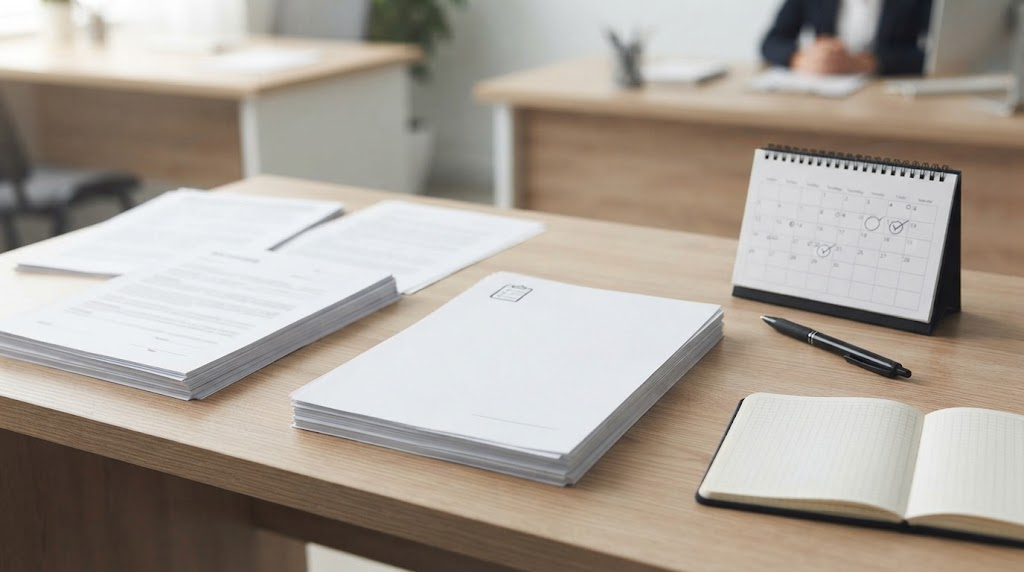
As the government support benefits are exceptional, it is most important to meticulously check the subscription qualification conditions and income requirements. We explain in detail the overall structure of the Youth Leap Account and the subscription qualification criteria that must be checked to build assets solidly until maturity.
- Core Structure of the Youth Leap Account: 5-Year Maturity, Maximum Monthly Payment Limit of 700,000 Won
The Youth Leap Account is a 5-year (60-month) maturity savings product created to support the mid- to long-term asset formation of the youth generation.
Autonomous payment method: You can freely deposit the amount you want every month from 10,000 won up to a maximum of 700,000 won (in units of 10,000 won), so early-career workers with unstable incomes can participate without burden.
Complex support benefits: The ‘government contribution’ matched by the state to the amount you paid, bank interest, and ‘tax-exemption benefits’ on interest income form a triple harmony to exert explosive refund synergies at maturity.
- Complete Checklist for Subscription Qualifications (Age and Income Criteria)
Unfortunately, not all youth can sign up, and both age and income criteria must be met.
Age requirement: Youth aged 19 or older and 34 or younger based on the account opening date (If military service obligations have been fulfilled, up to 6 years of military service period is deducted from the age calculation, increasing the actual eligible subscription age.)
Personal income requirement: Individuals whose total salary in the previous tax period was 75 million won or less (for comprehensive income tax reporting subjects, comprehensive income amount of 63 million won or less)
Household income requirement: Individuals whose sum of household member income falls under 180% of the median income (based on household members listed together on the resident registration copy)
💡 Core Points for Youth Leap Account Subscription Qualifications
Since income requirements are reviewed based on the income at the time of subscription (or the previous tax period) rather than criteria renewed every year, it is advantageous to apply quickly when you meet the conditions.
Then, just how much money will the government actually add to my savings? Let’s thoroughly dissect the ‘structure of government contributions and tax-exemption benefits’ that you are most curious about in the next chapter!
Understanding the Structure of Government Contributions and Tax-Exemption Benefits
“They say the state adds money every time I pay into my installment savings, but exactly how is the government contribution calculated and how much is paid? And how much does the tax-exemption benefit practically help my returns?”
The reason the Youth Leap Account is decisively different from installment savings products of general commercial banks is thanks to two powerful wings: ‘government contributions’ and ‘interest income tax exemption’ supported by the state. We will thoroughly dissect the core structure of how the government adds money according to your income bracket.
- Government Contribution Matching Ratio and Payment Method by Income Bracket
The government contribution is an amount supported by the state according to a set matching ratio based on the subscriber’s personal income level and monthly payment amount.
Differential support by income bracket: The lower the total salary amount (e.g., annual 24 million won or less, etc.), the higher the state’s matching ratio, allowing you to receive more government contributions, and as income increases, the matching ratio is adjusted step by step.
Monthly payment linked limit: Since the government contribution is calculated for the maximum monthly recognized payment amount (e.g., within prescribed limits such as the 400,000 won or 700,000 won line), setting the optimal monthly payment amount that fits your income bracket is the core trick to max out contributions.
- The Power of Interest Income Tax Exemption and Savings Encouragement Benefits
When you sign up for a general bank installment savings account, 15.4% of your interest income is deducted like a tax bill for rural special tax and income tax, but the Youth Leap Account provides a full tax-exemption benefit on interest income.
Maximizing real returns: Because you pay zero tax on the interest accumulated steadily over a not-insignificant period of 5 years, it creates a massive difference in the actual received amount at maturity compared to general products in the total principal and interest received.
💡 Core Points of Government Contribution and Tax-Exemption Structure
Government contributions are not directly deposited as cash into the savings account every month, but are instead paid together with the principal at maturity or according to a set accumulation structure, so their true value explodes when the 5-year maturity is fulfilled.
Then, let’s check the specific simulation calculation method in the next chapter to see exactly how much total refund (maturity payout) you will hold in your hands after 5 years when actually paying a certain amount every month!
Practical Refund and Maturity Payout Calculation Method Simulation
“I understand the structure of the Youth Leap Account and the government contribution system, but when I steadily pay 400,000 won or 700,000 won every month for 5 years, what exactly will the final maturity refund stamped in my bankbook be after 5 years?”
More important than a hundred words is, as always, the simulation of the actual amount entering my bankbook. Let’s specifically understand the final refund calculation process completed by combining the principal paid by oneself, the government contribution added by the state, and the interest earnings and tax-exemption benefits with compound interest effects applied.
- Estimated Maturity Payout Simulation by Monthly Payment Amount (e.g., 400,000 Won, 700,000 Won)
The Youth Leap Account creates differences in the total amount received at maturity depending on the individual’s income bracket and monthly payment amount.
When depositing 400,000 won per month: Government contributions according to the income matching ratio, bank interest (base rate + preferential rate), and tax-exemption benefits are added, so upon 5-year maturity, a lump sum of about 27 million won to over 28 million won can be grabbed by nicely adding government subsidies and interest to the 24 million won principal.
When depositing the maximum 700,000 won per month: If surplus funds permit and you pay a total of 42 million won for 5 years (60 months) at the maximum limit of 700,000 won every month, the maximum matching government contribution and interest earnings explode and combine to achieve an enormous maturity refund (lump sum) approaching about 50 million won after 5 years.
- Calculation Process Combining Government Contributions and Interest Earnings
Maturity payout amounts are determined according to systematic financial calculation formulas rather than simple addition.
Principal accumulation: Total principal paid by the user over 5 years (e.g., 700,000 won × 60 months = 42,000,000 won)
Contribution accumulation: Government contributions according to monthly payments and interest thereon
Bank interest and tax-exemption application: Interest earnings calculated at agreed rates (such as a mix of fixed and variable rates for certain periods) on the entire principal and government contributions are combined intact without deducting a 15.4% tax
💡 Practical Refund Calculation Core Points
The refund of the Youth Leap Account is designed to maximize benefits when fulfilling the full 5-year maturity without terminating midway. Giving up midway results in losing both government contributions and tax-exemption benefits, making it important to wisely set monthly payments matching one’s financial situation.
Then, what are the practical pro tips that must be known to sail through to maturity without crises over a long period of 5 years? Let’s check in the next chapter!
Practical Pro Tips to Prevent Premature Termination and Maximize Benefits Until Maturity
“A period of 5 years is by no means short for early-career workers or youth. If one has to terminate midway due to sudden needs for a lump sum or income changes/job changes, all accumulated government contributions and tax-exemption benefits would be lost—how can one overcome crises and finish through to maturity?”
The biggest hurdle and key to success of the Youth Leap Account is ‘maintaining 5-year maturity’. We completely organize the practical pro tips and institutional devices that must be known to keep government subsidies and interest benefits fully as one’s own without giving up midway.
- Understanding Special Premature Termination Requirements in Advance (Marriage, Childbirth, First-time Homebuyer Home Purchase, etc.)
Just because money must inevitably be withdrawn or unexpected life events occur does not mean one unconditionally suffers losses.
Statutory recognized reasons: In case of falling under ‘special premature termination reasons’ recognized by the government such as subscriber’s death, overseas migration, first-time home purchase, marriage, or childbirth during the subscription period, unlike general premature termination, termination is possible while fully recognizing government contributions and tax-exemption benefits.
System utilization strategy: Rather than blindly choosing general termination when sudden funding demands arise, checking first whether one’s situation aligns with special premature termination requirements is the shortcut to preventing asset loss.
- Tips for Establishing a Realistic Funding Plan for Steady Payments
It is much more advantageous to maintain it to the end rather than signing up with an excessive amount and giving up midway.
Utilizing flexible payments: Since the Youth Leap Account allows free payments up to a maximum of 700,000 won every month, it is important to maintain the account even if you deposit a smaller amount during months when your income temporarily decreases or expenses are high.
Separating emergency savings: You must thoroughly separate living expenses from the 5-year savings and set up a separate short-term emergency fund account that can be broken in emergency situations, preventing you from touching the main Youth Leap Account.
💡 Core Points to Prevent Premature Termination
The Youth Leap Account is the best financial tech asset created by persistence and timing. If you steadily accumulate according to your own pace even if you are slightly out of breath, you will face a solid lump sum and refund beyond imagination after 5 years.
You have completely mastered all asset formation strategies and tips! Shall we check the warm closing remarks that will decorate the grand finale of this wonderful post?
Conclusion: Starting Solid Lump Sum Preparation and Asset Formation with the Youth Leap Account
So far, we have looked together at everything from the basic structure and subscription qualifications of the Youth Leap Account, the principles of government contributions and tax-exemption benefits that add wings to monthly payments, practical maturity refund simulation calculation methods, to premature termination prevention tips for completing the 5-year maturity.
For early-career workers and young professionals, saving goes beyond simply gathering money—it is the most certain first step to erase future anxiety and prepare for home purchase and independent self-reliance. However, amidst skyrocketing prices, there are clear limitations to growing assets with only earned income and general deposit/savings interest.
Shall we lightly retrace the core contents shared today once more?
First, if you meet the youth aged 19–34 and income requirements, actively utilize the 5-year maturity monthly payment structure of up to 700,000 won.
Second, maximize real returns through ‘government contributions’ according to matching ratios by personal income and interest income tax-exemption benefits.
Third, remember special premature termination requirements such as marriage, childbirth, and first-time homebuyer home purchase, and fully complete the 5-year maturity with a manageable payment plan.
This precious opportunity where the government adds strength to your savings is the smartest financial tech strategy to grab quickly when you meet the conditions. Taking today’s post as a solid compass, we hope you make the dream of building a solid lump sum a reality with the Youth Leap Account.
We sincerely hope this article served as a warm lighthouse for your successful asset formation journey. If you have any questions during the preparation process, please feel free to leave a comment anytime, and we sincerely cheer for everyone to smartly claim government subsidies and perfectly achieve your desired goals!
Korean version: 한국어로 읽기