Introduction: Why You Must Overcome the Temptation of Early Termination and Maintain the Youth Leap Account Until Maturity
Even while faithfully depositing money into a savings account every month, everyone has likely felt anxious and tempted to terminate at least once, wondering, “Is tying this money up for 5 years really a wise choice?”, “What if I suddenly need a large sum of money in the middle?” Especially as life goes on, when unexpected expenses arise or stories of people around making short-term profits through stocks, cryptos, and the like are heard, quietly maintaining the Youth Leap Account can sometimes feel tedious and frustrating.
However, the true value of the Youth Leap Account emphasized by financial experts and policy designers alike is hidden in the ‘final received amount that increases explosively when filling the period’. Because terminating midway turns everything built up so far—from government contributions to tax-exemption benefits—into a bubble, a rash choice becomes a shortcut to wasting enormous opportunity costs.
Then, just how overwhelming are the interest and benefits recorded in your bank account compared to regular savings when you quietly endure the long tunnel of 5 years and fulfill maturity? In today’s post, we will thoroughly dissect the reasons why you must robustly maintain the Youth Leap Account until maturity and the massive interest comparison benefits you can enjoy at that time. Check out that astonishing difference right through the content below!
Summary of the Basic Accumulation Structure of the Youth Leap Account and Total Benefits Received Upon Reaching 5-Year Maturity
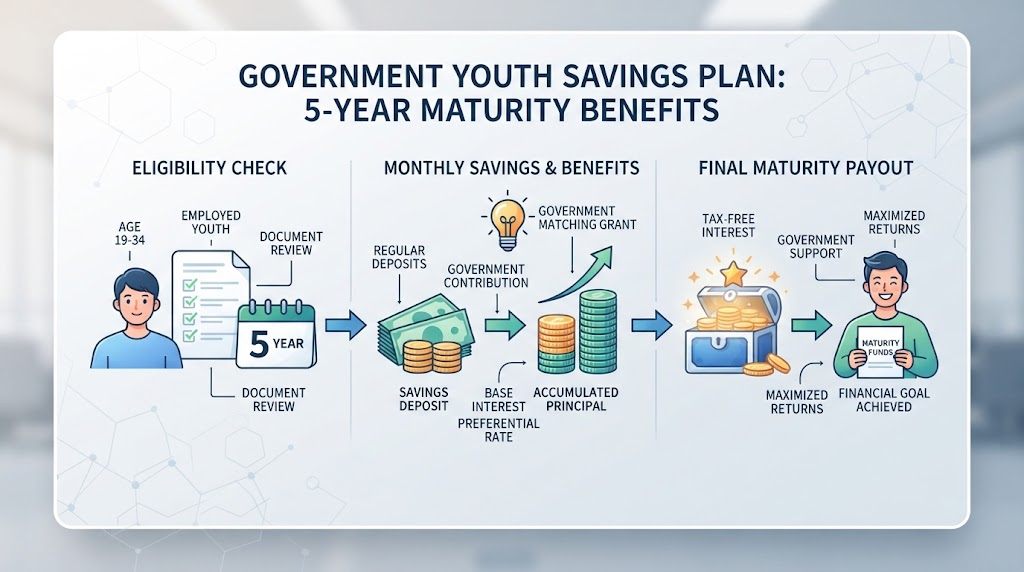
To clearly understand why you must carry the Youth Leap Account all the way to maturity without giving up midway, you must be able to draw an overall picture of how this product is designed in terms of its accumulation structure and how powerful the total benefits returning to you are when reaching the 5-year maturity. What on earth is the reality of that structure and those benefits?
- Basic Accumulation and Operation Structure of the Youth Leap Account 🎯
Subscription and Deposit Method: It is an asset-building support product in the form of a 5-year (60 months) installment savings account where young adults aged 19 to 34 can freely deposit up to a maximum limit of 700,000 won per month.
Public-Private Cooperation Structure: In addition to the principal deposited by the subscriber, it consists of a structure where ‘government contributions’ accumulate together in the savings account every month according to the ratio set by the state for each personal income bracket.
- Summary of 3 Core Benefits Enjoyed Upon Reaching 5-Year Maturity 💰
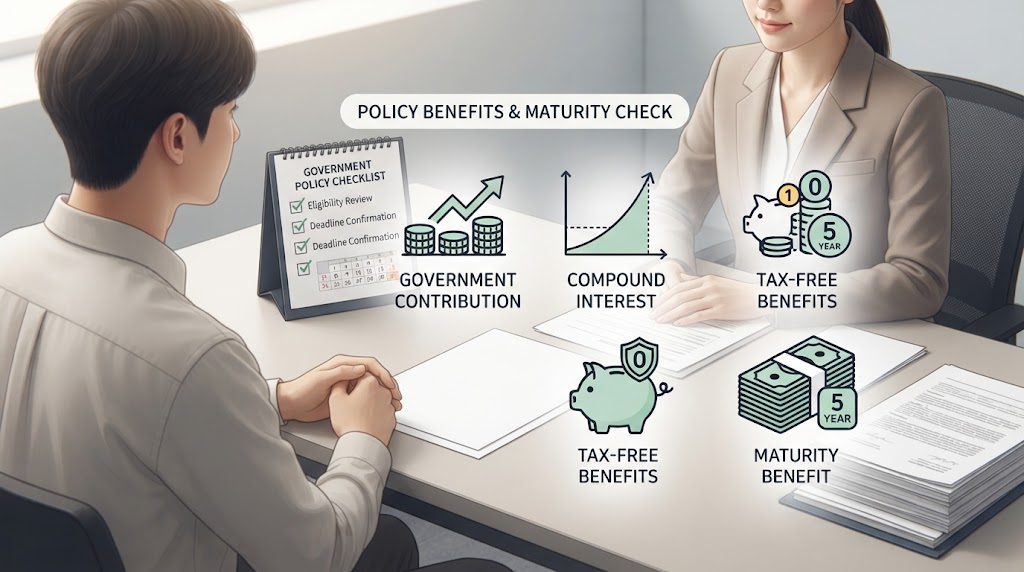
Maximization of Principal and Government Contribution Accumulation: The full amount of government contributions steadily accumulated every month is seamlessly added to the faithfully paid principal deposited by the individual for 5 years, completing a thick seed money that is on a completely different level from saving alone.
Combination of Bank Interest Rates and Interest: If you meet preferential interest rate conditions in addition to the base rate promised at the time of subscription, interest at a level significantly higher than general commercial savings products is applied as compound interest.
Interest Income Tax-Exemption Benefit: The 15.4% interest income tax generated from general financial products is fully exempted, allowing you to take the full final interest amount received upon maturity into your bank account completely without any tax deductions.
- The Power of Explosive Asset Building Brought by Maturity Maintenance 📈
Although difficult to perceive through simple calculation, the final received amount at 5-year maturity combining government contributions, tax-exemption, and interest rates creates a gap of millions of won or more when compared to general savings.
Because the benefits obtainable through maturity maintenance are enormous like this, terminating midway is no different from kicking away the asset-building opportunity given by the state with your own feet.
Then, among the core benefits applied upon maturity maintenance, how specifically do government contributions and the compound interest effect work? We will thoroughly dissect those details in the next chapter!
Core Benefit Analysis ① Applied Upon Maturity Maintenance: Maximum Matching of Government Contributions and Compound Interest Effect
Among the numerous reasons to robustly maintain the Youth Leap Account until maturity, if you were to name the most powerful core weapon, it is undoubtedly the combination of ‘government contributions’ steadily piling up every month and the ‘compound interest effect’ where interest accumulates on top of interest. Shall we carefully examine how these two benefits explosively inflate our assets?
- The Secret of the Government Contribution Matching Structure by Income Bracket 🎯
Depending on the personal income level, the government supports ‘government contributions’ by multiplying a certain ratio to the amount deposited by the subscriber every month.
For example, when depositing a certain amount every month, a higher matching ratio is applied as the income bracket is lower, exerting tremendous additional accumulation effects as if the state is putting wings on your savings.
Because these contributions become entirely your money only when you fulfill the 5-year maturity, maintaining maturity becomes the surest way to make money.
- The Magic of the Compound Interest Effect Where Interest Accumulates on Top of Interest 📈
The Youth Leap Account maximizes the efficiency of long-term savings through a structure where interest is calculated based on the principal and government contributions increased during the subscription period (according to the product-specific interest rate application method).
Thanks to the structure where interest accumulates again on top of accumulated interest as well as the principal as time goes by, the speed at which assets grow noticeably accelerates the longer the savings period is.
The 5-year period is the optimal golden time set to fully enjoy the explosive power of this compound interest effect.
- Synergy Created When Government Contributions and Compound Interest Meet 💡
The difference in the final received amount when quietly saving alone for 5 years versus when compound interest is added to the contributions the state supplements every month widens beyond imagination.
Thanks to national subsidies that are on a completely different dimension from simply receiving a few percent more in interest rates, the merit of maintaining maturity is bound to be overwhelming.
Aside from government contributions and the compound interest effect, there is another core weapon that strongly supports maturity maintenance. It is none other than tax-exemption benefits that save taxes and preferential interest rates! We will completely dissect them in the next chapter!
Core Benefit Analysis ② Applied Upon Maturity Maintenance: Maximization of Interest Income Tax-Exemption and Preferential Interest Rates
In addition to the government contributions and compound interest effect examined earlier, there is another powerful cheat key that maximizes the value of your assets when maintaining the Youth Leap Account until maturity. They are the ‘interest income tax-exemption benefit’ and the ‘preferential interest rates’ of commercial banks. Let’s analyze in detail just how tremendously these two benefits contribute to the maturity received amount.
- 15.4% Full Exemption of Interest Income Tax (Tax-Exemption Benefit) 💰
When you subscribe to a general bank savings product and receive interest at maturity, the state regularly deducts 15.4% (including local income tax) of the interest income as tax. When a large sum of money slips away as tax from hard-earned interest, a sense of dismay naturally arises.
However, for the Youth Leap Account, if you fulfill the 5-year maturity, a ‘tax-exemption benefit’ is applied where not a single penny of tax is imposed on interest income.
Since the money that was about to go out as tax remains intact in your bank account, when calculating the final received amount, the perceived interest difference becomes enormously large compared to general taxable products.
- Maximization of Interest Rates Through Satisfying Preferential Interest Rate Conditions by Bank 📈
Each commercial bank handling the Youth Leap Account presents various preferential interest rate conditions (such as salary transfers, card usage performance, initial transactions, etc.) in addition to the base rate.
If you consistently maintain and satisfy these preferential interest rate conditions over the 5-year period, you can stably be applied a level of interest significantly higher than general deposit and savings products in the market.
Due to the characteristics of long-term products, high interest rates work complexly throughout the entire 5 years, further maximizing interest income.
- The Power of Final Seed Money Completed by Tax-Exemption and Preferential Interest Rates 💡
When pure interest income without tax deductions is added to high preferential interest rates, it is not easy to find a financial product that provides such stable yet high returns during the early-career worker or youth period.
Ultimately, all of these benefits can become entirely yours only through the completion of ‘5-year maturity maintenance’.
Then, just how big of a difference is there specifically in the actual received amount when faithfully maintaining until maturity versus terminating midway? In the next chapter, we will clearly compare it through simulation!
Simulation Comparing Actual Received Amount Upon Early Termination vs. Maturity Maintenance (How Much Difference Will There Be?)
No matter how good the benefits upon maturity maintenance are theoretically, you must directly check with your eyes “how much difference there is in the money actually recorded in your bank account” to completely shake off the temptation of termination. To aid understanding, let’s coldly compare the actual received amounts of early termination and maturity maintenance through a hypothetical simulation.
- Basic Simulation Assumptions (Monthly Deposit Amount and Period) 📊
Deposit Conditions: Assuming a situation of steadily depositing 500,000 won per month for 5 years (60 months).
Applied Interest Rate: Annual 5.0% interest rate and reflection of maximum government contribution matching criteria by income bracket.
Comparison Targets: ① Upon normal 5-year maturity maintenance vs. ② Upon general termination (early termination)
- Simulation Results: Overwhelming Actual Received Amount Upon 5-Year Maturity Maintenance 💰
① Normal 5-Year Maturity Maintenance: The principal deposited by the individual (30 million won), the full amount of government contributions steadily piling up every month, compound interest at an annual 5.0%, and even the 15.4% interest income tax tax-exemption benefit are seamlessly combined, allowing you to grasp a thick final lump sum that surpasses imagination.
② General Termination (Early Termination): On the other hand, if terminated midway due to a simple change of mind or liquidity pressure, **not a single penny of the government contributions** supported by the state so far is received and they are recovered in full. Furthermore, a low early termination interest rate is applied to the interest, and even the 15.4% **interest income tax is deducted as general taxation**, leaving you with only a dismayed amount where slight interest is barely attached to the principal.
- Final Gap and Implications Between the Two Methods 💡
When comparing the final received amounts upon maturity maintenance versus general termination, you can clearly see that a huge monetary gap of millions of won or more occurs.
If you choose termination due to a short-term temptation or momentary liquidity crisis, it leads to a fatal loss where you throw away the state support and the magic of compound interest built up so far with your own hands.
Then, what are the practical tips we must keep in mind to complete the long 5-year journey to the end without getting tired? We will organize them together with a solid concluding remark in the final chapter!
Practical Deposit Maintenance Tips and Conclusion for Robustly Completing Until Maturity
So far, we have thoroughly examined the overwhelming government contributions, compound interest effect, tax-exemption benefits, and the painful losses faced upon early termination that you can enjoy when robustly maintaining the Youth Leap Account until maturity.
For young people shaking while saying, “Even knowing it, the money going out every month is burdensome,” we will wrap up today’s post with practical deposit maintenance tips that can safely complete the 5-year long journey!
- 3 Practical Deposit Maintenance Tips for Completing 5-Year Maturity 💡
First, setting flexible deposits tailored to your income and budget: The Youth Leap Account allows deposits up to a maximum of 700,000 won per month, but you do not necessarily have to fill it to the maximum. Whether it is 400,000 won or 500,000 won per month, steadily continuing with an amount that causes no strain according to your fixed expenses and income is the best way to prevent early termination.
Second, utilizing the ‘deposit suspension’ system during temporary liquidity crunches: As life goes on, there are times when income temporarily halts or large expenses occur, making deposits burdensome for a month or two. At times like this, rather than blindly worrying about termination, wisdom is needed to keep the account safely alive by utilizing deposit suspension through the system.
Third, finding other alternatives first, such as savings-backed loans instead of termination: If you immediately need emergency funds, rather than terminating the Youth Leap Account, consider alternatives of top priority, such as a ‘savings-backed loan’ where you take a low-interest loan from the bank using that account as collateral.
- Conclusion 🌟
The Youth Leap Account, supported actively by the state so that early-career workers and youth can grasp a large sum of money in their hands and design their future, requires a patient time of 5 years, but the reward is powerful enough to change a life.
Rather than voluntarily giving up the chance given by the state due to momentary temptation or short-term financial pressure, we sincerely cheer you on to silently push forward toward completion while recalling the benefits and simulations shared today.
We hope today’s post became a solid lighthouse for your wise asset building. If you have any further questions, please feel free to leave a comment anytime. Have a happy and wealth-building day today!
Korean version: 한국어로 읽기