Introduction: What If Business Income Occurs While Registered as a Dependent?
Have you been enjoying health insurance benefits without the burden of insurance premiums by being registered as a dependent of a family member who is an employee subscriber? At some point, you may have experienced panic upon starting a side job, working as a freelancer, or generating modest rental or business income.
Many people take it lightly, thinking, “Surely I won’t get disqualified as a dependent over this much income?” or conversely, feel excessive anxiety thinking, “Do I automatically get hit with a health insurance fee bomb if even 1 won of business income is generated?” In particular, since the health insurance dependent system strictly applies income and property criteria, if you do not know the exact criteria in advance and cope accordingly, you are bound to be flustered one day when you are suddenly converted to a local subscriber and receive an unexpected health insurance premium notice.
Whether your dependent qualification is maintained depends entirely on “whether or not you have a business registration” and “what the scale of the generated business income is.”
In this post, we will step-by-step examine everything from the core income criteria you must know when business income occurs while registered as a dependent, to maintenance and disqualification conditions based on the presence of business registration, and the limit line that 3.3% freelancer income earners must check. Let’s take a close look together from now on at wise coping methods to safely protect your precious dependent qualifications.
Core Understanding of Business Income Criteria for Health Insurance Dependents
When screening health insurance dependent qualifications, the item that is viewed most stringently while also causing the most confusion is none other than the ‘income criteria’. Among them, unlike earned income or pension income, business income requires even more accurate understanding because the applied criteria differ drastically depending on the form of generation and the presence of business registration.
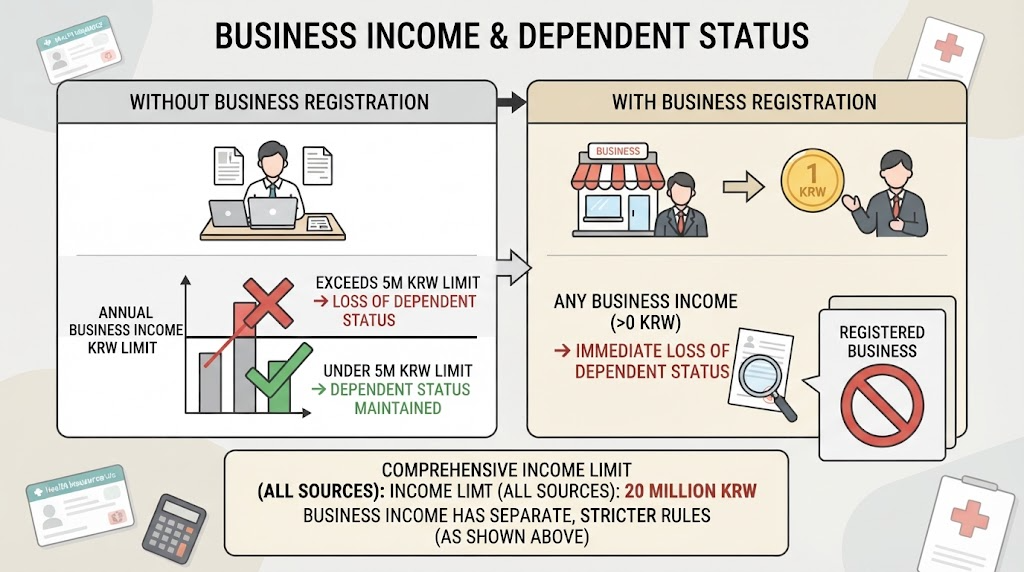
To be recognized as a dependent under the National Health Insurance Act, you must satisfy both income requirements and property requirements. The core of the income requirement is that annual combined income must be below a certain amount. In the case of business income, it must satisfy the general global income (earned, business, property, financial income, etc.) annual combined standard of 20 million won or less, while simultaneously passing the inherent criteria of business income itself.
- When there is no business registration: Business income from freelancers, personal service providers, etc., without business registration must have an annual combined income of 5 million won or less to maintain dependent status. In other words, the moment it exceeds 5 million won per year, you are immediately disqualified as a dependent.
- When there is business registration: When you have business registration and run a business, the criteria become much stricter. If you have a business registration, in principle, if even 1 won of business income occurs (exceeding 0 won in annual business income), you lose your dependent qualification. (However, even if there is a business registration, cases where there is no income due to business closure or where annual business income is 0 won may be exceptionally recognized.)
As such, depending on whether you obtained a business registration certificate while engaging in side jobs or freelance activities, the criteria diverge sharply into whether the ‘5 million won limit line’ is applied or whether ‘not even 1 won of income is allowed.’
Understanding in advance how the income you have earned is classified under tax law and how it will be judged in the Corporation’s screening based on the presence of business registration is the first step to preventing a health insurance fee bomb. In the next section, we will delve into more detail regarding the specific qualification maintenance and disqualification conditions according to the presence of business registration.
Conditions for Maintaining and Disqualifying Dependent Status When Business Income Occurs
As examined earlier, in health insurance dependent qualification screening, completely different standards are applied to business income depending on the ‘presence of business registration.’ Therefore, you must carefully check whether there is a risk of disqualification by accurately cross-referencing the nature of the income you generated and your business registration status.
The specific conditions for maintaining and disqualifying qualifications according to the presence of business registration are clearly divided as follows:
- When there is no business registration (freelancers, personal service providers, etc.): If you earn business income by working in a freelance format without business registration, you can maintain your dependent status if your annual combined business income is 5 million won or less. In other words, if the annual business income amount excluding necessary expenses does not exceed 5 million won, your dependent status is maintained, but the moment it exceeds 5 million won by even 1 won, you are immediately disqualified as a dependent and converted to a local subscriber.
- When there is business registration (sole proprietors, etc.): When you are running a business with a business registration at the National Tax Service, the criteria are very strict. If a business registration exists, in principle, if even 1 won of business income occurs (exceeding 0 won in annual business income), you immediately lose your dependent qualification. If sales occur and income excluding expenses occurs, you become subject to disqualification regardless of the amount. (However, cases where there is a business registration but it is in a suspension or closure state, or where there is no business income at all resulting in an annual income amount of 0 won, may be exceptionally recognized.)
As such, since an extreme difference arises between ‘allowing 5 million won per year’ and ‘not allowing even 1 won’ depending on the presence of a business registration certificate, it is wise to check whether business registration in your name is necessary before starting a minor side job or rental business.
Especially in the case of freelancers, it is easy to confuse tax law treatment and the National Health Insurance Service’s qualification screening criteria because of the income tax withheld every month. In the next section, we will take a deeper look into the 3.3% withholding tax and its impact on health insurance, which freelancers and side-job earners frequently experience.
The Impact of 3.3% Withholding Tax and Health Insurance for Freelancers and Side-Job Earners
For those who work a side job after getting off work while keeping a regular job, or raise their income through freelance activities outside of their main job, the most commonly encountered form of income is none other than 3.3% withholding tax income. Because 3% of business income tax and 0.3% of local income tax are deducted in advance from the amount to be received, tax processing seems neat, but from the perspective of maintaining health insurance dependent status, this 3.3% income acts as a very tricky variable.
Many people let their guard down, thinking, “Since the 3.3% tax was deducted, it will be handled on its own as earned income or freelance income,” but the Corporation strictly screens this income based on National Tax Service global income tax return details.
- 3.3% income of freelancers without business registration: As examined earlier, freelancers who earn business income in the form of 3.3% withholding tax without a business registration must have an annual combined business income of 5 million won or less to maintain dependent status. The 5 million won mentioned here is not total revenue (sales), but the ‘income amount (annual revenue minus necessary expenses)’ standard excluding necessary expenses from total revenue, so you must carefully check based on the amount reflected during the global income tax return.
- Beware of the time lag in Corporation screening reflection: Freelancer income is not reflected in health insurance immediately as it occurs every month; instead, it is reflected at the point in time when the data is handed over to the National Health Insurance Service (typically after the second half of every year) after finishing the global income tax return every May. Because of this, you may face an embarrassing situation where your dependent qualification is suddenly revoked this year or retroactively subjected to health insurance premiums due to income generated last year.
Therefore, if you are a freelancer or side-job earner where 3.3% withheld income occurs, the habit of frequently checking for yourself whether your annual combined net income exceeds the limit line of 5 million won is essential.
To prevent situations where you unknowingly lose your qualification due to the time lag between income changes and Corporation screening, thorough management utilizing your smartphone in daily life must be supported. In the next and final section, we will comprehensively summarize wise coping methods and advance check tips when business income occurs.
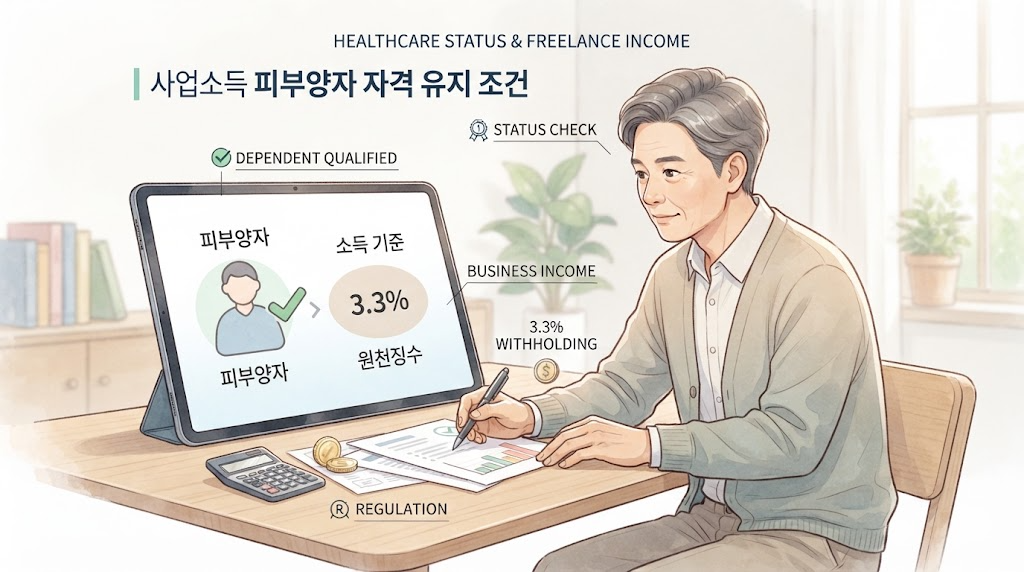
Conclusion: Smart Response and Advance Check Tips When Business Income Occurs
📋 Conclusion: Smart Response and Advance Check Tips When Business Income Occurs
So far, we have thoroughly explored everything from the core income criteria you need to know when business income arises while registered as a dependent, the conditions for maintaining or losing eligibility based on whether you have a business registration (the 5 million won lifeline vs. not even 1 won allowed), to important considerations regarding 3.3% freelance earners and the reporting time gap for comprehensive income tax.
National Health Insurance dependent eligibility often changes unexpectedly while you let your guard down thinking, “Surely I won’t lose eligibility just from earning a little side income?”, leading to a transition to a local subscriber and a massive health insurance premium bomb. However, if you accurately understand today’s criteria and check the nature of your income generation in advance, you can fully prepare for it.
💡 Summary of Today’s Key Points and Final Remarks
- Clearly understand the criteria regarding business registration: Always keep in mind that if you do not have a business registration, your annual combined business income must be 5 million won or less, and if you do have a business registration, you will lose eligibility if your income exceeds 0 won in principle.
- Manage net income for 3.3% freelance income: Managing the 5 million won lifeline strictly based on your annual income amount excluding necessary expenses rather than total revenue is the best defense.
- Check eligibility frequently via the ‘The Health Insurance’ app: Form a habit of easily checking your National Health Insurance eligibility status through the mobile app around annual income tax reporting seasons or whenever your income changes.
We hope you securely protect your precious finances and health this year through thorough advance checks and smart income management!
If today’s post was helpful, please leave a like (❤️), a comment, and add us to your neighbors. We will be back with more useful and informative living information. Thank you!
Recommended Articles to Read Together
- Learn About the Conditions for Exceeding the Property Tax Standard Under Dependent Disqualification Income Criteria
- Check Dependent Disqualification Income Criteria: Dependent Eligibility Maintenance Conditions and Screening Standards
- Carefully Examine Dependent Disqualification Income Criteria: Property and Annual Combined Income Conditions
Korean version: 한국어로 읽기