Introduction: Youth Leap Account, Is It Really a Profitable Deal for Me?
When you faithfully save every month, endure the long period of 5 years, and finally reach maturity, how much money will actually be stamped in your bankbook? The Youth Leap Account, ambitiously introduced by the government to help young people form assets, has been receiving hot interest from countless office workers and youths since its release.
However, since a considerable amount of up to 700,000 won is tied up every month for 5 years, quite a few people have doubts in the middle, thinking, “Is it really worth that much?” or contemplate early termination. If you were only to get back the principal you paid, it would be no different from a regular savings account, but the true charm of the Youth Leap Account lies in the fact that ‘government matching grants’ and ‘tax-free interest income benefits’ are added to produce a synergy effect beyond imagination.
The lump sum you get your hands on when you complete the full 5-year maturity is not just the result of simple savings, but serves as a practical asset-formation opportunity that will become a solid stepping stone for early career workers and youths. Then, let’s carefully dissect from now on the specific structure: exactly how much can be received when paying how much each month, and how my refunds and interest are calculated.
Basic Structure of Refund Calculation: Principal, Government Matching Grant, and Tax Exemption
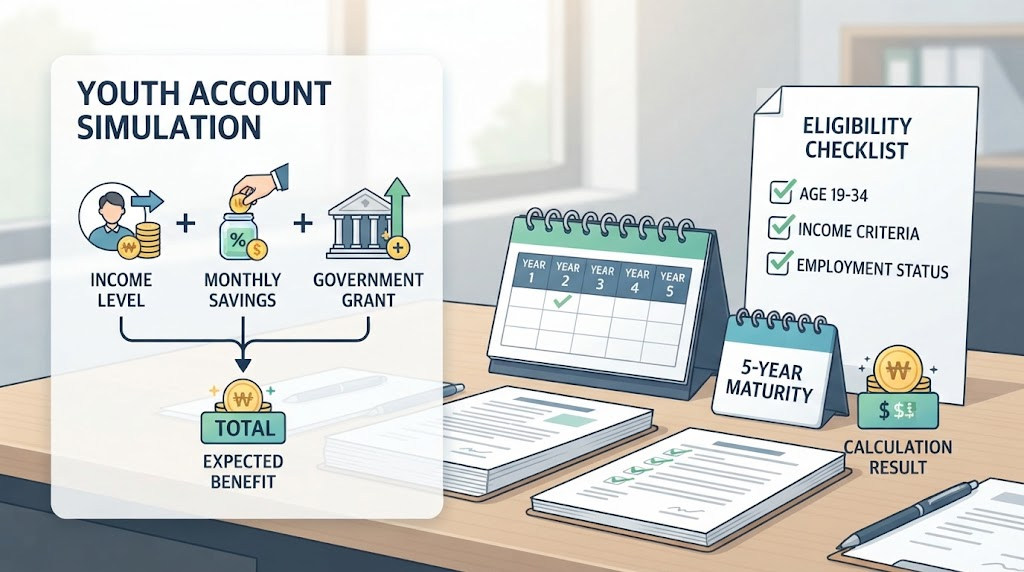
To understand the magical principle of how the Youth Leap Account creates a huge lump sum in 5 years, you must accurately grasp the three-way structure (principal contribution + government matching grant + tax-free interest income) that this product has. How is it different from simply signing up for a bank savings account? Let’s break down the structure one by one.
- Core Components of the Three-Way Structure
Principal contribution: The principal amount that the subscriber freely deposits every month (from a minimum of 10,000 won to a maximum of 700,000 won).
Government matching grant: A subsidy where the state adds a certain ratio to the monthly deposit according to the subscriber’s income level. Since it is essentially the government matching subsidies to the money you pay, it becomes a tremendous merit in terms of yield.
Tax-free interest income benefit: By receiving a 100% exemption from the 15.4% interest income tax attached to general savings products, the interest received upon maturity goes entirely into your pocket.
- Government Matching Grant Structure by Income Bracket
Government matching grants are differentially paid according to the subscriber’s personal income level. The lower the income, the higher the matching ratio and limit applied, allowing you to receive generous support.
The lower the total salary: The government matching ratio increases, allowing more matching grants to accumulate in the account according to the limit for each bracket (e.g., limits based on monthly deposits of 400,000 won or 500,000 won).
The exact standard amount for each income bracket and the matching limit according to the subscriber’s deposit amount are finalized based on income proof at the time of subscription, and are steadily accumulated every month for 5 years.
Because these four axes—’principal contributed by me + government matching grants added by the state + bank interest + tax exemption (tax-free)’—mesh together, you can expect a high actual yield that cannot be compared with general savings accounts at regular commercial banks.
Then, when you deposit a certain amount every month, exactly how much will you get your hands on after 5 years? Let’s compare specific calculation points in the next part.
Practical Refund Calculation Points: Simulation by Monthly Deposit and Income Bracket
When contemplating joining the Youth Leap Account, the question you’ll be most curious about is undoubtedly, “How much will I actually get in my hands after 5 years when depositing a certain amount every month?” Let’s look into the specific simulation calculation points according to the government matching grant limit by income bracket and the choice of monthly deposit.
- Government Matching Grant Structure by Monthly Deposit and Income Bracket
For the Youth Leap Account, the payment limit and matching ratio of the contribution added by the government every month are applied differently depending on the subscriber’s personal income (based on total salary).
The lower the total salary: The government matching ratio increases, generously providing the limit of contributions that can accumulate to the maximum in proportion to the amount deposited by the individual every month.
Utilization of deposit limit: Individuals can freely deposit up to 700,000 won per month, but government matching grants are paid within the matching limit recognized for each income bracket. For example, in certain income brackets, the maximum matching ratio is applied only up to monthly deposit amounts of 400,000 won or 500,000 won.
- Simulation Comparison of Expected Payout at 5-Year Maturity
Depending on the amount deposited monthly by the actual subscriber and income conditions, the total amount received after 5 years (60 months) is calculated in the following structure.
Scenario A (When depositing 400,000 won monthly):
Total principal contributed for 5 years: 400,000 won × 60 months = 24 million won
Sum of government matching grant and interest: The government matching grant matched by income bracket and 5-year maturity interest (with tax-free interest income applied) are added.
Expected total payout: A lump sum of roughly 28 million won to 29 million won is formed.
Scenario B (When depositing the maximum 700,000 won monthly):
Total principal contributed for 5 years: 700,000 won × 60 months = 42 million won
Sum of government matching grant and interest: The maximum matching grant, 5-year compounding effect, and 15.4% tax exemption benefit are combined to the maximum.
Expected total payout: It returns as a huge asset of around 50 million won (or more).
💡 Points to Remember When Calculating
The applied interest rate moves in the form of a 3-year fixed rate + 2-year variable rate after subscription, and the final interest scale varies depending on how much you satisfy the preferential interest rate conditions of each handling bank.
In addition to running a simple calculator, the matching limit according to your exact income level is finalized based on income proof at the time of subscription, so it is most accurate to refer to the Korea Inclusive Finance Agency guidelines together.
Have you got a sense of what amount you should use to make your 5-year plan according to your income and financial capacity? In the next part, based on these calculations, we will examine the opportunity costs and risks that must be checked when weighing practical benefits upon subscription.
Examining Practical Benefits ①: Checking Opportunity Cost and Early Termination Risk
Although the Youth Leap Account offers massive benefits such as government matching grants and tax-free interest income, you must carefully weigh the opportunity cost and early termination risk before subscribing, given that funds are tied up for a long contract period of 5 years.
- Countermeasures for Emergency Fund Demands That May Arise During the 5-Year Maturity Period
For early career workers or young office workers, situations requiring a large sum of money—such as marriage, independence (residential relocation), job change, or vehicle purchase—can arise at any time during the 5-year span.
Since depositing an amount reaching up to 700,000 won every month can make living funds tight and create an emergency fund gap, you must objectively check your savings capacity compared to your monthly income.
Countermeasure: It is safe to proceed with subscription after securing a separate emergency fund account (e.g., 3 to 6 months’ worth of living expenses) that can be withdrawn at any time, in addition to your Youth Leap Account deposits.
- Fatal Losses Occurring Upon Early Termination (The Reality of Opportunity Cost)
If you fail to fulfill the 5-year maturity due to unavoidable circumstances and terminate early, there is a structural risk where most of the benefits accumulated up to that point disappear.
Recovery of government matching grants: Government matching grants accumulated with state support are not paid in full and are recovered.
Disappearance of tax-free benefits: A 15.4% tax is levied on interest income just like a regular taxable product, making it no different from standard savings products.
Result: You may end up with a lower return than if you had subscribed to a regular savings account, so rather than having a complacent mindset of “Let’s just sign up first,” you must thoroughly verify whether your cash flow can support steady deposits for 5 years.
💡 Practical Checkpoints
Work backward to see if you can comfortably sustain your monthly deposit amount (e.g., 400,000 won vs. 700,000 won) for 5 years based on your current fixed expenses and income flow.
Even if there are partial provisions for reducing the amount or deferring deposits in the middle, it is most advantageous to maintain the initially planned amount until the end as much as possible.
Then, when compared to other youth policy financial products besides the Youth Leap Account, which product best fits your asset formation goals? In the next part, let’s check the final practical benefits through a comparison with other products.
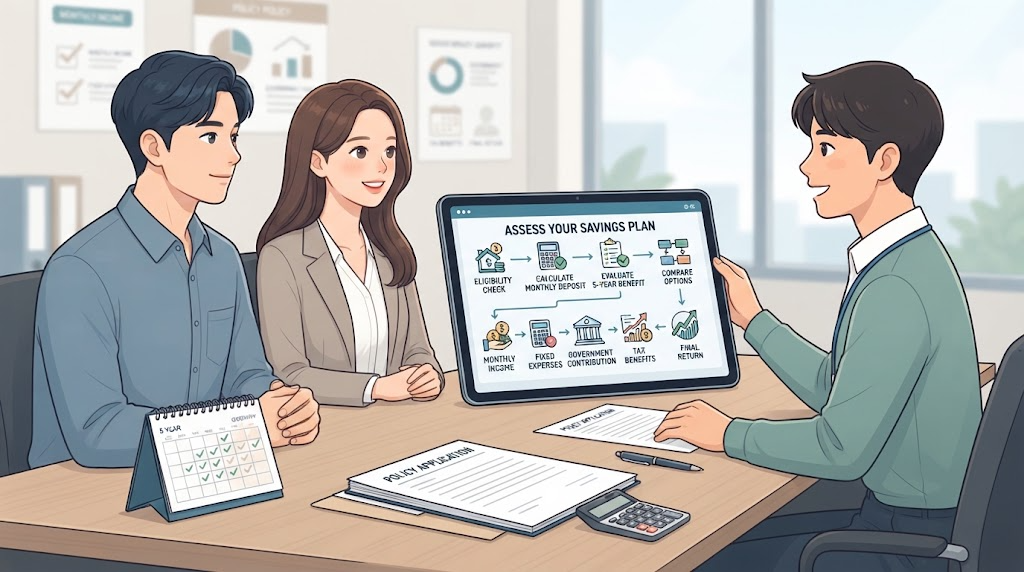
Examining Practical Benefits ②: Comparison with Other Financial Products (Youth Housing Dream Subscription Savings, etc.)
Even if the Youth Leap Account provides decent government matching grants and tax-free benefits every month, this is not the only government policy-oriented product for youths. When compared with other financial products, such as the ‘Youth Housing Dream Subscription Savings Account’, which is called a representative competing product and the ultimate king of housing support, you must weigh which product better fits your asset formation goals.
- Comparison Points: Youth Leap Account vs. Youth Housing Dream Subscription Savings Account
Strengths of the Youth Leap Account (Short- and Medium-Term Asset Formation):
It is specialized in reliably creating a lump sum (around 50 million won) over a relatively short period of 5 years.
Government matching grants for monthly deposits and tax-free interest income benefits are powerful, making it advantageous in terms of pure asset growth.
Strengths of the Youth Housing Dream Subscription Savings Account (Housing and Subscription Linkage):
It is advantageous for youths whose top priority is purchasing a home (housing subscription).
Since it is linked to the ‘Youth Housing Dream Loan’, which supports up to 80% of the sale price at a low interest rate in the 2% range upon winning a subscription, you can simultaneously solve seed money generation and housing stability. (※ However, due to the nature of the subscription savings account, funds are tied up until long-term maintenance and winning a subscription, or it is concentrated on subscription functions.)
- Wise Selection Criteria According to Your Asset Goals
If marriage, independence, or gathering seed money is urgent: It is advantageous to take the Youth Leap Account as your main choice, which hands you reliable cash-like assets at a 5-year maturity.
If future home purchase (subscription) is life’s top priority: You should place housing-related youth accounts with powerful subscription functions and loan linkage benefits as your top priority.
Possibility of parallel subscription: If you meet the income and subscription requirements, it is also good to check through each bank counter or related institution guidelines whether you can split your portfolio and subscribe according to the nature of the two products (asset formation vs. housing subscription).
If you have carefully examined the structure of the Youth Leap Account, refund calculations, and comparisons with other products, now is the time to make your final decision. Finally, let’s summarize how to make a wise subscription decision.
Continue checking the following contents:
How to make a wise subscription decision after finishing Youth Leap Account refund calculations
How to easily check maturity refunds using the Korea Inclusive Finance Agency app
Things to keep in mind and disadvantages when early termination of the Youth Leap Account
Conclusion: How to Make a Wise Subscription Decision After Finishing Refund Calculations
So far, we have carefully examined the refund calculation structure of the Youth Leap Account, simulations by monthly deposit amount, practical benefits that must be weighed before joining, and comparisons with other products. When you think of the solid lump sum that will be stamped in your bankbook when you faithfully save every month and complete the long journey of 5 years, doesn’t your heart already feel proud?
However, since the period of 5 years is not short, you must never experience failure due to joining with an excessive amount and giving up halfway or facing unexpected expenses. Finally, we summarize the key points to remember to make a wise subscription decision.
- Utilize Easy Expected Payout Inquiry Tips Through the Korea Inclusive Finance Agency and Bank Apps
If you are hesitating to subscribe, rather than worrying blindly, directly simulate the government matching grants and maturity payouts expected based on your income right now through your transaction bank app or the Korea Inclusive Finance Agency official inquiry service.
Just checking the specific numbers with your eyes provides great motivation for setting future savings plans.
- Completing According to Your Financial Situation Takes Top Priority Over Excessive Deposits
Rather than the pressure of having to unconditionally fill the maximum limit of 700,000 won every month, it is much wiser to accurately reflect your monthly income and fixed expenses to set an amount that you can steadily deposit for 5 years without a single cancellation (e.g., 400,000 won or 500,000 won).
Do not forget that government matching grants and tax-free benefits finally become yours only when you fully complete the 5-year maturity.
💡 Final Advice
The Youth Leap Account is not just a bank savings product, but a precious opportunity where the state supports the asset formation of youths working diligently together. Based on the refund calculation criteria and practical benefit check contents we looked at today, we sincerely cheer for you to make the best choice most suited to your economic situation and be reborn as a solid asset holder 5 years later!
We hope today’s posting became a clear compass for your smart asset management, and we will return with more substantial and practical living financial information. Thank you!
Continue checking the following contents:
How to easily check maturity refunds using the Korea Inclusive Finance Agency app
Things to keep in mind and disadvantages when early termination of the Youth Leap Account
Practical tips for satisfying preferential interest rate conditions of the Youth Leap Account
Korean version: 한국어로 읽기