Introduction: Youth Leap Account, How Much Can You Really Receive If Maintained Until Maturity?
When you faithfully save every month, endure the long period of 5 years, and finally reach maturity, how much money will actually be stamped in your bankbook? The Youth Leap Account, ambitiously launched by the government to help young people form assets, has been receiving hot interest from countless office workers and youths since its release.
However, since a considerable amount of up to 700,000 won is tied up every month for 5 years, quite a few people have doubts in the middle, thinking, “Is it really worth that much?” or contemplate early termination. If you were only to get back the principal you paid, it would be no different from a regular savings account, but the true charm of the Youth Leap Account lies in the fact that ‘government matching grants’ and ‘tax-free interest income benefits’ are added to produce a synergy effect beyond imagination.
The lump sum you get your hands on when you complete the full 5-year maturity is not just the result of simple savings, but serves as a practical asset-formation opportunity that will become a solid stepping stone for early career workers and youths. Then, let’s carefully dissect from now on the specific structure: exactly how much can be received when paying how much each month, and how my refunds and interest are calculated.
Continue checking the following contents:
Compare expected maturity payout amounts by monthly deposit amount for the Youth Leap Account
Learn about government matching grant ratios and standards by income bracket
How to easily check maturity refunds using the Korea Inclusive Finance Agency app
Understanding Core Concepts: Structure of the Youth Leap Account and Subsidy Principles
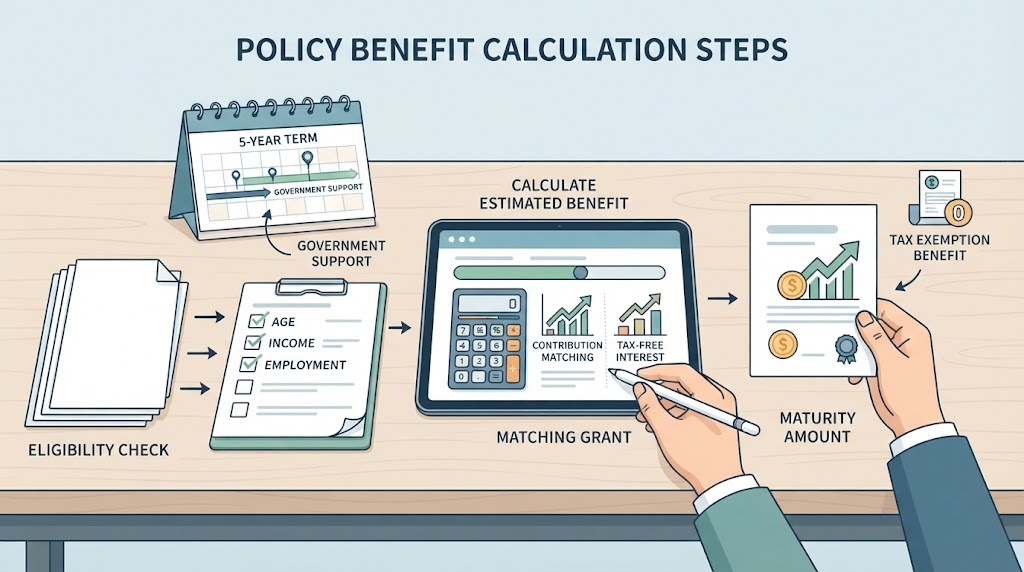
To understand the magical principle of how the Youth Leap Account creates a huge lump sum in 5 years, you must accurately grasp the three-way structure (principal contribution + government matching grant + tax-free interest income) that this product has. How is it different from simply signing up for a bank savings account? Let’s break down the structure one by one.
- Core Components of the Three-Way Structure
Principal contribution: The principal amount that the subscriber freely deposits every month (from a minimum of 10,000 won to a maximum of 700,000 won).
Government matching grant: A subsidy where the state adds a certain ratio to the monthly deposit according to the subscriber’s income level. Since it is essentially the government matching subsidies to the money you pay, it becomes a tremendous merit in terms of yield.
Tax-free interest income benefit: By receiving a 100% exemption from the 15.4% interest income tax attached to general savings products, the interest received upon maturity goes entirely into your pocket.
- Income and Asset Criteria Matching Structure
Government matching grants are differentially paid according to the subscriber’s personal income level. The lower the income, the higher the matching ratio and limit applied, allowing you to receive generous support.
The lower the total salary: The government matching ratio increases, allowing more matching grants to accumulate in the account according to the limit for each bracket (e.g., limits based on monthly deposits of 400,000 won or 500,000 won).
The exact standard amount for each income bracket and the matching limit according to the subscriber’s deposit amount are finalized based on income proof at the time of subscription, and are steadily accumulated every month for 5 years.
Because these four axes—’principal contributed by me + government matching grants added by the state + bank interest + tax exemption (tax-free)’—mesh together, you can expect a high actual yield that cannot be compared with general savings accounts at regular commercial banks.
Then, when you deposit a certain amount every month, exactly how much will you get your hands on after 5 years? Let’s compare specific amounts in the next part.
Continue checking the following contents:
Calculate total payout amount upon maturity by monthly deposit amount
Experience the amount saved through tax-free interest income benefits
How to easily check maturity refunds using the Korea Inclusive Finance Agency app
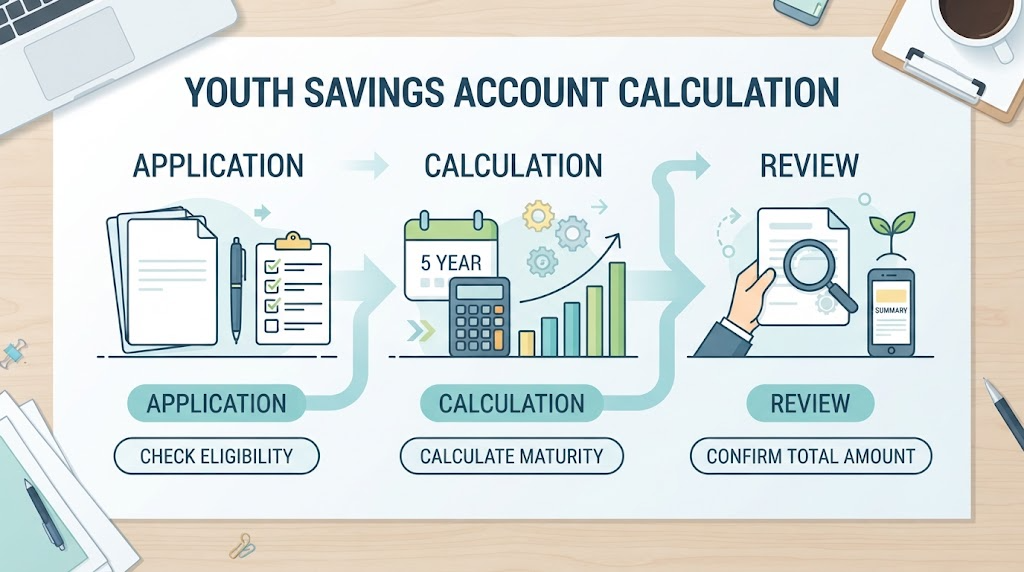
Practical Calculation Method ①: Calculating Total Payout at Maturity by My Monthly Deposit Amount
If you have understood the structure of the Youth Leap Account, now it is time to calculate the maturity payout that will actually be stamped in your bankbook, which you will be most curious about. Let’s check through specific scenarios how the size of the lump sum you get your hands on after 5 years changes depending on how much you deposit every month.
- Comparison of Expected Maturity Amount According to Monthly Deposit Selection
For the Youth Leap Account, you can freely choose the deposit amount between 10,000 won and 700,000 won every month. (※ There may be differences depending on bank situations or individual income conditions, but let’s look at it based on the representative amount ranges most frequently chosen.)
When depositing 400,000 won monthly:
The principal saved by myself over 5 years (60 months) totals 24 million won. When government matching grants by income bracket and interest (with tax exemption applied) are added here, the payout amount at maturity swells into a lump sum of roughly 28 million won to 29 million won.
When depositing 700,000 won (maximum) monthly:
Over 5 years, the total principal contributed alone reaches 42 million won. If you receive the maximum matching grants provided by the government, the compounding effect, and the 15.4% interest income tax exemption benefit to the fullest, the total payout amount at maturity will return as a tremendous asset of around 50 million won (or more).
- Interest Rate Application Method and the Magic of Interest
The Youth Leap Account adopts a structure where a fixed interest rate is applied for the first 3 years after subscription, followed by a variable interest rate for the remaining 2 years.
If you maximize preferential interest rates (such as income conditions, card performance, and marketing consent) on top of the recent base rates of commercial banks, you can receive a high interest rate reaching the 5% to 6% range per year.
In particular, while 15.4% is deducted as tax from interest in regular savings accounts, this product applies tax-free interest income, allowing you to bring the calculated interest entirely into your bankbook without losing a single penny. This is the core secret to maximizing the maturity payout amount.
Then, exactly how much government matching grants and tax-saving benefits will you receive under your income conditions? In the next part, let’s look closer at the tax-free benefits and refund calculation points.
Continue checking the following contents:
Experience the amount saved through tax-free interest income benefits
How to easily check maturity refunds using the Korea Inclusive Finance Agency app
Check things to keep in mind when early termination of the Youth Leap Account
Practical Calculation Method ②: Tax-Free Benefits and Low-Income Refund Calculation Points
Another powerful weapon that maximizes the maturity payout amount of the Youth Leap Account is the ‘tax-free interest income’ and ‘additional refund (matching grant)’ benefits for low-income earners. In addition to the principal and basic interest, let’s point out the calculation points on how this part protects your assets.
- 15.4% Interest Income Tax Exemption (Power of Tax-Free Benefits)
If you sign up for a general bank savings or deposit account, 15.4% (14% income tax + 1.4% local income tax) of the interest you earned is withheld as tax.
For example, assuming that the total interest accumulated over 5 years is 3 million won, with a general taxable product, about 460,000 won would be deducted as tax.
However, since the Youth Leap Account applies tax exemption to the entire amount of interest income if the requirements are met, you can receive 3 million won of interest entirely into your bankbook without tax deduction. The longer the long-term product of 5 years, the larger the scale of interest, so the tax-saving effect becomes bigger than imagination.
- Additional Support Points for Low-Income Youths
For low-income youths below a certain income standard, not only is the government matching grant ratio set higher, but thick government support is concentrated during the product subscription period.
When the compounding effect is added to the government matching grant itself and preferential interest rate conditions according to income brackets are intertwined, the actual refund and profit scale are further maximized.
Then, where exactly can you check your current deposit status and expected refund at this very moment? Let’s find out about the easy inquiry method in detail in the next part.
Continue checking the following contents:
How to easily check maturity refunds using the Korea Inclusive Finance Agency app
Check expected payout amount in the Youth Leap Account handling bank app
Things to keep in mind when early termination of the Youth Leap Account
Inquiry Guide: Easily Checking Expected Maturity Payouts via Korea Inclusive Finance Agency and Bank Apps
After joining the Youth Leap Account, you naturally begin to wonder, “How much money have I paid so far, and how much government matching grant has accumulated?”, and “Exactly how much will I receive upon maturity?” Without having to calculate complex formulas yourself, we will introduce easy inquiry tips where you can check your account’s expected payout amount and refund in real time with just a few touches on your smartphone.
- Utilizing the Korea Inclusive Finance Agency ‘Seo-min-geum-yung-won’ App and Official Inquiry Service
The government matching grant payment history and total accumulation status, which are core to the Youth Leap Account, are managed most accurately through the Korea Inclusive Finance Agency.
By using the Korea Inclusive Finance Agency official website or related integrated inquiry services, you can grasp at a glance the scale of government matching grants matched against the principal paid to date and the expected maturity refund in the future.
- Real-Time Inquiry in Each Handling Bank App
Since the Youth Leap Account is joined and managed through commercial bank apps such as Kookmin, Shinhan, Woori, Hana, and Nonghyup, accessing the banking application you currently trade with is the fastest and easiest.
Inquiry path: Run bank app > [Product/Account Inquiry] > Access [Youth Leap Account] detail menu
Checkable items:
This month’s deposit status and cumulative principal paid
Total amount of government matching grants accumulated so far
Applied interest rate (base rate + preferential rate)
Expected maturity payout amount and refund calculated based on the current point in time
💡 Smart Inquiry Tip
Even if you are busy with monthly rent or living expense expenditures, check your account status through the bank app once every quarter (or every half year). Since you can grasp fluctuations in matching grants due to income re-examinations or satisfaction of preferential rate conditions in real time, it is very useful for asset management.
To make a lump sum without wavering over the long period of 5 years, getting motivated by visually checking the amount growing little by little is very important. Finally, let’s summarize the points you must remember to complete the race until maturity.
Continue checking the following contents:
Disadvantages and things to keep in mind when early termination of the Youth Leap Account
Practical tips for satisfying preferential interest rate conditions of the Youth Leap Account
Learn about wealth management strategies for utilizing lump sum funds after maturity
Conclusion: Tips to Prevent Early Termination and Complete the Full Term
We have covered everything from how to calculate the Youth Leap Account refund to tips for checking the maturity payout amount. When you think about the substantial lump sum that will hit your bank account after faithfully saving every month and completing the long 5-year journey, doesn’t it already give you peace of mind?
However, since a 5-year period is not short, moments may arise where you are tempted to terminate the account early due to unexpected expenses or a sudden need for a large sum of money. To help you safely complete the full term until maturity without a hitch, here are some essential tips to keep in mind.
- Remember the massive benefits you must forfeit upon early termination
If you terminate the account early, all the government contribution subsidies you received from the state will be fully retrieved.
In addition, the crucial tax-exemption benefit on interest income will also disappear, and standard taxation rules will apply, making the final amount you actually receive much smaller than expected. Whenever you feel tempted to waver, keep this loss in mind to steady your resolve!
- Set up automatic transfers and separate your emergency fund
It is recommended to set up an automatic transfer so that your Youth Leap Account contribution is automatically deducted on your monthly payday, and to thoroughly separate your living expense account from your savings account.
By setting aside a separate emergency fund for sudden expenses (e.g., 3 to 6 months’ worth of living expenses), you can get through crises without having to break your account, drastically lowering the probability of early termination.
💡 Final Advice
The Youth Leap Account is not just a regular savings product; it is a precious opportunity where the government joins hands to cheer for and support the better future and asset building of young people. Using today’s calculation methods and inquiry tips as a reference, we hope you will visualize your wonderful self 5 years from now while watching your assets grow every month!
We hope today’s post served as a reliable compass for your smart financial management, and we will be back soon with more enriching and practical lifestyle finance information. Thank you!
Korean version: 한국어로 읽기