Introduction: Preferential Savings Products That SME Employees Must Pay Attention To
Amidst a challenging economic climate where we work hard every month to save our salaries, soaring prices and housing costs make goals like buying a home or building a lump sum always feel distant. Especially for young adults and workers employed by small and medium-sized enterprises (SMEs), you may have felt a sense of regret regarding relatively scarce asset-building opportunities. Although numerous installment savings products are available on the market, did you know that there are ‘preferential savings products’ specially designed solely for SME employees?
Compared to ordinary installment savings from general commercial banks, SME employee preferential savings products are truly hidden gem systems where the state and the financial sector join forces to offer extraordinary benefits. Looking at the immediate benefits right now, they might seem no different from regular savings, but the final outcome you hold in your hands at maturity is completely different.
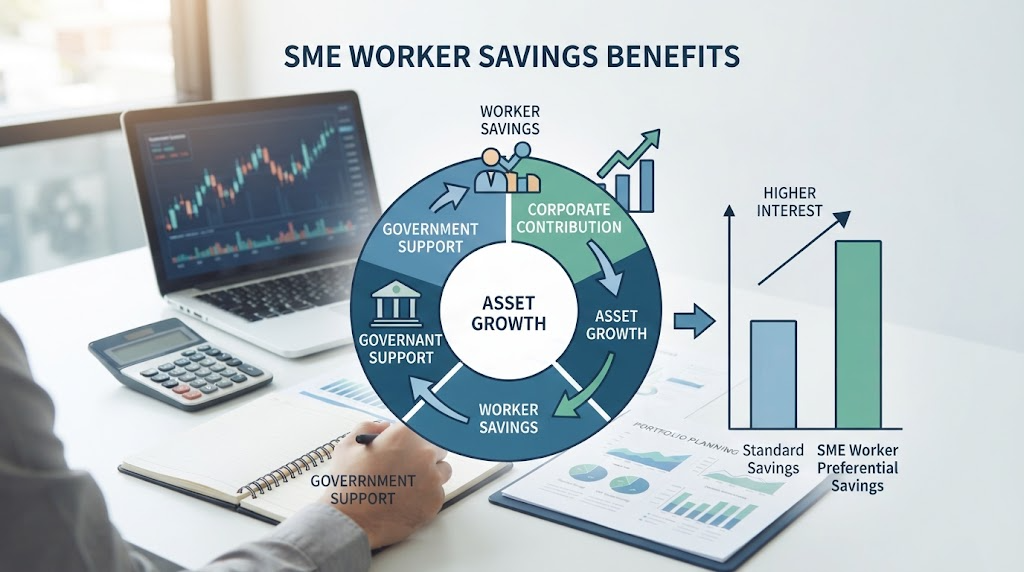
Stark difference from ordinary savings: While ordinary commercial savings have no additional financial resources or subsidies on top of the base interest rate, SME employee preferential savings combine government support, joint accumulation with the company, and the bank’s high-interest preferential benefits to create an exceptional pace of asset building.
Two birds with one stone—long-term retention and asset building: Designed as a win-win structure that provides workers with the opportunity to build a lump sum and induces companies to retain talented employees over the long term, it serves as a reliable source of motivation for work life.
Can you and your company also enjoy these benefits? Since it is not a product anyone can just sign up for, carefully examining the precise eligibility requirements and benefit structure is essential.
From the concept of this preferential savings product that SME employees should never miss, to eligibility and bank-by-bank interest rate comparisons, we will examine everything in detail starting from the next section.
What is ‘SME Employee Preferential Savings’? (Core Concept and Support Purpose)
The name ‘SME Employee Preferential Savings’ might sound a bit unfamiliar to you. This product is a win-win financial product created through a joint effort by the government, the financial sector, and SMEs to narrow the wage gap between large corporations and SMEs, encourage long-term retention of SME workers, and support stable asset formation.
While general commercial bank savings products have a structure where individuals save solely within their own income, this preferential savings features special support mechanisms added directly to its structure. Looking at the core concept and purpose of support, it is as follows.
- Multi-party accumulation and support structure
Not only does the worker themselves deposit a certain amount every month, but subsidies supported by the company (employer) or policy support from the government are complexly linked to create an incomparable high-yield effect and acceleration in gathering lump sums compared to regular savings.
- Win-win for relieving SME manpower shortages and improving worker welfare
From the company’s perspective, it serves as a powerful incentive for talented personnel to work with peace of mind over the long term, and from the worker’s perspective, you can enjoy a dual benefit of increasing actual income through market-leading interest rate benefits and subsidies.
- Decisive difference from ordinary savings
While ordinary savings only pay out the principal you deposited plus bank interest (after income tax deduction) at maturity, SME employee preferential savings add company contribution support or extraordinary preferential interest rates so that the total amount received at maturity shows an unimaginable difference.
In other words, you can understand it as a system where the state and companies together prepare a solid stepping stone so that hardworking SME employees can dream bigger and grow their assets.
Then, precisely which workers and companies can become the protagonists of this wonderful benefit? In the next section, we will examine eligibility and qualification requirements in detail.
Complete Guide to Eligibility and Qualification Requirements
No matter how extraordinary the benefits of ‘SME Employee Preferential Savings’ may be, verifying whether you are included in the eligible targets is the top priority. This product sets clear worker and corporate requirements tailored to the purpose of supporting asset formation for SME workers.
We completely organize the core requirements regarding who can sign up.
- Worker’s own requirements (mandatory check points)
Period and type of employment: Targets full-time workers (or employment types meeting requirements) who have been employed for a certain period or longer in a targeted SME.
Income criteria: Due to the nature of government-supported or policy-linked products, personal income criteria (e.g., previous year’s income criteria, etc.) may apply, so you must check your annual salary or comprehensive income level in advance.
- Requirements for the company you are employed by (eligible target companies)
SME scope: Must correspond to an SME pursuant to the 「Framework Act on Small and Medium Enterprises」. Large corporations and public institutions are excluded in principle, and certain industries (such as entertainment bar businesses and other policy-restricted industries) may be excluded from eligibility.
Company’s willingness to participate: Since this product often involves companies and workers being linked together or company matching support accompanying it, whether your current company can participate as a partner company for the product is also a crucial variable.
- Useful tips to easily check if you are eligible
It is not easy to figure out all the industry codes or detailed requirements of a company on your own. The most accurate and fastest method is to check whether you are eligible based on your current business registration number through the customer center or branch of a handling bank, or via a dedicated platform of a related public institution (such as the Korea SMEs and Startups Agency).
If you have carefully checked whether you meet the qualification requirements, next comes the time to compare the most important aspect: ‘which bank offers how much interest rate benefit’. In the next section, we will take a detailed look at the interest rate support benefits by bank.
Comparison of Interest Rate Support Benefits and Preferential Interest Rate Conditions by Bank
Once you have checked your eligibility and qualification requirements, it is time to look into the most practical matter: ‘which bank offers how much more advantageous interest rate benefits’. SME employee preferential savings are being participated in by major commercial banks keeping pace with government policies, putting forward interest rates significantly higher than ordinary installment savings and various preferential conditions.
Let’s compare what differences exist in the benefit structures and preferential interest rate conditions provided by each bank.
- 1. Characteristics of base interest rates and preferential benefits by major commercial banks
- Major handling banks such as Industrial Bank of Korea (IBK), Woori Bank, and Shinhan Bank: Through dedicated SME employee preferential savings products, they offer attractive interest rates that far exceed the upper limit of ordinary commercial installment savings products.
- Base interest rate + additional preferential interest rate structure: In addition to the base interest rate provided by the bank itself, it is designed in a form where additional preferential interest rates are added depending on the worker’s transaction performance or policy-linked conditions.
- 2. Core conditions to win additional preferential interest rates
- Automatic transfer and salary transfer performance: Preferential interest rates are basically attached if your salary is transferred to the corresponding bank account or if installment savings deposits are made via automatic transfer on a designated date every month.
- Card usage performance or first-time customer: You can secure additional interest rate benefits if you have a certain amount or more of usage performance with the bank’s credit/check cards or if you are a new customer trading with the bank for the first time.
- Policy-linked conditions: Depending on whether there is a link with the SME employee support program, additional interest rate or fee waiver benefits may be applied differently by bank.
| Category | General Commercial Savings | SME Employee Preferential Savings |
|---|---|---|
| Interest Rate Level | General market interest rates applied | Base interest rate + combined policy preferential interest rates |
| Preferential Conditions | Focus on simple card performance and automatic transfers | Abundant additional benefits such as salary transfer and employment linkage |
| Actual Yield | Average level | Maximized through high interest rates + corporate/policy support |
- 3. Points to definitely consider when choosing a bank
- Rather than blindly signing up just by looking at the highest interest rate figure, you must carefully consider whether it is a bank you usually use as your main financial institution, or whether you can fulfill the salary transfer or card performance conditions without unreasonable difficulty. This is because if you fail to meet the preferential conditions and miss the highest interest rate, another bank might actually be more advantageous.
Once you have chosen the bank that best fits your primary banking tendencies, let’s look into what procedures you need to go through to actually sign up. In the next section, we will take a detailed look at the application methods and required submission documents.
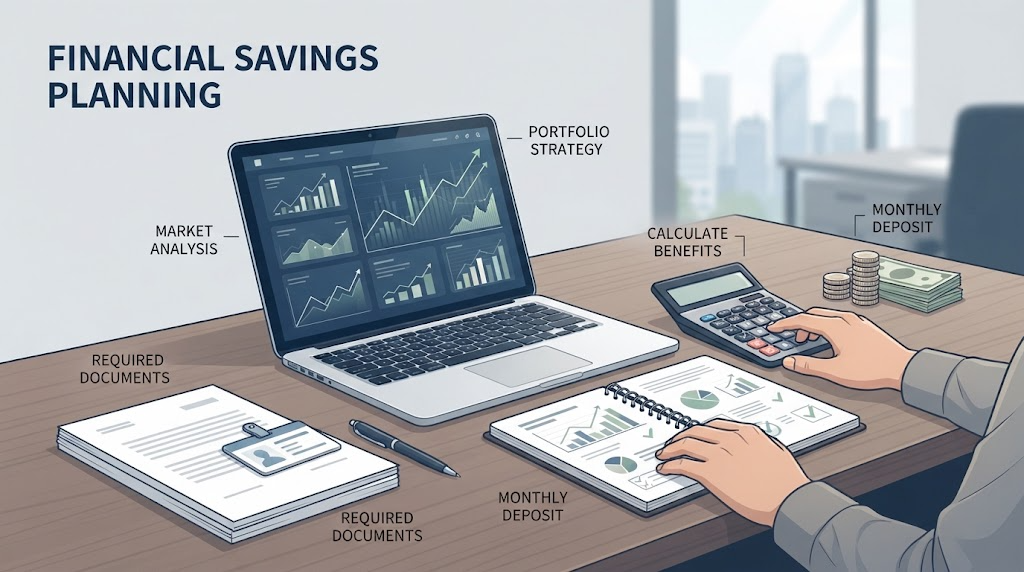
Guide to Application Methods and Required Submission Documents
If you have chosen the most advantageous bank for yourself, it is now time to formally sign up for the product. Unlike general free installment savings, SME employee preferential savings require verification of the company and employment status, so you must carefully prepare the application method and required submission documents in advance to avoid the hassle of making a second trip.
Check the application channels and essential documents for smooth subscription.
- Special Preferential Savings Application Channels
Commercial bank mobile app (App): You can easily apply non-face-to-face by accessing the smart banking app of commercial banks handling the product, such as Industrial Bank of Korea (IBK), Woori Bank, and Shinhan Bank, through the ‘SME Employee Preferential Savings > Product Subscription’ menu. (However, non-face-to-face authentication may vary depending on whether the company is linked.)
Offline branch visit application: If document submission or eligibility verification is not smooth through the app, you can visit an offline branch of the bank in person with your ID and supporting documents to sign up safely under the guidance of a bank teller (staff).
- Essential Submission Document Guide by Situation
To prove employment requirements and income criteria, the following official documents are mainly required. It is recommended to have them issued in advance.
Worker’s own identification documents:
ID card (Resident Registration Card, driver’s license, etc.)
Resident registration copy (including household member information if necessary)
Employment and income verification documents:
Certificate of employment (specifying the SME currently employed by)
Income amount certificate or earned income withholding receipt (for checking the previous year’s income criteria)
Company-related verification documents:
Copy of business registration certificate (for checking whether the employing company has a partnership and the SME scale)
※ Depending on the bank or product type, a separate confirmation letter or official document submitted through the company (employer) may be required.
💡 Core Tip: Before preparing documents to visit a branch or apply via the app, we strongly recommend contacting the handling bank’s customer center first to check in advance whether your employing company is registered with the product subscription target code and if there are any additional company-related documents to submit.
Thorough preliminary preparation is the only shortcut to reducing stress in the subscription process and fully securing benefits. Then, what precautions must you keep in mind when maintaining it until the end after joining? We will examine this in detail in the next section.
Precautions & Net Benefit Analysis to Check Before Subscription
While it is true that SME employee preferential savings products are overwhelmingly more advantageous than ordinary installment savings, there are realistic details you must check before pressing the subscription button or starting the long race. We highlight the core checklist you must verify to prevent ending up in trouble midway or missing out on net benefits due to hasty subscription.
- Risk of Benefit Extermination and Disadvantage Upon Early Termination
The powerful interest rate preferential treatment or subsidy benefits of this product are mostly completed only when the ‘agreed period (maturity)’ is fully fulfilled. If you fail to fulfill the maturity due to personal circumstances and terminate early, the high preferential interest rate you expected will not be applied, and a general early termination interest rate will be applied, which can cause your actual yield to plummet. You must soberly evaluate whether the amount to be deposited every month during the subscription period is at a manageable level relative to your income.
- Comparison of Net Benefits with Other Government Support Policies (such as Youth Leap Account)
If you have already subscribed to other government-supported asset-building products such as the Youth Leap Account or Youth Tomorrow Savings Account and are depositing a substantial amount every month, you must compare whether there are duplicate subscription restriction regulations or if the savings amount exiting your paycheck becomes excessive and disrupts your daily life. Careful calculation is required to determine which product brings you the highest final return according to your income bracket and employment form.
- Impact of Company Changes (Job Change and Resignation)
SME employee preferential savings are basically designed based on the requirement of ‘SME employment’ in many cases. If you change jobs or resign during the subscription period, you must figure out in advance through the bank and HR manager what changes will occur to the preferential interest rate conditions or corporate-linked benefits of the account you have been maintaining.
💡 Wise Asset Management Tip: If the fixed monthly installment deposit amount feels burdensome, rather than blindly signing up for the maximum limit, it is much wiser to reduce hidden expenses from your paycheck and start with a realistic amount you can consistently maintain. Fulfilling maturity even with a slightly smaller amount is always the winning shortcut compared to terminating early.
If you have reduced risks through thorough net benefit analysis, we will now wrap up with a general summary of the core contents of this posting and share our closing remarks. It continues in the next section.
Conclusion: A Wise Way to Connect the Advantages of SME Employment to Asset Formation
For office workers living in an era full of high inflation and economic uncertainty, saving and asset building easily feel like a grueling and lonely battle. Especially for workers sweating silently in SME fields, preparing for the future amidst relatively scarce conditions may have felt even more daunting.
However, the ‘SME Employee Preferential Savings’ we examined together today is a solid wing prepared hand in hand by the state, the financial sector, and companies so that the efforts of these hardworking workers do not go to waste.
Core Summary to Remember:
You can maximize the speed of asset formation through extraordinary preferential interest rates and support benefits incomparable to ordinary installment savings.
You must accurately understand your own worker requirements and whether your employing company has a partnership agreement, and apply after thoroughly preparing the essential documents.
Rather than excessive deposits, you need the wisdom to set a realistic amount suited to your income and maintain it completely until maturity.
The fact that you are employed by an SME can go beyond the simple meaning of a workplace and become a powerful turning point for growing your assets. Please review the contents introduced today carefully and make a wise choice that will protect your precious wallet and future.
If you have any further questions or policies you would like to know about additionally, please feel free to leave a comment anytime. We sincerely cheer for your reliable asset building and vibrant work life. Thank you!
Korean version: 한국어로 읽기