Introduction: Why Do We Need ‘Beontimok Jeonse Loan Refinancing’ to Reduce Interest Burdens?
If you are someone who received a general jeonse loan from a commercial bank when finding a jeonse home or renewing a contract, you likely felt a heavy burden from the monthly interest payments due to the high-interest trend that has continued over the past few years.
To cover the increased interest driven by soaring benchmark interest rates, loan interest leaking out every month like monthly rent has become one of the biggest fixed expenditures weighing down household economies.
“The jeonse loan interest has gone up so much that my bank account is completely empty every month…”
“Isn’t there a way to switch to a government-supported product with a lower interest rate?”
The most powerful alternative for homeless working-class individuals using such high-interest commercial bank jeonse loans to dramatically ease their interest burden is ‘Beontimok Jeonse Loan Refinancing (Switching)’.
The Beontimok Jeonse Loan is a representative government-supported microfinance product backed by the Housing and Urban Fund, offering ultra-low interest rates in the 1~2% per annum range, which are much cheaper than commercial bank rates. Even if you are currently using a general loan with expensive interest, as long as you meet certain income and asset requirements, you can refinance to this product and dramatically reduce the interest expenses paid out every month.
Now, let’s carefully examine one by one whether you are included as a target for Beontimok Jeonse Loan refinancing, and what the specific income criteria and loan limits are.
Core Checkpoint ①: Basic Qualifications and Income Criteria for Beontimok Jeonse Loan Refinancing
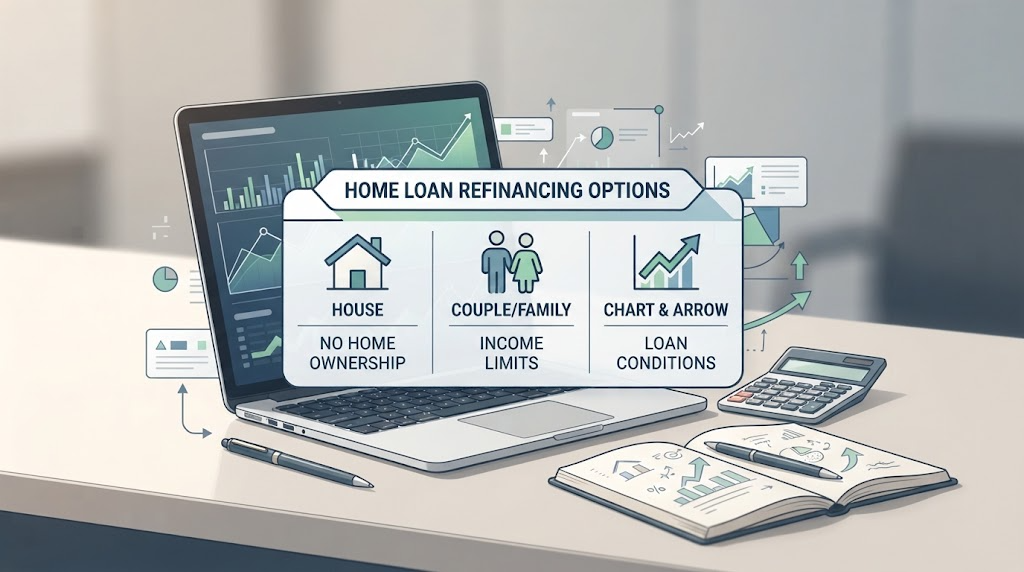
When considering Beontimok Jeonse Loan refinancing, the very first thing you must check is “Do I meet the basic government support requirements (homelessness, income, assets)?” As it is a public product operated by the Housing and Urban Fund, applicant qualifications are strictly screened, so careful verification is essential.
We have organized 3 core criteria for applying for Beontimok Jeonse Loan refinancing.
① Homeless householder requirement (All household members must be homeless)
Basic condition: Including the lessee (householder) of the housing for which refinancing is being applied, all household members must be homeless.
Even in the case of single-person households, certain requirements such as being age 30 or older must be met, and if there is a history of owning housing, you may be excluded from eligibility or exception rules must be strictly examined, so you must definitely check whether household members own housing based on the household member criteria before signing a contract.
② Combined annual income criteria for spouses (Differentially applied by household type)
Beontimok refinancing applies differential income criteria depending on the characteristics of the household. Compared to general households, more relaxed income criteria are applied to newlyweds or families with multiple children.
General households: Combined annual income of spouses 50 million KRW or less
Newlywed households (including prospective newlyweds): Combined annual income of spouses 70 million KRW or less
Households with 2 or more children / First-time homebuyers: Combined annual income of spouses 70 million KRW or less
Employees of public institutions relocated to innovative cities, migrants to other regions, etc.: Income criteria may be applied separately or given preferential treatment.
③ Combined net asset value criteria for spouses (Asset requirements)
You must meet not only income criteria but also asset ownership criteria. You must fall below the combined net asset value criteria stipulated by the Housing and Urban Fund (e.g., approximately the mid-to-upper 300 million KRW range based on the previous year) to be eligible for support.
If the net asset, which is the sum of real estate, automobiles, financial assets, and general assets minus liabilities, exceeds the standard, you will be excluded from low-interest refinancing eligibility, so it is safe to check the latest asset criteria in advance through the Fund Portal or HUG (Korea Housing & Urban Guarantee Corporation).
💡 Core Summary
Before knocking on the door of Beontimok refinancing, you must first verify through Employment24 or Fund Portal guidance whether our home is in a ‘all household members homeless’ status and complies with ‘combined spouse income and net asset criteria’.
Core Checkpoint ②: Examining Loan Limits and Interest Rate Benefit Conditions
If you have decided on Beontimok Jeonse Loan refinancing, you must specifically examine the ‘loan limit’—how much of your jeonse deposit you can actually receive refinancing support for—and the ‘interest rate benefits’ you can save every month. Check how advantageous conditions you can apply compared to commercial bank loans.
① Maximum loan limit (Differentially applied by region and household type)
The loan limit for Beontimok refinancing is applied differently depending on regional and household characteristics within a certain percentage of the lease deposit.
Metropolitan area (Seoul, Gyeonggi, Incheon) region:
General households: Up to within 120 million KRW
Newlywed households and multi-child households with 2 or more children: Up to within 300 million KRW
Local (non-metropolitan) region:
General households: Up to within 80 million KRW
Newlywed households and multi-child households with 2 or more children: Up to within 200 million KRW
※ However, since refinancing applications are only possible for housing where the total jeonse deposit is 300 million KRW or less (400 million KRW for newlyweds) in the metropolitan area and 200 million KRW or less (300 million KRW for newlyweds) in local areas, you must definitely check the deposit upper limit.
② Groundbreaking ultra-low interest rate benefits and additional preferential interest rates
Unlike commercial bank general jeonse loan interest rates exceeding the 4~5% per annum (or higher) range, Beontimok Jeonse Loans utilize Housing and Urban Fund resources, so very low interest rates are applied.
Base interest rate: Differentially applied according to combined spouse income and deposit brackets, but generally structured with groundbreaking ultra-low rates at the level of 1.5% ~ 2.7% per annum.
Application of additional preferential interest rates:
If you fall under categories such as housing stability monthly rent rebate recipients, real estate electronic contract signatories, multi-child households, or newlywed couples, you can receive additional preferential interest rates (0.1%p ~ 0.5%p, etc.) through duplicate application.
Depending on conditions, the interest rate can be lowered down to the early 1% per annum range, so compared to existing loan interest, you can sharply drop the monthly expenditure on interest by more than half.
💡 Core Summary
If your jeonse deposit falls within the support target limit (300 million KRW or less in the metropolitan area, etc.), you can maximize the benefits of switching to an ultra-low interest rate in the 1~2% range, which is half the commercial rate, while securing the maximum loan limit through Beontimok refinancing.
Practical Tips to Know: Precautions and Procedures When Applying for Refinancing (Switching)
Although Beontimok Jeonse Loan refinancing is a great means to reduce interest burdens, blindly knocking on bank doors can lead to unexpected hurdles. We have summarized 3 practical precautions and progress procedures that you must examine when clearing your existing loan and switching to a new fund loan.
① Comparing existing loan early repayment fees and actual benefits
If you are currently using a general jeonse loan at a commercial bank, early repayment fees (typically around 0.5% to 1%) may occur if the agreement period still remains.
You must carefully compare the total annual interest saved through refinancing with the fee costs incurred when early repaying the existing loan.
Sometimes incidental costs such as fees or guarantee fees can be greater, so it is safe to request a simulation in advance through a bank consultation window to see “how much the actual benefit is upon refinancing.”
② Fund loan preliminary screening (Whether HUG or HF guarantee certificates can be issued)
Beontimok Jeonse Loans are executed with guarantee certificates from the Korea Housing & Urban Guarantee Corporation (HUG) or Korea Housing Finance Corporation (HF) as collateral.
Depending on your credit score, existing loan balance, debt-to-income ratio (DSR or guarantee limit), desired guarantee certificates may not be issued or limits may be cut.
Therefore, before proceeding with the main contract or terminating the existing loan, it is essential to visit a fund trustee bank (Woori, KB Kookmin, Shinhan, NH Nonghyup, IBK Industrial Bank, etc.) and receive a preliminary loan screening (guarantee limit inquiry) first.
③ Matching the lease contract renewal timing and refinancing application timing
Beontimok refinancing cannot be applied for at any time, and in many cases, applications are only possible within a certain period before and after based on the lease contract renewal (use of contract renewal request right or re-contracting).
In addition, since procedures requiring the cooperation of the lessor (landlord) (such as deposit return account verification and lease verification) are necessary, you must visit the bank with plenty of time at least 1 to 2 months before the contract expiration date to prepare documents and coordinate schedules so that no disruptions occur in the balance payment date and refinancing timing.
💡 Core Summary
The core of successful refinancing is ‘analysis of interest reduction effect versus early repayment fee’ and ‘checking bank preliminary guarantee limits’. Please visit the bank in advance to test feasibility and proceed with switching according to the contract expiration timing.
Conclusion: Wisely Saving Interest Expenses Through Thorough Condition Verification
In a period of prolonged high interest rates, the jeonse loan interest leaking out of bank accounts every month acts as an enormous fixed expenditure burden on working-class households. At times like this, ‘Beontimok Jeonse Loan Refinancing’, which switches loans by actively utilizing government support benefits, can become the wisest and most powerful weapon to protect your wallet.
We summarize the core points we examined together today once again.
Fulfilling basic qualifications and income/asset requirements: Accurately check in advance the all-household-members homeless condition, combined income by household (50 million KRW or less for general, 70 million KRW or less for newlyweds/multi-child households), and net asset criteria.
Advantageous loan limits and groundbreaking interest rate benefits: Understand maximum limits by metropolitan and local regions (general 120 million KRW / up to 300 million KRW for newlyweds/multi-child households, etc.) and drastically lower your interest burden with ultra-low interest rates in the 1~2% per annum range.
Thorough advance inspection and timing coordination: Compare and analyze early repayment fees versus actual benefits, undergo preliminary guarantee limit screening through fund trustee banks, and proceed with refinancing without a hitch in line with the lease contract renewal timing.
Government-supported loans do not automatically flow into your bank account just by waiting idly; they finally become your benefit when you check your qualifications first and actively knock on the door. Using the guide provided today as your reliable compass, we sincerely hope you wisely reduce your monthly interest expenses and regain housing cost stability!
Korean version: 한국어로 읽기