Introduction: What is ‘Beontimok Jeonse Loan Refinancing’ That Reduces Interest Burdens?
Due to the high-interest-rate trend and fluctuations in Jeonse prices persisting over the past few years, tenants’ monthly interest burdens are growing day by day. Especially for those using general Jeonse loans from commercial banks, big sighs are often let out on the monthly interest payment date. One of the strongest alternatives to watch out for in times like this is ‘Beontimok Jeonse Loan Refinancing (Switching).’
The Beontimok Jeonse Loan is a representative housing support product for ordinary people and actual end-users supported by the Housing and Urban Fund, with its biggest feature being that it provides an interest rate significantly lower than those of commercial banks. Even if you previously received and used a Jeonse loan at a relatively high interest rate from a commercial bank or secondary financial sector, if you meet the requirements, you can refinance (switch) to the low-interest Beontimok product and drastically reduce your interest expenditures.
Then, what is the first wall you encounter when you actually try to switch? It is grasping the exact criteria of ‘whether I actually qualify’ and ‘what documents must be thoroughly prepared’ before visiting the bank.
In this posting, we will meticulously check everything from the core conditions for Beontimok Jeonse Loan refinancing to target qualifications and essential required documents for approval all at once. If you definitely want to save on the monthly outgoing interest costs, check out the information summarized today all the way to the end!
Eligibility Qualifications (Who Can Apply?)
To successfully proceed with Beontimok Jeonse Loan refinancing (switching), you must satisfy all the strict basic requirements and income/asset standards demanded by the Housing and Urban Fund. Shall we take a meticulous look item by item to see if I am also included in the application targets?
- Basic Requirements (Contract and Head of Household Criteria)
Head of Household Criterion: You must be a head of household who is an adult under the Civil Act as of the loan application date. (Head of household where all household members on the resident registration are homeowners without a house)
Prospective Head of Household: This also includes persons scheduled to become independent as a head of household within 1 month from the loan execution date, or persons recognized with status equivalent to a head of household.
Non-homeowner Criterion: All household members including the head of household must maintain a non-homeowner status until the time of applying for the loan.
- Income and Asset Criteria
As the Beontimok Jeonse Loan is a housing support product for the working class, upper limits exist for the household’s annual income and net assets.
Annual Income Criterion:
General Household: Annual income of 50 million KRW or less
Newlywed Household: Annual income of 60 million KRW or less (including prospective newlyweds)
Youth Household: (Separate criteria applied for youth-exclusive products) Generally, a combined annual income level of 50 million KRW or less is applied.
Net Asset Criterion: You must satisfy the net asset value of the criteria set by the Housing and Urban Fund (usually around the mid-300 million KRW range or lower based on the recent year, subject to change according to annual fund management guidelines). All assets including real estate, automobiles, financial assets, general assets, etc. are summed up and calculated by subtracting liabilities.
- Target Housing Criteria
The leased housing for which you wish to receive a loan (or are already residing in) must also satisfy certain criteria to become eligible for refinancing.
Lease Deposit Limit:
Metropolitan Area Criteria: General households 300 million KRW or less (Newlywed households 400 million KRW or less)
Non-Metropolitan Area Criteria: General households 200 million KRW or less (Newlywed households 300 million KRW or less)
Housing Exclusive Area: The leased exclusive area must correspond to the national housing scale (85 square meters or less, 100 square meters or less for eup/myeon regions). (However, a restriction of 60 square meters or less may apply in the case of a single-person head of household aged 25 or older)
If you have checked all of the above basic requirements (non-homeowner head of household), income and asset criteria, and housing deposit and area conditions, it is time to check the next steps: the specific refinancing execution conditions and existing loan liquidation procedures. Calculate in advance whether our home fits the conditions perfectly!
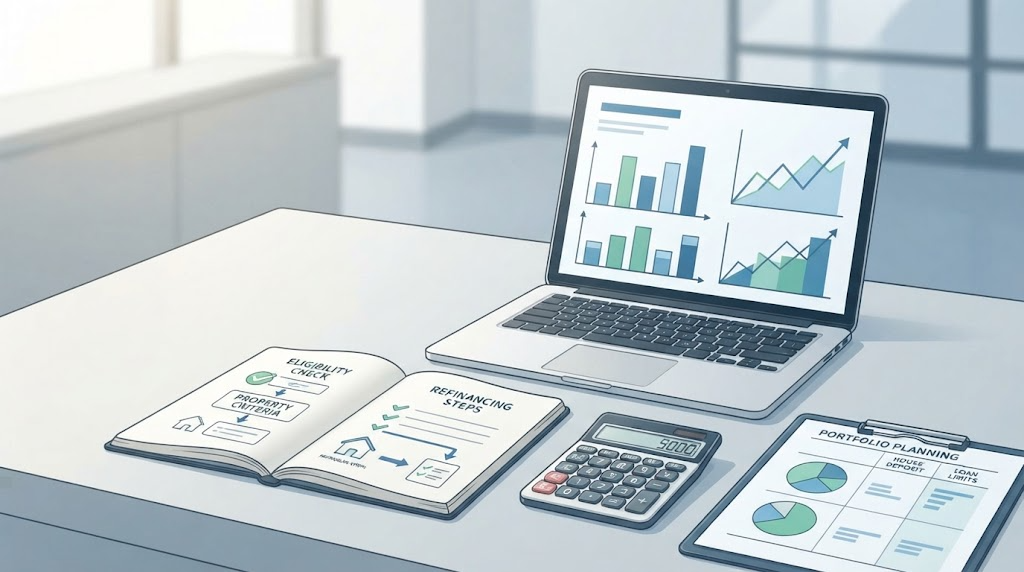
Core Refinancing Conditions (Under What Circumstances Can You Switch?)
Having meticulously checked the qualification requirements earlier, it is now time to check the most important practical gateway: the ‘Core Refinancing Conditions’. In a situation where you are already using a general Jeonse loan or a high-interest product from a commercial bank, we organize the specific criteria on when and how you can switch to the Beontimok Jeonse Loan.
- Existing Loan Possession and Switchability
Target Products: Tenants using commercial bank Jeonse loans or secondary financial sector Jeonse loans, rather than Housing and Urban Fund loans, are eligible.
Core of Refinancing: Beontimok Jeonse Loan refinancing is not simply the concept of extending an existing loan, but proceeds by fully repaying the existing expensive loan and newly switching to a low-interest product of the Housing and Urban Fund. Therefore, prior confirmation of whether the nature of the loan you currently hold complies with the fund loan conversion requirements is essential.
- Contract Renewal and Application Timing Requirements
New Contracts and Renewal Contracts: It is smoothest to pursue refinancing at the time of newly concluding a lease contract or tacitly renewing or re-contracting (contract renewal) an existing contract.
Application Feasible Timing:
Applying within 3 months from the earlier of the balance payment date on the lease contract and the resident registration transfer date complies with general fund loan application regulations.
In the case of renewal contracts, applications must be made within a certain period from the contract renewal date (or contract renewal conclusion date), so it is advisable to proceed with bank consultations with ample time around the contract maturity date or renewal timing.
- Checking Loan Limits and Interest Rate Benefits
Loan Limit: The maximum limit of the Beontimok Jeonse Loan is differentially applied depending on criteria such as 120 million KRW for general households in the metropolitan area (80 million KRW in non-metropolitan areas), 300 million KRW for newlywed households in the metropolitan area (200 million KRW in non-metropolitan areas), and youth household criteria. However, you cannot receive a loan exceeding the existing loan balance, and it is limited to the smaller amount within the limits of the existing loan balance and the lease deposit ratio (80% in the metropolitan area, 80% in non-metropolitan areas, etc.).
Interest Rate Level: Although differentially applied depending on annual income and deposit scale, a low interest rate in the late 1% to late 2% range per annum—much lower than commercial bank Jeonse loan interest rates—is applied, which can drastically lower the monthly outgoing interest burden.
Once you have grasped the core requirements and timing for refinancing, let’s thoroughly check in the next step what essential required documents must be prepared without omission before visiting the bank!
Comprehensive Summary of Essential Required Documents (Perfect Preparation Before Visit)
If you have made up your mind to proceed with Beontimok Jeonse Loan refinancing, meticulously gathering the necessary documents before visiting the bank branch is a core step that dictates screening and execution. Since missing documents can cause the hassle of having to visit the bank multiple times, try preparing perfectly based on the checklist below!
- Identification and Resident Registration-Related Documents
Resident Registration Card, Driver’s License, or Passport (for identity verification)
Resident Registration Copy (Deungbon): Must include address change history for the past 5 years or more, or allow verification of household member composition and transfer date. (Issued at community service centers or using Gov24)
Resident Registration Abstract (Chobon): Prepare as a full abstract including past address change history.
Certificate of Family Relations (Detailed): Essential for proving the relationship with the spouse and marital status if you are married or applying under newlywed qualifications.
- Income and Employment (Business) Proof Documents
For wage earners:
Certificate of Employment
Income Amount Certificate or Earned Income Withholding Receipt (including company seal)
Health Insurance Qualification Loss/Acquisition Confirmation Letter
For business income earners (self-employed):
Copy of Business Registration Certificate
Income Amount Certificate (issued by the tax office)
For persons without income (job seekers, full-time homemakers, etc.):
Certificate of Non-filing of Income Tax Return proving no income or related fact-finding documents.
- Housing and Lease Contract-Related Documents
Original Lease Contract with Fixed Date: Must be a formal lease contract concluded through a certified real estate agent, and a fixed date must be assigned.
Receipt for Payment of 5% or More of Lease Deposit: A receipt or account transfer confirmation proving payment of the contract deposit.
Real Estate Registry (Certified Copy of Register): Prepare a recently issued copy to check the ownership and rights relationship of the leased housing.
- Existing Loan-Related Documents (Core of Refinancing)
Existing Jeonse Loan Usage Confirmation Documents:
Financial Transaction Confirmation Certificate or Loan Balance Certificate issued by the financial institution currently providing your Jeonse loan.
Documents stating the loan account number and accurate virtual account number for repayment (essential for repaying the existing loan).
💡 Tip: All documents must be issued with resident registration numbers fully displayed (unmasked), and in principle, only documents issued within the past 1 month from community service centers, Gov24, or banks are recognized as valid. If you call the loan officer before visiting the bank to double-check if there are any additionally requested documents, it will be even more perfect!
Application Procedures and Precautions (Tips for Flawless Switching)
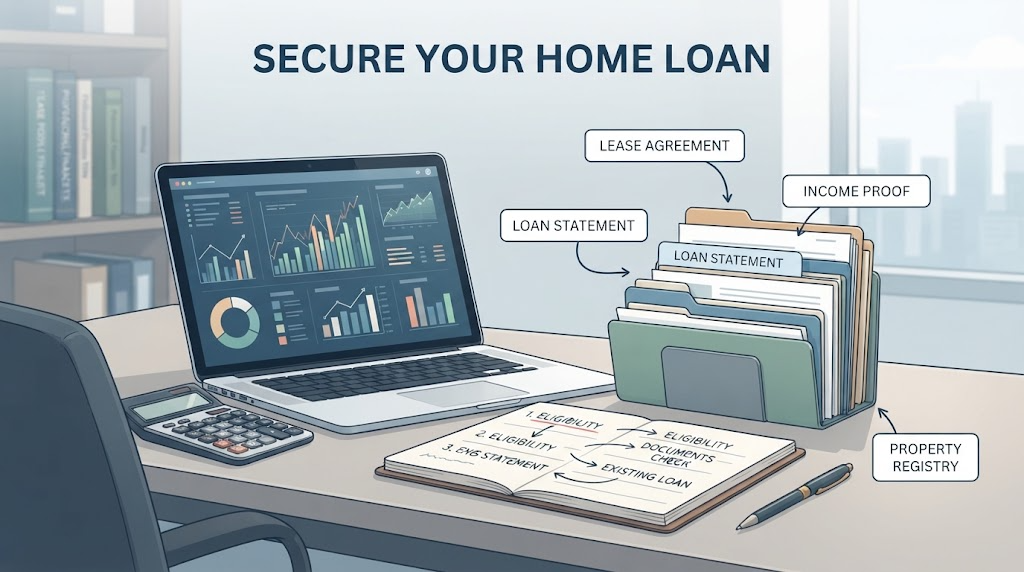
Unlike general new loans, Beontimok Jeonse Loan refinancing (switching) involves the process of neatly clearing your currently utilized loan and switching to a fund product, making accurate understanding of the procedures paramount above all else. We organize the step-by-step procedures and core tips for succeeding in a smooth switch without failure.
- Beontimok Jeonse Loan Refinancing Application Procedure
Step 1: GigimeDdeun Pre-application Online
After logging into the Housing and Urban Fund portal or the official ‘GigimeDdeun’ website (or app) using a joint certificate, select the Jeonse loan product (Beontimok) and proceed with the pre-application.
This is the first gateway to pass through because you must receive an ‘eligible’ judgment after qualification screening for the subsequent bank visit to go smoothly.
Step 2: Visiting the Entrusted Bank and Submitting Documents
Visit a branch of the entrusted bank (Woori, KB Kookmin, Shinhan, NH Nonghyup, IBK Industrial Bank, etc.) designated or intended to be visited after the GigimeDdeun screening.
Submit the previously prepared essential required documents (ID, income and employment proof, contract, existing loan balance certificate, etc.) and apply for the final loan screening.
Step 3: Final Screening and Loan Approval
The bank and the fund conduct final screenings regarding leased housing requirements, re-verification of income and assets, and whether existing loan repayment is possible.
Step 4: Existing Loan Repayment and New Loan Execution
Once the loan is approved, the Beontimok loan funds are executed on the designated date, and the existing commercial bank loan is fully repaid. In this process, if a difference occurs between the remaining principal of the existing loan and the Beontimok loan limit, a funding plan for this must be established in advance.
- Core Precautions for a Flawless Switch
Checking Existing Loan Early Repayment Fees
Commercial bank Jeonse loans usually incur an early repayment fee (around 0.5% to 1.2% level) if repaid early within a certain period (usually 2 to 3 years) after loan execution. You must meticulously compare the gains obtained from the interest rate reduction and the cost of the early repayment fee to weigh the net benefits.
Matching Application Timing and Balance/Renewal Dates
Since refinancing loans must proceed in line with the lease contract renewal timing or balance payment date, you must coordinate schedules so that the maturity date of the existing loan and the execution date of the new Beontimok loan mesh together without gaps. Move with ample time considering the bank screening period (typically takes 2 to 4 weeks).
Preparing for Limit Restrictions and Insufficient Funds
The Beontimok loan cannot be received exceeding the existing loan balance, and may hit fund regulation limits (120 million KRW for general metropolitan area, 300 million KRW for newlyweds, etc.) and deposit ratio restrictions. If the Beontimok limit comes out less than the existing loan amount, the difference must be directly repaid with your own cash, so you must pre-inquire about the available loan limit at the bank in advance.
If you meticulously check and prepare all procedures, you will be able to escape the high interest burden that choked your monthly life and enjoy housing stability with a much lighter heart. We cheer for your successful refinancing!
Conclusion: Maximizing Interest Rate Cut Effects
So far, we have meticulously looked at everything from target qualifications, core conditions, essential documents, to flaw-free application procedures for Beontimok Jeonse Loan refinancing.
Loan interest that goes out fixedly every month during high-interest periods places a considerable burden on the household economy. Especially if you were bearing the high interest rates of commercial banks as they were, just switching to the Housing and Urban Fund’s Beontimok Jeonse Loan can drastically reduce interest costs and give breathing room to your household finances every month.
Lastly, we summarize the core checklist for successful refinancing once again.
[Check 1] Re-verifying Qualification Requirements: Confirming satisfaction with the non-homeowner head of household criteria and combined couple’s income and net asset limits.
[Check 2] Checking Housing Criteria: Confirming lease deposit limits (metropolitan/non-metropolitan areas) and exclusive area requirements.
[Check 3] Calculating Net Benefits vs. Costs: Comparing the early repayment fee of the existing loan with the magnitude of interest saved through the interest rate cut.
[Check 4] Schedule Coordination: Managing a relaxed schedule considering the bank screening period (approx. 2 to 4 weeks) starting from the GigimeDdeun pre-application.
Although the preparation process may feel somewhat demanding, if you gather documents meticulously and proceed in order, you can successfully alleviate your interest burden. We hope the information guided today is of great help to your wise housing financial life and solid asset management!
Korean version: 한국어로 읽기