What is the Youth Beotimmok Jeonse Loan? (Support Target and Basic Conditions)
The “Youth Beotimmok Jeonse Loan” is a representative public jeonse fund loan product supported by the government to dramatically ease the housing cost burden of young professionals and homeless youth. Because you can receive jeonse deposit support at a much cheaper interest rate compared to general jeonse loans from commercial banks, it is one of the essential courses that young people preparing for independence look for first.
Support Target and Age Criteria: As a homeless household head (including prospective household heads) who executes a housing lease agreement and pays the lease deposit, youth aged 19 or older and up to 34 are eligible. (If military service obligations have been fulfilled, the age limit may be partially relaxed in proportion to the service period.)
Income Criteria: The combined annual income of the loan applicant and spouse must satisfy certain criteria (generally 50 million won or less, provided that the criteria may differ for newlyweds, public institution employees relocated to innovative cities, cross-region migrants, etc.). The door is fairly open to young professionals and job seekers as well.
Homeless Household Head Requirement: All household members must be homeless at the time of applying for the loan. If there is anyone who owns a house among not only yourself but also household members living together, you will be excluded from eligibility, so you must check whether all household members own a house before signing a contract.
Target Housing Criteria: It must be housing with a dedicated area of 85 square meters or less (including residential officetels), and the lease deposit must be below a certain amount (300 million won or less based on the metropolitan area, 200 million won or less based on local areas) to fully enjoy the benefits of the Youth Beotimmok Jeonse Loan.
As such, the Youth Beotimmok Jeonse Loan is a core product that acts as a reliable housing ladder for youth lacking lump-sum funds, provided they carefully satisfy the income, age, and housing requirements.
Maximum Loan Limit Structure by Jeonse Deposit Amount
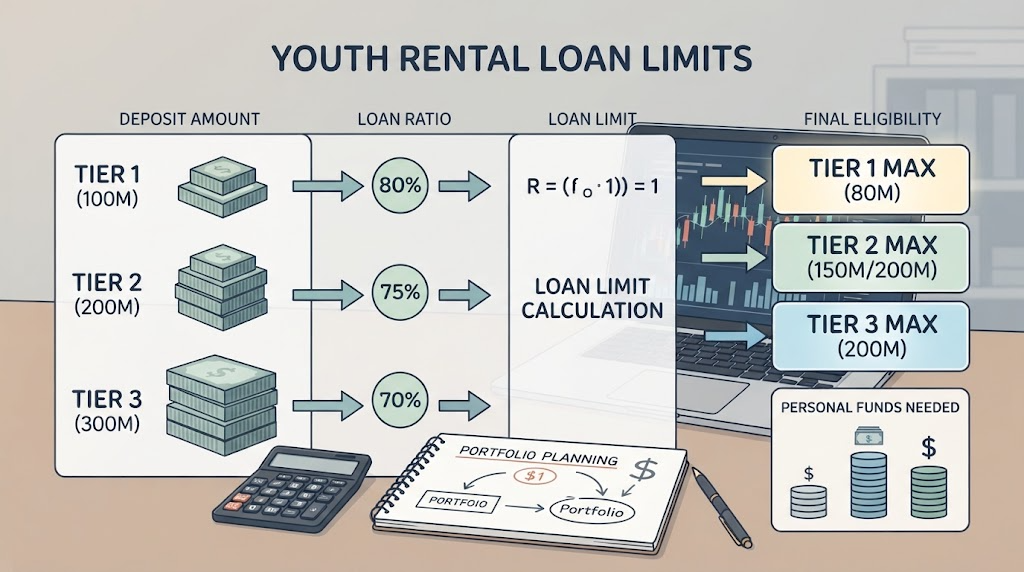
The biggest characteristic of the Youth Beotimmok Jeonse Loan is that a loan is not simply disbursed as much as you want, but rather the limit is ultimately determined by the smaller amount (minimum amount) between two criteria: ① the per-unit loan limit (maximum amount by age) and ② within 80% of the lease deposit. The specific loan limit calculation structure by deposit amount is as follows:
Basic Per-Unit Loan Limit Criteria by Age:
Youth aged 25 or older: Up to 200 million won or less
Single household head under 25 years old: Up to 150 million won or less (simultaneous application of housing area restriction of 60 square meters or less)
Application of 80% Loan Ratio Against Lease Deposit (Simulation by Deposit Amount):
Case A (When deposit is 150 million won or less):
Example: When finding a jeonse home with a deposit of 100 million won
Calculation: 80% of 100 million won = 80 million won
Result: Since the 80% amount is smaller than the per-unit limit (150 million/200 million), the final loan limit becomes 80 million won. (The remaining 20 million won requires personal funds)
Case B (When deposit is 200 million won):
Example: When finding a jeonse home with a deposit of 200 million won
Calculation: 80% of 200 million won = 160 million won
Result: If you are a youth aged 25 or older, you fall within the per-unit limit (200 million won), so the full 160 million won loan is possible. However, if you are a single household head under 25, you hit the maximum limit of 150 million won, so the final limit is restricted to 150 million won, and the difference of 50 million won must be prepared in cash.
Case C (When deposit is 300 million won – Youth Beotimmok Maximum Limit Criteria):
Example: When finding a jeonse home with a deposit of 300 million won (based on the 300 million won deposit ceiling for Youth Beotimmok target housing)
Calculation: 80% of 300 million won = 240 million won
Result: Since the 80% amount (240 million) exceeds the maximum per-unit limit for youth aged 25 or older (200 million won), the loan is approved only up to 200 million won, which is the lower amount according to regulations. In this case, to find a house with a 300 million won deposit, you must fill the remaining 100 million won excluding the 200 million won loan entirely with your own lump-sum money (or additional credit loans, etc.).
As such, as the jeonse deposit amount increases, a gap occurs between the limit based on the 80% ratio and the maximum limit set by the government (150 million to 200 million won). Therefore, it is essential to substitute your age and cash assets held before contract to pre-calculate the actual loanable amount.
3 Core Factors Determining Your Loan Limit
When applying for the Youth Beotimmok Jeonse Loan, if you carelessly assume that “my age matches and the deposit is within the criteria, so the maximum limit will come out,” you could face major difficulties. You must carefully examine the three core factors that actually determine your final loan limit during the bank screening process.
- Income and Debt Status (DSR and Repayment Capacity Screening):
Since the Youth Beotimmok Loan is a government-supported fund product, its income screening is relatively lenient compared to general jeonse loans from commercial banks. However, the applicant’s annual income and existing debt status (credit loans, minus accounts, card loans, etc.) directly affect the limit.
In particular, if you already carry excessive credit loans or debt, some amount may be deducted from the maximum fund loan limit, or you may be rejected in the guarantee screening of guarantee institutions (HUG, HF, etc.), so you must check your existing debt management status.
- Physical Requirements of the Housing (Dedicated Area and Deposit Ceiling):
The dedicated area and lease deposit amount of the jeonse home you wish to receive a loan for themselves serve as criteria determining loan availability and limits.
Basically, it must be housing with a dedicated area of 85 square meters or less (100 square meters or less for eup/myeon areas), and housing exceeding a deposit of 300 million won in the metropolitan area (200 million won in local areas) is completely excluded from the Youth Beotimmok Loan target. In addition, for single household heads under 25 years old, area restrictions are applied more strictly at 60 square meters or less, so you must definitely consider this point when finding a house.
- Loan Ratio Against Lease Deposit and Collateral Type (HUG vs HF):
Aside from the principle that loans are only available up to a maximum of 80% of the jeonse deposit as examined earlier, detailed limits and guarantee fee conditions vary depending on which guarantee institution (Korea Housing & Urban Guarantee Corporation HUG or Korea Housing Finance Corporation HF) you receive the loan through.
HUG (Korea Housing & Urban Guarantee Corporation): A product where the jeonse deposit return guarantee is subscribed to together, and the deposit loan limit is calculated taking into consideration home prices and senior claims.
HF (Korea Housing Finance Corporation): Since the guarantee limit is calculated based on the applicant’s income and credit score, for young professionals with low income or close to no income, the guarantee limit for the HF product may come out lower than expected.
As such, your annual income, the area and deposit of the house you are trying to find, and the characteristics of the chosen guarantee product intertwine to determine the final loan limit, so it is safe to comprehensively simulate various variables before contract.
How to Check Loan Limits and Calculate Expected Interest
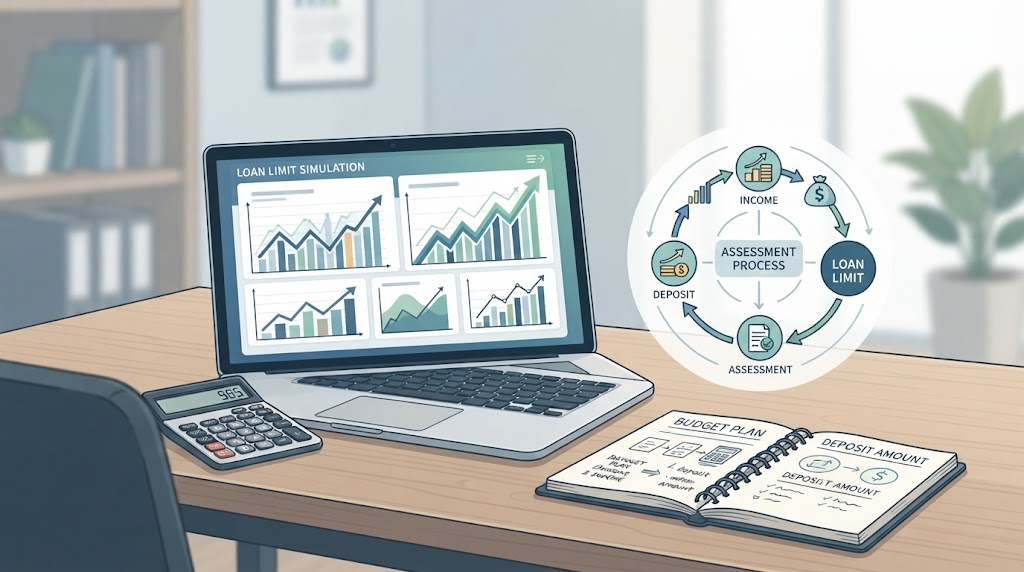
Before fully executing the Youth Beotimmok Jeonse Loan, the process of directly checking how much you can borrow and how much your monthly interest will be is essential. The ways you can easily simulate limits and interest at home before visiting a bank branch are as follows:
Pre-Limit Inquiry and Self-Diagnosis via the Internet (Housing and Urban Fund Portal):
Official Housing and Urban Fund Website (or Fund e-DeunDeun Portal): Search for “Housing and Urban Fund” on a portal site to access, then navigate to the [Personal Products] – [Jeonse Loan] – [Youth Beotimmok Jeonse Fund] menu.
Utilizing Self-Diagnosis Services: By simply entering the expected deposit, annual income, household head requirements, etc., you can carefully self-diagnose in advance whether you qualify for the loan target and what the rough expected limit is.
Non-face-to-face (Mobile) Inquiry and Preliminary Screening by Trustee Banks:
Limit inquiries are also possible through the mobile banking apps of the 5 major trustee banks handling the Youth Beotimmok Loan (Woori, KB Kookmin, NH Nonghyup, Shinhan, IBK Enterprise).
Recently, if you link MyData through loan/refinancing comparison platforms like Naver Pay, Toss, and Kakao Pay or bank app “jeonse loan limit inquiry” services, you can check more intuitive and faster expected limits based on your income and credit score.
Calculating Expected Interest Rates and Monthly Payment Interest for Youth Beotimmok Loans:
Interest Rate Level: The basic interest rate of the Youth Beotimmok Loan is very cheap, ranging from 2.0% to 3.1% per annum depending on the annual income bracket. (Can be lower when preferential interest rates are applied)
Expected Interest Calculation Example (Assuming a 2.5% loan interest rate):
If you executed a loan of 100 million won, the annual interest would be about 2.5 million won, and dividing this by 12 months means you only have to bear about 208,000 won in monthly interest.
Compared to general commercial jeonse loan interest rates hovering in the 4-5% range, you can dramatically reduce the monthly payment interest burden by more than half.
By understanding your loan limit and expected monthly interest scale in advance through preliminary inquiries, you can clearly set your budget range when looking around for jeonse homes, enabling a much more realistic and safe real estate contract.
Mistakes to Watch Out for During Limit Inquiries and Essential Checklist Before Application
Although the Youth Beotimmok Jeonse Loan is preferred by many young people due to its low interest rate and good conditions, there are quite a few cases where they suffer setbacks by missing minor mistakes during the limit inquiry process or document preparation stage. We have organized the mistakes you must avoid for successful loan approval and a checklist before application.
Mistake 1: Blindly Trusting Online Virtual Limit Inquiry Results 100%
Problem: The expected limit inquired on the Housing and Urban Fund portal or mobile app is merely a “virtual limit” calculated based on entered simple information (income, deposit, etc.). During actual bank screening, the limit can be significantly reduced or rejected depending on an individual’s hidden debt, credit score, and rights analysis results of the target housing (senior claims on the certified copy of the registry, etc.).
Coping Method: Use virtual limit inquiry results only for reference, and if you find a house you like, you must definitely visit a trustee bank branch or go through non-face-to-face preliminary screening before concluding the contract to probe actual loan availability.
Mistake 2: Paying a Provisional Deposit or Contract Deposit First and Looking Into Loans Later
Problem: If you impulsively remit a contract deposit to the landlord because you like the jeonse home and then apply for a loan, but the loan is rejected due to unexpected reasons (exceeding income, failing housing requirements, insufficient limit, etc.), you may not get the contract deposit back and suffer huge financial losses.
Coping Method: When drafting a real estate contract, it is safe to explicitly specify a special clause stating, “In case of non-approval of the Youth Beotimmok Jeonse Loan, the contract is null and void and the contract deposit is immediately returned.”
Mistake 3: Choosing Without Considering the Characteristics of Guarantee Institutions (HUG vs HF)
Problem: If you blindly choose a guarantee institution product that is not advantageous to your income or asset situation, you may be flustered when the guarantee limit does not come out as much as desired. For example, if a young professional with no income applies for an HF product, the guarantee limit may come out low.
Coping Method: Depending on whether you can prove your income and your workplace employment status, you must check in advance through bank consultation which product between HUG (Korea Housing & Urban Guarantee Corporation) and HF (Korea Housing Finance Corporation) is more advantageous and make a selection.
📌 Essential Checklist Before Applying for Youth Beotimmok Loan
- Check Homeless Status of All Household Members: Have you finally checked through Government 24, etc., to ensure there are no homeowners among household members on the resident registration copy?
- Satisfaction of Income and Asset Criteria: Is the combined annual income of spouses for the previous year within the standard (generally 50 million won or less) and does it satisfy asset criteria?
- Compliance with Target Housing Requirements: Does it fall under a home with a dedicated area of 85 square meters or less (60 square meters or less for those under 25) and a deposit of 300 million won or less in the metropolitan area (200 million won or less in local areas)?
- Confirmed Date on Lease Agreement and Payment of 5% or More Contract Deposit: After concluding a formal contract, have you paid 5% or more of the contract deposit and received a confirmed date?
- Securing Loan Application Timing: Are you preparing bank reception with plenty of time starting at least 1 month to 1 and a half months before the balance payment date?
Through meticulous preliminary preparation and thorough checklist verification, we hope you wisely alleviate your housing cost burden with the Youth Beuteumok Jeonse Loan!
Korean version: 한국어로 읽기